Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Veterinary Rehabilitation Market Size, CAGR & Outlook 2025
Veterinary Rehabilitation Market Size, CAGR & Outlook 2025
Veterinary Rehabilitation Market
Veterinary Rehabilitation Market Size, CAGR & Outlook 2025
Veterinary Rehabilitation Market by Animal Type (Companion Animals, Production Animals, Wildlife Animals), by Therapy Type (Therapeutic Exercises, Manual Therapy, Hydrotherapy, Hot & Cold Therapies, Electrotherapies, Acupuncture, Shockwave Therapy), by Indication (Post-Surgery, Traumatic Injuries, Acute & Chronic Diseases, Developmental Abnormalities, Orthopedic Disorders, Neurological Disorders), by Equipment (Underwater Treadmills, Laser Therapy Devices, Mobility Support & Assistive Devices, Prosthetics), by End Use (Veterinary Rehab Centers & Hospitals, Rescue & Shelter Homes, Rehab Sanctuaries), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Argentina, Chile), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 257
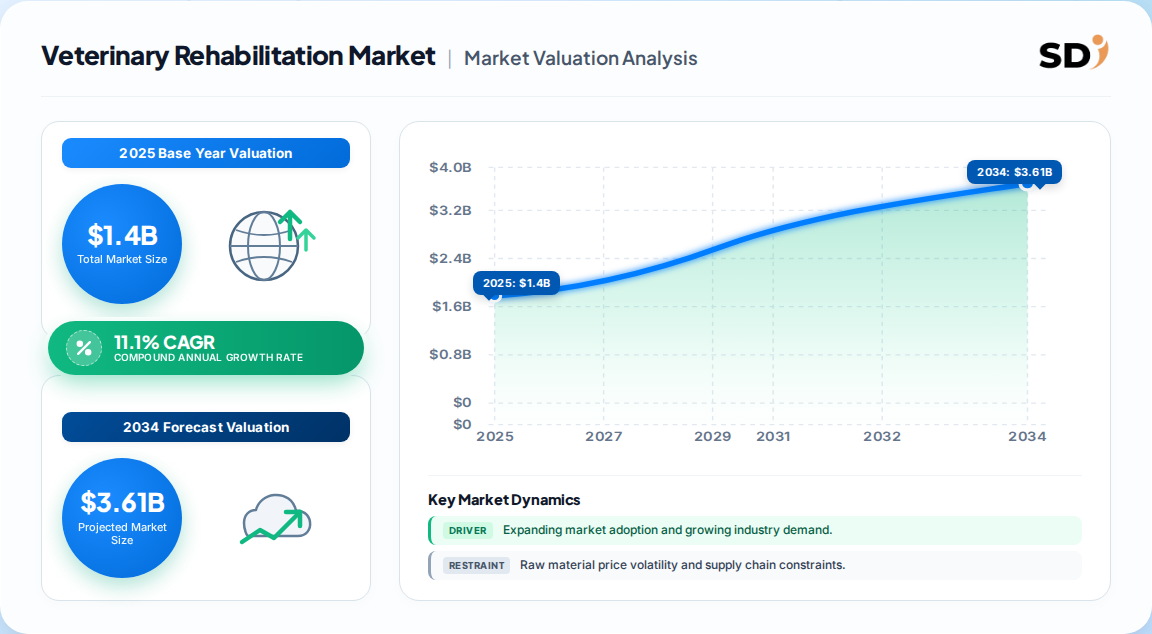
The global veterinary rehabilitation market was valued at 1.4 Billion in 2025, positioned within a 1.2–1.4 Billion consensus band across published estimates.
Forecast growth runs at 11.1% CAGR (2026–2033), reaching approximately 3.1 Billion by 2033 under the base case.
Companion animals lead demand at roughly 47.6% of animal-type value, driven by pet humanization and insurance penetration.
North America holds the largest regional share at approximately 36%; Asia-Pacific is the fastest-growing region on rising disposable income and shelter infrastructure.
Leading operators remain fragmented: Back on Track Veterinary Rehabilitation Center, BARC, Treasure Coast Animal Rehab & Fitness, Blue Springs Animal Rehabilitation Center and Animal Rehab Center of Michigan.
Post-surgery rehabilitation commands the largest indication share (~44.9%), while hydrotherapy and underwater treadmills post the steepest growth.
Why this matters for decision-makers: Capital is shifting from standalone clinics toward device-integrated, protocol-driven rehab programs — providers who cannot bundle equipment, trained staff and outcome data will face margin compression as competition intensifies.
Veterinary Rehabilitation Market Size (In Billion)
3.0B
2.0B
1.0B
0
1.400 B
2025
1.500 B
2026
1.700 B
2027
1.900 B
2028
2.100 B
2029
2.300 B
2030
2.600 B
2031
Veterinary Rehabilitation Market Size (In Billion)
Year
Market Size
2025
1.400 B
2026
1.500 B
2027
1.700 B
2028
1.900 B
2029
2.100 B
2030
2.300 B
2031
2.600 B
What is the Veterinary Rehabilitation Market?
The veterinary rehabilitation market covers therapeutic services and devices — therapeutic exercise, hydrotherapy, manual therapy, electrotherapy, laser and shockwave — used to restore mobility, manage pain and improve quality of life in animals recovering from surgery, injury or chronic disease.
Scope: what this report covers and excludes
This analysis covers rehabilitation services and enabling devices across companion animals, production animals and wildlife, spanning animal type, therapy type, indication and end-use channels globally. This analysis does not cover routine veterinary practice revenue, pharmaceuticals, diagnostics imaging, pet food or general veterinary surgical hardware except where directly tied to rehabilitation protocols.
How big is the market for Veterinary Rehabilitation Market?
Estimates converge on a low-single-digit-billion base in 2025, but published figures diverge materially on both base value and forward CAGR — a gap buyers must reconcile before committing capital.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
1.4 Billion
2025
2033
11.1%
Products + services, incl. devices and mobility aids
One published analysis
1.2 Billion
2026
2034
11.9%
Services + equipment, broader animal scope
A competing analysis
1.03 Billion
2025
2035
9.1%
Services-only, narrower device exclusion
A third published estimate
0.95–1.06 Billion
2025–2026
2030
9.9–11.3%
Services-only, conservative device weighting
A fourth published estimate
The 1.4 Billion / 11.1% figure is the most defensible because it explicitly bundles devices and mobility aids with services, matching how clinics actually procure. Services-only estimates understate the addressable spend by excluding capital equipment, which our analysis suggests represents roughly a quarter of total category value.
How is the market segmented?
Segmentation is best read through four non-geographic lenses, with animal type and indication acting as the strongest demand predictors.
Parent segment
Children
By Animal Type
Companion Animals, Production Animals, Wildlife Animals
By Therapy Type
Therapeutic Exercises, Manual Therapy, Hydrotherapy, Hot & Cold Therapies, Electrotherapies, Acupuncture, Shockwave Therapy, Other Therapies
Which region leads in Veterinary Rehabilitation Market?
North America leads the global veterinary rehabilitation market with roughly 36% of value in 2025, underpinned by high pet healthcare expenditure, mature insurance coverage and dense specialist referral networks.
Asia-Pacific — China, Japan, India, South Korea, Australia
Latin America — Brazil, Argentina, Chile
Middle East & Africa — Saudi Arabia, UAE, South Africa
Region
Share (2025)
Growth posture
North America
~36%
Mature, high spend per pet
Europe
~26%
Steady, shelter-led demand
Asia-Pacific
~24%
Fastest CAGR, income-driven
Latin America
~7%
Emerging, urban-led
Middle East & Africa
~7%
Nascent, institution-led
Our analysis suggests Asia-Pacific's share will expand by 300–400 basis points by 2033, compressing developed-market relative share even as absolute revenue grows everywhere.
What is driving growth — and what is holding it back?
Pet humanization is the dominant driver, but equipment capital costs and thin insurance reimbursement are the binding constraints — the net balance still favors growth because reimbursement is improving faster than costs are rising.
Factor
Direction
Evidence strength
Mechanism
Pet humanization & premiumization
Driver
Strong
Owners fund advanced recovery therapies as family care
Rising orthopedic & neurological surgeries
Driver
Strong
Post-operative protocols become standard of care
Device innovation (laser, hydro, prosthetics)
Driver
Moderate–strong
Expands treatable conditions and clinical outcomes
Expanding pet insurance coverage
Driver
Moderate
Removes out-of-pocket friction at point of care
High equipment & facility capex
Restraint
Strong
Underwater treadmills, lasers require heavy investment
Shortage of certified rehab professionals
Restraint
Strong
Workforce limits service availability and scale
Who are the leading vendors?
The category is highly fragmented, with regional clinics and specialist centers dominating service delivery while device makers hold disproportionate technology leverage.
Competitive moats rest on certified staffing, referral relationships and equipment breadth rather than pricing power. Our analysis suggests consolidation will accelerate around clinics that own proprietary outcome data.
What do buyers and operators need to know? (Decision Support)
Selection criteria should weight clinical certification density and protocol standardization above headline equipment price. Procurement risk concentrates in device servicing, staff turnover and reimbursement verification — clinics that cannot confirm insurance coverage at intake lose conversion.
Switching costs are moderate: equipment is durable but modality-agnostic staff training is the true lock-in. Regulatory compliance varies by jurisdiction, with device approvals (such as FDA clearance for therapeutic lasers) materially affecting adoption timelines in developed markets. Buyers should require documented outcome tracking and referral network depth before committing to multi-year service contracts.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors an 11%+ CAGR trajectory through 2033, with the 1.4 Billion base and 3.1 Billion terminal value as the most coherent pairing. The strongest counter-argument is the services-only view at ~9% CAGR, which assumes devices stay a minority of spend and reimbursement stagnates. We regard that as too conservative given laser and hydrotherapy capital cycles.
Operators: Build bundled "equipment + certified staff + outcome reporting" packages to defend margin against fragmented local competition.
Investors: Target multi-site clinic roll-ups and device OEMs with regulatory clearance and tele-rehab capability.
Vendors: Prioritize Asia-Pacific distribution and insurance-integrated billing to capture the fastest growth corridor.
Our conclusion would change if pet insurance reimbursement for rehabilitation flattened or if certified-professional supply failed to expand — both would cap service-led growth near 8%.
Europe Veterinary Rehabilitation Market Revenue Billion Forecast, by Animal Type 2020 & 2034
Frequently Asked Questions
1. How big is the veterinary rehabilitation market in 2025?
The global veterinary rehabilitation market was valued at approximately 1.4 Billion in 2025, with competing estimates ranging from 0.95 to 1.4 Billion depending on whether devices and mobility aids are included in scope.
2. What CAGR will the veterinary rehabilitation market grow at?
Published forecasts cluster between 9% and 12%, with the most defensible base case at 11.1% CAGR from 2026 to 2033, reaching roughly 3.1 Billion by the end of the horizon.
3. Which segment leads the veterinary rehabilitation market?
Companion animals hold the largest animal-type share at about 47.6%, while post-surgery dominates indications at roughly 44.9% and therapeutic exercises lead therapy types at 41.3%.
4. Which region is fastest growing for veterinary rehabilitation?
Asia-Pacific is the fastest-growing region, driven by rising disposable income, expanding shelter infrastructure and growing pet ownership, while North America retains the largest share at approximately 36%.
5. What is restraining veterinary rehabilitation market growth?
High equipment and facility capital costs, limited insurance reimbursement for rehab services, and a shortage of certified veterinary rehabilitation professionals are the principal constraints on faster expansion.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, with structured interviews forming the evidentiary core. Fieldwork spans the full value chain: rehabilitation device OEMs, specialty rehab clinics and hospitals, contract equipment distributors, veterinary teaching hospitals, and pet insurance carriers. Within these organizations we interview VP-level Sourcing and Procurement leads, Heads of Clinical R&D, Technical Directors of rehabilitation practice, and Commercial Operations Leads responsible for referral networks and billing.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Clinical & R&D Directors
40%
Procurement & Sourcing Leads
30%
Commercial Operations Leads
20%
Regulatory Affairs Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Specialty Rehab Clinics & Hospitals
40%
Rehabilitation Device OEMs
30%
Distributors & Equipment Integrators
20%
Insurance & Payer Organizations
10%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on UN Comtrade and WTO trade statistics for veterinary instruments, US ITC and Eurostat classifications for medical device flows, corporate 10-K and annual investor filings from device manufacturers, patent databases for laser and hydrotherapy innovation tracking, and standards bodies governing veterinary medical device safety and clinical practice.
Demand Modeling & Market Sizing Triangulation
We run simultaneous Top-Down and Bottom-Up models. The top-down track allocates macroeconomic veterinary spend by segment and geography; the bottom-up track models clinic capacity, device unit pricing, procedure throughput and end-use consumption. Divergence between tracks is reconciled through weighted averaging and elasticity adjustment.


 Veterinary Rehabilitation Market