 Latin America Ostomy Care Bags Market
 Report 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 196

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Latin America Ostomy Care Bags Market
Amit Mardhekar
Research Analyst

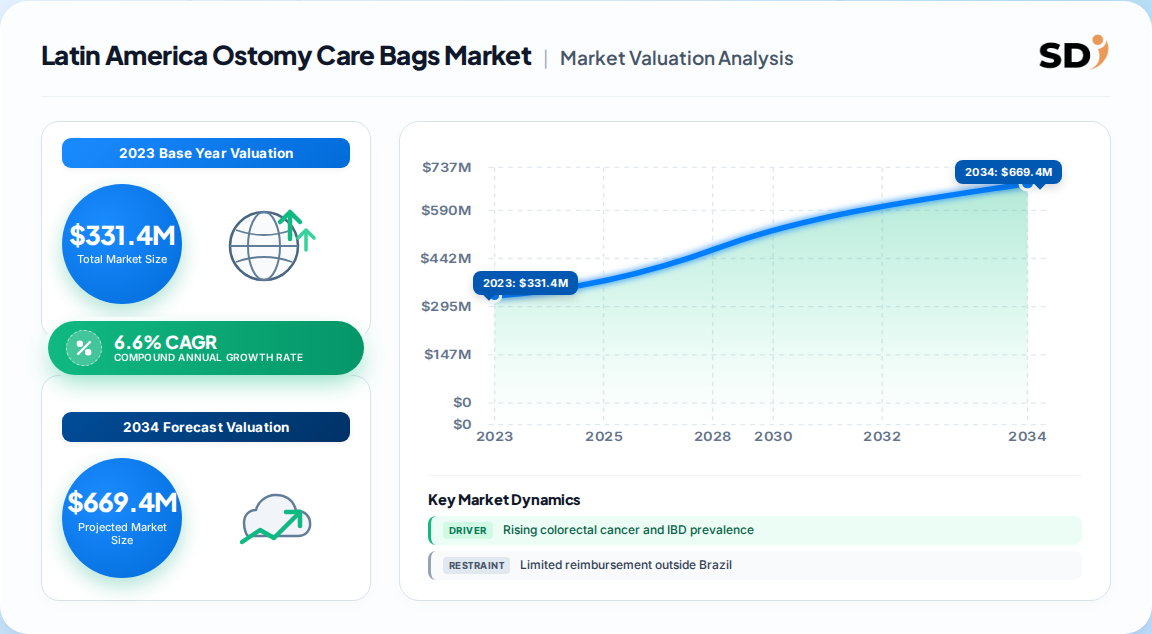
| Year | Market Size |
|---|---|
| 2023 | 331.0 M |
| 2024 | 353.0 M |
| 2025 | 377.0 M |
| 2026 | 402.0 M |
| 2027 | 428.0 M |
| 2028 | 456.0 M |
| 2029 | 486.0 M |

The Latin America ostomy care bags market covers pouching systems — colostomy, ileostomy, and urostomy bags in one-piece and two-piece formats — used by patients with surgically created stomas across Brazil, Mexico, Argentina, and neighboring economies, sold through hospital, home care, and public procurement channels.
This analysis covers ostomy pouching systems (colostomy, ileostomy, urostomy), one-piece and two-piece configurations, and the hospital, home care, and ambulatory end-use channels across Latin America. This analysis does not cover ostomy accessories (barrier rings, pastes, powders, deodorants), wound care, continence care, or surgical stapling devices.
One published estimate places the Latin America ostomy care bags market at USD 331.4 million in 2023, projecting a 6.6% CAGR from 2024 to 2030 — implying roughly USD 490–520 million by 2030. A competing global analysis sizes the worldwide ostomy drainage bag category at USD 3.1 billion in 2024 growing at 5.3%, which, applied to Latin America's typical 9–11% share of global medtech consumables, triangulates to a similar regional base.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 331.4 Million | 2023 | 2030 | 6.6% | Latin America ostomy care bags, all applications | One published estimate |
| USD 3.1 Billion (global) | 2024 | 2035 | 5.3% | Global ostomy drainage bags, all products | A competing analysis |
| USD 5.5 Billion (global) | 2035 | 2035 | — | Global ostomy drainage bags endpoint | A competing analysis |
| ~USD 340–360 Million (implied) | 2024 | — | — | Latin America share of global | Our triangulation |
The 6.6% regional figure is the most defensible: it sits materially above the 5.3% global CAGR, which is consistent with Latin America's younger patient base but expanding surgical capacity. Our analysis suggests the regional premium is driven less by prevalence than by channel formalization — public procurement converting previously out-of-pocket purchases into tracked volume.
Segmentation follows three non-geographic axes: clinical application, product configuration, and end-use setting — each with a distinct growth trajectory and reimbursement logic.
| Parent segment | Children | 2023 position | Growth signal |
|---|---|---|---|
| Application | Colostomy, Ileostomy, Urostomy | Ileostomy 42.3% | Urostomy fastest |
| Product | One-piece, Two-piece | One-piece dominant | Two-piece fastest |
| End use | Hospitals, Home care, Ambulatory | Home care dominant | Hospitals fastest |
Analytical implication: the fastest-growing child in each parent sits at the higher-complexity, higher-price end — urostomy (leak-defense tech), two-piece (skin-barrier preservation), hospitals (outcome-linked procurement). This is a mix-upgrade market, not a volume-only market, and pricing strategy should reflect it.
Brazil leads the Latin America ostomy care bags market with 37.8% of regional revenue in 2023, underpinned by Ministry of Health programs that extend ostomy provision through public and private facilities. Argentina is forecast to post the fastest CAGR, driven by diagnostic and surgical capacity expansion into underserved regions.
| Parent | Countries / sub-markets |
|---|---|
| Brazil | National (SUS-linked + private) |
| Mexico | National (IMSS, ISSSTE, private) |
| Argentina | National (fastest CAGR) |
| Colombia | National |
| Chile | National |
| Peru | National |
| Rest of Latin America | Ecuador, Uruguay, Paraguay, Central America, Caribbean |
Two structural features define the geography. First, public-payer concentration: in Brazil and Mexico, a handful of institutional buyers control the majority of formal volume, making tender capability a more decisive moat than brand marketing. Second, Argentina's growth is capacity-led, not demand-led — the constraints are surgical throughput and stoma-nurse availability, which means the fastest-CAGR market may also be the hardest to monetize near-term. Our analysis suggests treating Argentina as a 3–5 year positioning play rather than a near-term revenue driver.
Rising colorectal cancer and IBD incidence, aging populations, and public-program expansion are the dominant demand drivers, while reimbursement inconsistency, leakage complications, and out-of-pocket cost sensitivity constrain adoption — particularly outside Brazil.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Colorectal cancer & IBD prevalence | Driver | High | More ostomy surgeries → more pouching demand |
| Aging population | Driver | High | Age-related surgical need expands patient base |
| Public procurement expansion (Brazil) | Driver | High | Converts out-of-pocket to formal channel volume |
| Product innovation (leak defense, adhesives) | Driver | Medium-High | Reduces complications → higher compliance & trade-up |
| Telemedicine / home monitoring | Driver | Medium | Shifts care to home → home-care bag demand |
| Limited reimbursement outside Brazil | Restraint | Medium-High | Caps formal volume; pushes patients to grey/out-of-pocket |
| Leakage & peristomal skin complications | Restraint | Medium | Drives discontinuation and brand switching |
| Out-of-pocket cost sensitivity | Restraint | High | Suppresses two-piece and premium trade-up |
The balance of evidence favors demand-side strength over supply-side constraint. Surgery volumes are structurally rising; the binding constraint is payer coverage and stoma-nurse distribution, both of which are policy variables that can move faster than epidemiology. This is why the regional CAGR (6.6%) outperforms the global figure — it captures channel conversion, not just disease growth.
Three multinationals — Coloplast, Hollister, and Convatec — anchor the Latin America ostomy care bags market, competing primarily on product portfolios, adhesion technology, and the depth of their local distribution and tender relationships.
| Vendor | Portfolio emphasis | Differentiation | Regional moat |
|---|---|---|---|
| Coloplast Group | Full ostomy range, one- & two-piece | Adhesive and skin-barrier science | Deep distributor networks, tender history |
| Hollister Incorporated | Full ostomy range | Skin-friendly barriers, education programs | Established clinical relationships |
| Convatec Group PLC | Leak-defense systems, urostomy innovation | Esteem Body with Leak Defense (2024) | Innovation-led differentiation |
| Regional distributors | Multi-brand logistics | Procurement access, last-mile reach | Local payer relationships |
The moat is distribution and tender capability, not product novelty. Multinationals hold the technology edge, but access to Brazil's public channel and Mexico's institutional buyers is intermediated by local distributors — creating a durable structural advantage for incumbents and a barrier for new entrants. Our analysis suggests the most vulnerable position is a mid-tier global brand without local procurement infrastructure: strong product, weak channel.
Buyers should prioritize skin-barrier performance and leak reliability over unit price, because complication-driven discontinuation and re-admission costs outweigh per-bag savings. Procurement teams must evaluate total cost of care, not invoice cost — a lower-priced bag that drives peristomal skin breakdown erodes value within a single patient year.
Switching costs are concentrated at the patient-education layer. Ostomates trained on a specific pouching system resist change; converting a patient requires nurse re-training investment, which makes clinical education a genuine competitive weapon rather than a marketing expense.
Regulatory and compliance considerations are material: national device registries (ANVISA in Brazil, COFEPRIS in Mexico) govern import and sale, and tender participation typically requires local registration and often local inventory. Operators should map registration timelines before forecasting revenue — a 6-to-12 month registration lag can invalidate a near-term business case. Finally, reimbursement asymmetry means operators should model public and private channels separately, since pricing, volume, and margin profiles diverge sharply.
The balance of evidence favors a channel-first, mix-upgrade strategy over a volume-led land-grab. The 6.6% regional CAGR is real, but it is unevenly distributed: Brazil's public channel and the two-piece/urostomy mix shift are where growth actually monetizes, while Argentina's headline CAGR overstates near-term revenue.
The strongest counter-argument is that reimbursement reform or economic contraction could compress formal volume faster than disease growth adds it — a genuine risk given the region's history of currency volatility and fiscal pressure. We weight this as a timing risk, not a structural one: the underlying surgical demand does not disappear, it migrates to out-of-pocket and grey channels, which compresses price but preserves volume.
Actionable strategy for investors and operators:
Our conclusion would change if credible evidence emerged that public reimbursement in Brazil is contracting or that local manufacturing displaces imports at scale — either would shift the strategic priority from channel access to cost position. Precise sub-segment forecasting and country-level channel economics require the full report's granular modeling.
| Region | Market Share (%) |
|---|---|
| Brazil | 0.38% |
| Mexico | 0.21% |
| Argentina | 0.14% |
| Colombia | 0.09% |
| Chile | 0.07% |
| Peru | 0.05% |
| Rest of Latin America | 0.06% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.6% from 2020-2034 |
| Segmentation |
|
The Latin America ostomy care bags market was valued at USD 331.4 million in 2023 and is projected to grow at a 6.6% CAGR through 2030. Brazil accounts for the largest country share at 37.8% of regional revenue.
Ileostomy bags led the Latin America market with 42.3% revenue share in 2023, driven by improved healthcare infrastructure and patient education. Urostomy bags are forecast to grow fastest, supported by leak-defense innovations.
Argentina is anticipated to register the fastest CAGR in the region, driven by expanded diagnostic and surgical capacity and healthcare network extension into rural and underserved areas.
Coloplast Group, Hollister Incorporated, and Convatec Group PLC lead the Latin America ostomy care bags market, competing on adhesion technology, product breadth, and local distribution and tender relationships.
Rising colorectal cancer and inflammatory bowel disease prevalence, aging populations, public procurement expansion in Brazil, and product innovation reducing leakage and skin complications are the primary growth drivers.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across the ostomy care value chain, spanning raw material and medical-grade adhesive suppliers, specialized ostomy pouch producers, contract manufacturers, and regional medical-device distributors. Decision-maker interviews targeted VP-level Sourcing, Heads of R&D and Clinical Affairs, Technical Directors, and Commercial Operations Leads responsible for tender and channel strategy in Brazil, Mexico, and Argentina.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Commercial & Tender Operations Leads | 35% |
| R&D & Clinical Affairs Heads | 30% |
| Procurement & Sourcing Directors | 22% |
| Quality & Regulatory Managers | 13% |
| Company Type | Representation (%) |
|---|---|
| Ostomy Pouch Producers | 40% |
| Raw Material & Adhesive Suppliers | 25% |
| Regional Medical Distributors | 25% |
| Contract Manufacturers | 10% |
Findings were cross-validated against UN Comtrade medical-device trade flows, WTO tariff schedules, US ITC and Eurostat device trade data, corporate 10-K and SEC filings, annual investor presentations, patent databases, and recognized technical standards bodies and clinical associations relevant to ostomy and wound-ostomy continence care.
Top-down allocation used macroeconomic and healthcare-spend segmentation across Latin American economies. Bottom-up modeling used manufacturer capacity, product pricing by configuration, and end-use consumption by channel (hospital, home care, ambulatory). The two approaches were reconciled to a single base-year estimate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |