 Laboratory Equipment Market
: $50.3B Outlook to 2030
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 262

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Laboratory Equipment Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2022 | 28.00 B |
| 2023 | 30.10 B |
| 2024 | 32.40 B |
| 2025 | 34.90 B |
| 2026 | 37.50 B |
| 2027 | 40.40 B |
| 2028 | 43.50 B |

The laboratory equipment market encompasses instruments, apparatus, and workflow systems used in scientific, clinical, and industrial laboratories for sample preparation, analysis, measurement, and diagnostics. It spans general benchtop apparatus, analytical instruments, clinical diagnostic platforms, and specialty equipment serving research institutions, healthcare providers, and veterinary diagnostics.
This report covers the global laboratory equipment market across five product categories (general, analytical, clinical, support, and specialty equipment) and three primary end-use sectors (research institutions, healthcare, and veterinary). Regional coverage spans North America, Europe, Asia-Pacific, Latin America, and the Middle East & Africa. This analysis does not cover laboratory consumables and disposables as a standalone market, nor does it address laboratory information management systems (LIMS) software, laboratory furniture, or contract research services as distinct categories.
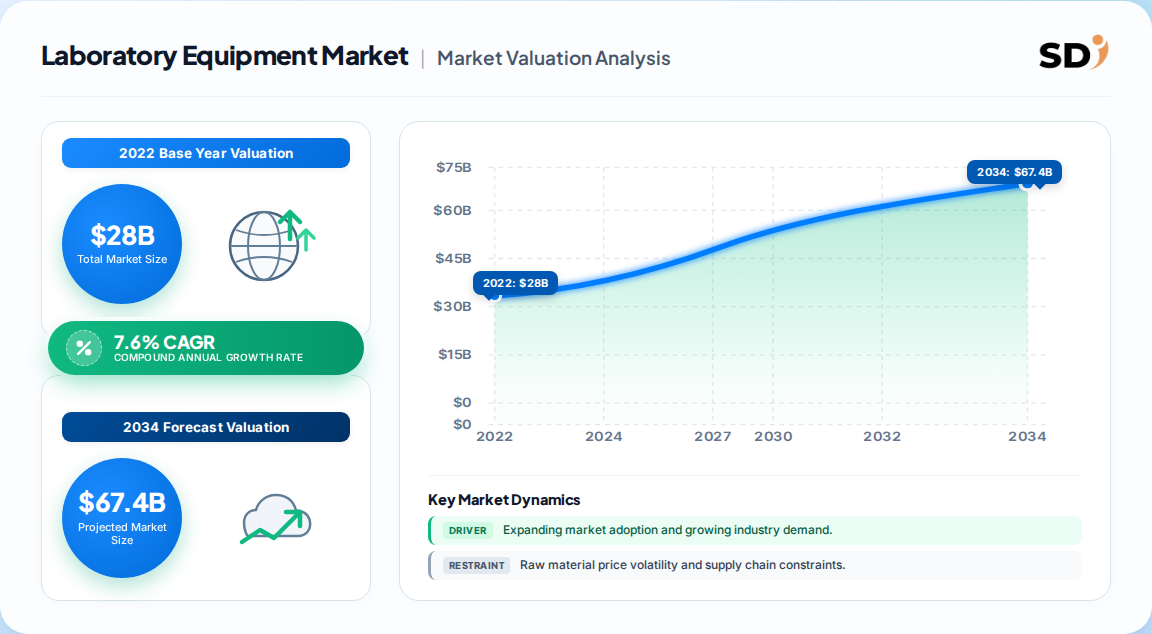
Published estimates diverge materially: one benchmark values the market at USD 28.0 billion (2022) with a 7.6% CAGR to 2030, while a competing analysis sizes it at USD 23.9 billion (2025) growing at 5.9% to 2035. The difference reflects scope definition — the higher-growth estimate includes broader specialty and clinical equipment categories.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 28.0B → USD 50.3B | 2022 | 2030 | 7.6% | General, analytical, clinical, support, specialty equipment | One published estimate |
| USD 23.9B → USD 42.3B | 2025 | 2035 | 5.9% | Analytical instruments, laboratory instruments, other equipment | A competing analysis |
| USD 43.2B → USD 75.3B (equipment + disposables) | 2025 | 2034 | 6.17% | Equipment and disposables combined | A third-party benchmark |
Our analysis suggests the 7.6% CAGR estimate is most defensible for buyers evaluating capital equipment procurement, because it captures the full breadth of clinical and specialty instrumentation. The 5.9% figure likely excludes several specialty categories and understates demand from veterinary and clinical diagnostics segments. The equipment-plus-disposables figure is useful directionally but conflates consumables-intensive revenue with capital equipment cycles.
The market is segmented by product type and end-use sector, with product categories ranging from general benchtop apparatus to highly specialized analytical and clinical instruments.
| Parent Segment | Children |
|---|---|
| By Product | General, Analytical, Clinical, Support, Specialty |
| By End-Use | Research Institutions, Healthcare, Veterinary |
| By Application | Biochemistry, Endocrinology, Microbiology, Genetic Testing, Others |
| By Mode | Manual, Semi-Automatic, Automatic |
General laboratory equipment held 31.1% share in 2022, reflecting its versatility across research fields. Analytical instruments are forecast to grow fastest, driven by chromatography, spectroscopy, and mass spectrometry demand in regulated workflows. The healthcare end-use segment dominated at 43.1% share, underpinned by diagnostic testing volumes and pharmaceutical R&D investment.
North America led the global laboratory equipment market with a 38.0% revenue share in 2022, driven by advanced healthcare infrastructure, concentrated pharma and biotech R&D spending, and strong government research funding. Asia-Pacific is the fastest-growing region, with China, India, and South Korea expanding clinical laboratory capacity.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.26% |
| Asia Pacific | 0.24% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
| Region | Share (2022/2025) |
|---|---|
| North America | 38% |
| Europe | 26% |
| Asia Pacific | 24% |
| Latin America | 7% |
| Middle East & Africa | 5% |
Nested geography:
Europe holds approximately 26% of spending, anchored by Horizon Europe research grants and IVD Regulation compliance upgrades. Asia-Pacific's growth is structural: China's National Health Commission mandate for ISO 15189 accreditation at county-level hospitals by 2027 is estimated to generate over USD 3.5 billion in new equipment procurement.
Biopharmaceutical R&D spending, which crossed USD 205 billion globally in 2024, is the dominant growth driver, complemented by rising non-communicable disease burden (41 million deaths annually per WHO) and accelerating laboratory automation adoption.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Biopharmaceutical R&D spending growth | Driver (+1.8% CAGR) | High | Expands demand for high-throughput screening, chromatography, analytical balances |
| Non-communicable disease burden | Driver (+1.5% CAGR) | High | Extends chemistry, hematology, molecular diagnostics capacity |
| Laboratory automation mandates | Driver (+1.0% CAGR) | Medium | Labor shortages drive sample-to-result platform procurement |
| Single-use technology adoption | Driver (+1.2% CAGR) | Medium | Shortens replacement cycles, increases consumables revenue density |
| Extended regulatory timelines (IVD) | Restraint (−0.7% CAGR) | Medium | Lengthens adoption cycles for regulated diagnostic platforms |
| Capital budget constraints | Restraint (−0.6% CAGR) | Medium | Limits modernization pace for smaller and public laboratories |
| Supply-chain concentration risk | Restraint (−0.4% CAGR) | Medium | Specialty reagent shortages constrain instrument utilization |
Our analysis suggests the net balance strongly favors growth: the combined driver impact (+7.7% directional) substantially outweighs restraint drag (−2.5% directional). However, the mechanism matters more than the magnitude — capital-constrained buyers are shifting toward shared laboratories, leasing, and phased automation, which redistributes demand toward service-supported procurement models rather than suppressing it.
Thermo Fisher Scientific leads with over 12% market share in 2025, and the top five players — Thermo Fisher, Agilent, Bruker, Danaher, and PerkinElmer — collectively hold approximately 40% of the market.
| Company | Positioning | Notable Strength |
|---|---|---|
| Thermo Fisher Scientific | Market leader (>12% share) | Broadest portfolio across analytical, clinical, and general equipment |
| Danaher Corporation | Top-tier diversified | Clinical diagnostics and life sciences instrumentation |
| Agilent Technologies | Analytical specialist | Chromatography, spectroscopy, mass spectrometry |
| Bruker Corporation | Scientific instruments | High-end analytical and materials characterization |
| PerkinElmer | Life sciences and diagnostics | Detection, imaging, and informatics integration |
Differentiation hinges on workflow integration rather than instrument performance alone. Vendors that connect analytical capability, automation, service, and data integrity command premium pricing. The top-five concentration (40%) leaves room for specialist providers solving defined bottlenecks — complex molecule characterization, controlled sample storage, or process monitoring — to compete on precision rather than scale.
Procurement decisions increasingly hinge on total cost of ownership and validation burden, not sticker price. Mass spectrometers, sequencers, and bioreactors can require investment beyond the reach of early-stage firms, shifting purchasing toward shared laboratories and phased automation. Buyers should prioritize instruments with clear utilization cases and strong validation documentation.
Regulatory compliance is a critical selection filter. The U.S. Quality Management System Regulation final rule incorporated ISO 13485:2016, requiring manufacturers to adapt documentation and quality-system practices. At the laboratory level, qualification spans installation, operational, and performance stages — a technically capable instrument may still be delayed if its software controls or auditability do not fit the buyer's validation requirements.
Switching costs are rising as laboratories standardize on integrated platforms. Once a lab commits to a vendor's workflow ecosystem, the cost of retraining staff, revalidating methods, and reconfiguring data pipelines creates meaningful lock-in. Our analysis suggests buyers should negotiate service-level agreements and data-portability terms upfront, because post-installation leverage diminishes sharply.
Supply-chain risk for specialty reagents remains a medium-term concern, particularly in Asia-Pacific. Operators should evaluate dual-sourcing strategies and vendor take-back programs, which are increasingly bundled into sustainability-linked procurement mandates.
The balance of evidence favors a 7–7.5% medium-term CAGR for the laboratory equipment market, anchored between the 5.9% conservative and 7.6% broad-scope estimates. The strongest counter-argument is that capital budget constraints in public hospitals and extended IVD regulatory timelines could suppress growth toward the lower bound, particularly in Latin America and the Middle East. But this is offset by structural demand from China's accreditation mandates and biopharma R&D expansion, which our analysis suggests will keep growth above 7% through 2030.
Actionable strategy for investors and operators:
What evidence would change our conclusion: A sustained decline in biopharma R&D spending below 3% annual growth, or a regulatory shock that extends IVD approval timelines by more than 18 months, would push the market toward the 5.5–6% range and favor consumables-led business models over capital equipment vendors.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.6% from 2020-2034 |
| Segmentation |
|
The global laboratory equipment market was valued at USD 28.0 billion in 2022 and is projected to reach USD 50.3 billion by 2030 at a 7.6% CAGR. A narrower-scope estimate puts 2025 size at USD 23.9 billion.
Published estimates range from 5.9% to 7.6% CAGR depending on scope. The broader estimate of 7.6% (2023–2030) captures clinical and specialty equipment, while the 5.9% figure reflects a narrower instrument-only definition.
North America led with 38.0% revenue share in 2022, driven by advanced healthcare infrastructure and concentrated pharma R&D spending. Asia-Pacific is the fastest-growing region, expanding at roughly 9.2% CAGR.
Thermo Fisher Scientific leads with over 12% market share. The top five — Thermo Fisher, Agilent, Bruker, Danaher, and PerkinElmer — collectively hold approximately 40% of the global market.
General laboratory equipment held 31.1% product share in 2022, while healthcare was the largest end-use at 43.1%. Analytical instruments and veterinary diagnostics are forecast as the fastest-growing segments through 2030.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology applies a 70/30 primary-to-secondary split, with in-depth interviews conducted across the laboratory equipment value chain. We engaged stakeholders from raw material and component suppliers, specialized instrument manufacturers, contract manufacturing organizations, and global distributors. Decision-maker designations interviewed included VP-level Sourcing Leads, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both procurement and technical validation perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Quality Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Instrument & Equipment Manufacturers | 45% |
| Component & Reagent Suppliers | 30% |
| Distributors & Channel Partners | 25% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and SEC 10-K disclosures, patent databases, and recognized technical standards bodies. Regulatory frameworks including ISO 13485:2016 and U.S. Quality Management System Regulation amendments were reviewed to assess compliance-driven procurement cycles. Industry association publications and peer-reviewed research on total laboratory automation informed workflow-adoption modeling.
We apply simultaneous top-down and bottom-up triangulation. Top-down modeling allocates macroeconomic healthcare and R&D expenditure across industry segments, while bottom-up modeling builds from manufacturer capacity, product pricing, and end-use consumption data. Divergences between the two approaches are reconciled through sensitivity analysis across base-year and forecast scenarios.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |