 Molecular Diagnostics Std Market
Molecular Diagnostics STD Market: 2025 Size & 8% CAGR Outlook
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 226

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Molecular Diagnostics Std Market
Amit Mardhekar
Research Analyst

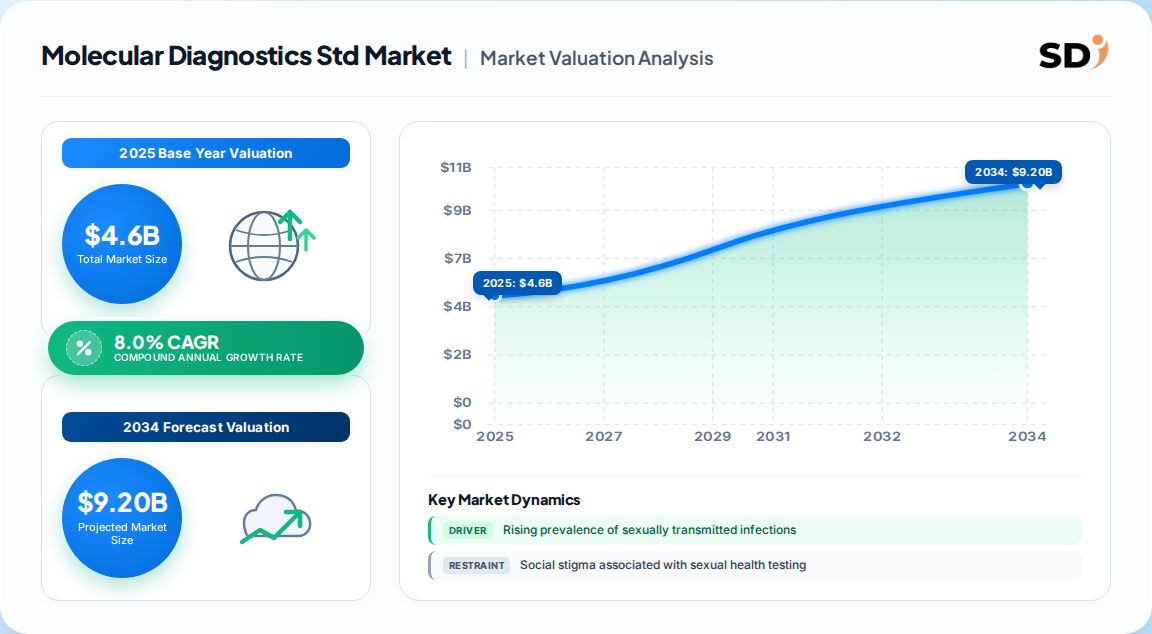
| Year | Market Size |
|---|---|
| 2025 | 4.600 B |
| 2026 | 4.970 B |
| 2027 | 5.360 B |
| 2028 | 5.790 B |
| 2029 | 6.260 B |
| 2030 | 6.760 B |
| 2031 | 7.300 B |

The molecular diagnostics STD market covers nucleic-acid-based tests—PCR, NAATs and sequencing—that detect pathogens such as chlamydia, gonorrhoea, syphilis, trichomonas, HPV and HIV. It includes instruments, reagents and kits, and software and services spanning central laboratories, point-of-care and self-testing settings.
This report covers molecular (nucleic-acid amplification and sequencing) diagnostic products and services for bacterial, viral and parasitic sexually transmitted infections across laboratory and decentralized settings. It excludes conventional culture, serology-only immunoassays, general molecular diagnostics for non-STI infectious diseases, and broader immunodiagnostics. This analysis does not cover adjacent markets such as at-home wellness panels or oncology molecular testing.
The most defensible 2025 base is approximately 4.6 Billion, derived by applying the molecular share (roughly 40%) to a total STD diagnostics base of 11.4 Billion, then growing at the stated 8% CAGR.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| ~4.6 Billion | 2025 | 2031 | 8.0% | Molecular STD diagnostics, global | Derived from one published STD diagnostics base and the stated molecular CAGR |
| 12.2 Billion (total STD diagnostics) | 2026 | 2033 | 7.1% | All STD diagnostics incl. immunoassay | A competing analysis, broad scope |
| 18 Billion (total molecular diagnostics) | 2026 | 2035 | 6.4% | All molecular diagnostics | Another published estimate, broad scope |
The narrower molecular STD figure is the most defensible because it isolates nucleic-acid testing and aligns with the stated 8% growth rate. The broader totals confirm direction, not the specific sub-segment size. Our analysis suggests buyers should anchor budgeting on the 4.6 Billion base and treat the 12.2 Billion total as the ceiling.
Segmentation follows product, application, testing mode and end user, with consumables and laboratory testing carrying the largest current revenue weight.
| Parent | Children |
|---|---|
| Product | Instruments, Consumables (Reagents & Kits), Software & Services |
| Application | CT/NG, Syphilis, Gonorrhoea, HPV, HIV, Trichomoniasis, HSV |
| Mode of Testing | Laboratory, Point-of-Care |
| End User | Hospitals, Diagnostic Laboratories, Decentralized Care Settings |
North America leads with roughly 42% of global revenue in 2025, supported by mature screening programs and automated laboratory infrastructure; Asia-Pacific is the fastest-growing region.
| Region | Market Share (%) |
|---|---|
| North America | 0.42% |
| Europe | 0.26% |
| Asia-Pacific | 0.22% |
| Latin America | 0.06% |
| Middle East & Africa | 0.04% |
| Region | 2025 share |
|---|---|
| North America | 42% |
| Europe | 26% |
| Asia-Pacific | 22% |
| Latin America | 6% |
| Middle East & Africa | 4% |
The gap between North America and Asia-Pacific implies that near-term revenue concentration remains Western, while medium-term volume growth shifts east. Vendors should hedge by maintaining US reimbursement strength while building low-cost, CLIA-waived or decentralized formats for Asian screening programs.
Growth is primarily driven by the high and rising burden of STIs, the shift to molecular testing and multiplex panels, and expansion of government screening programs; social stigma and reimbursement complexity are the key brakes.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising STI prevalence (over 1 million curable STIs daily, WHO) | Driver | High | Sustained testing volume across high-risk populations |
| Transition from culture to molecular methods | Driver | High | Higher sensitivity and faster turnaround |
| Multiplex and high-throughput adoption | Driver | High | Single-sample co-infection detection; lower cost per test |
| Government screening programs and funding | Driver | Medium-High | Structural demand, especially in Asia-Pacific |
| Social stigma around sexual-health testing | Restraint | Medium | Delays screening uptake; depresses demand |
| Reimbursement and coverage restrictions | Restraint | Medium-High | Limits novel assay commercialization (e.g., MolDX) |
The balance of evidence favors sustained growth, but the restraints are disproportionately powerful for new entrants. Stigma suppresses demand at the patient level, while reimbursement complexity suppresses supply at the vendor level. Our analysis suggests the net effect is a market that grows reliably for incumbents with reimbursed menus but remains difficult for novel assays to penetrate without payer evidence.
The market is led by Roche, Abbott, Hologic, Cepheid/Danaher and BD, with Qiagen, bioMérieux, Thermo Fisher, Seegene and DiaSorin competing on assay breadth and decentralized formats.
| Company | HQ | Positioning |
|---|---|---|
| F. Hoffmann-La Roche | Switzerland | Broad molecular menu, strong lab automation |
| Abbott Laboratories | USA | Integrated platforms, point-of-care reach |
| Hologic | USA | Women's health and STI assay leadership |
| Cepheid (Danaher) | USA | Cartridge-based PCR, decentralized footprint |
| BD | USA | Sample-to-answer and lab systems |
| Qiagen | Netherlands | Sample prep, NGS and PCR workflows |
| bioMérieux | France | Multiplex syndromic panels, CLIA-waived options |
| Thermo Fisher | USA | Broad PCR and sequencing portfolio |
| Seegene | South Korea | Multiplex assay breadth, price-competitive |
| DiaSorin | Italy | Specialty molecular and immunoassay |
Differentiation increasingly rests on assay-menu breadth, closed automated workflows and reimbursement coverage rather than instrument performance alone. Incumbents with installed bases convert consumables into recurring revenue, creating switching costs that protect share. Seegene's price-competitive multiplex strategy is the strongest counter-position, particularly in cost-sensitive Asian markets.
Buyers should prioritize total cost per reported result, not instrument price, because consumables represent about 70% of spend and lock in multi-year economics. Assay menu breadth matters most for laboratories handling co-infections, where multiplex consolidation reduces per-test cost and workflow burden.
Procurement risk centers on reimbursement: novel assays may face coverage delays or discontinuation, as seen with Medicare restrictions on certain tests. Switching costs are substantial once automation, middleware and electronic health record integration are installed. Regulatory compliance requires attention to FDA clearance, CLIA waiver status for decentralized formats, and local equivalent approvals. Operators should require vendor evidence of reimbursement pathway and validation studies before committing to platform lock-in.
The balance of evidence favors a steady-growth market with defensible incumbency. An 8% CAGR is credible because it rests on structural disease burden and an ongoing technology transition rather than speculative demand. The strongest counter-argument is that stigma and reimbursement friction could suppress realized growth toward 6%, especially for novel assays lacking payer evidence. Our analysis suggests the downside risk is concentrated in new entrants, not incumbents.
Second-order effects matter. Multiplex consolidation lowers cost per result and should accelerate laboratory adoption, but it also compresses per-test pricing and favors vendors with the broadest menus. Meanwhile, decentralized formats shift volume toward point-of-care, where CLIA-waived clearance becomes a competitive gate. Vendors that straddle both centralized and decentralized footprints are best positioned to capture incremental volume.
Evidence that would change our conclusion: a sharp slowdown in STI incidence, widespread reimbursement contraction across major payers, or faster-than-expected erosion of per-test pricing in multiplex panels. Precise sub-segment forecasting and vendor-level share analysis require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.0% from 2020-2034 |
| Segmentation |
|
The global market was approximately 4.6 Billion in 2025, representing the molecular (nucleic-acid) share of total STD diagnostics, growing at an 8% CAGR.
The market is projected to grow at an 8.0% CAGR through 2031, driven by rising STI prevalence, screening expansion and the shift from culture to molecular testing.
North America holds roughly 42% of global revenue, supported by mature screening programs and advanced laboratory infrastructure, while Asia-Pacific grows fastest.
Leading vendors include Roche, Abbott, Hologic, Cepheid/Danaher, BD, Qiagen, bioMérieux, Thermo Fisher, Seegene and DiaSorin, competing on assay breadth and automation.
Consumables, including reagents and assay kits, account for about 70% of revenue, making recurring kit sales the largest and most economically important product segment.
Social stigma around sexual-health testing and restrictive reimbursement policies are the primary restraints, delaying patient uptake and constraining commercialization of novel assays.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material and reagent suppliers, specialized assay producers, contract manufacturers, and global distributors. Decision-makers interviewed included VP-level sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads. Interviews validated assay menus, procurement cycles, reimbursement pathways and installed-base economics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Quality Affairs Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Reagent & Assay Kit Producers | 45% |
| Instrument & Platform Manufacturers | 30% |
| Distributors & Laboratory Service Providers | 25% |
We corroborated primary findings against official multilateral trade and standards databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K and SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. Public health surveillance data from WHO and CDC informed prevalence-driven demand assumptions.
We ran simultaneous Top-Down (macroeconomic and industry segment allocation) and Bottom-Up (manufacturer capacity, product pricing and end-use consumption) models. Triangulation reconciled total STD diagnostics spend with molecular-specific shares to isolate the nucleic-acid sub-segment.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |