 Asia Pacific Therapeutic Respiratory Devices Market
 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 231

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Asia Pacific Therapeutic Respiratory Devices Market
Amit Mardhekar
Research Analyst

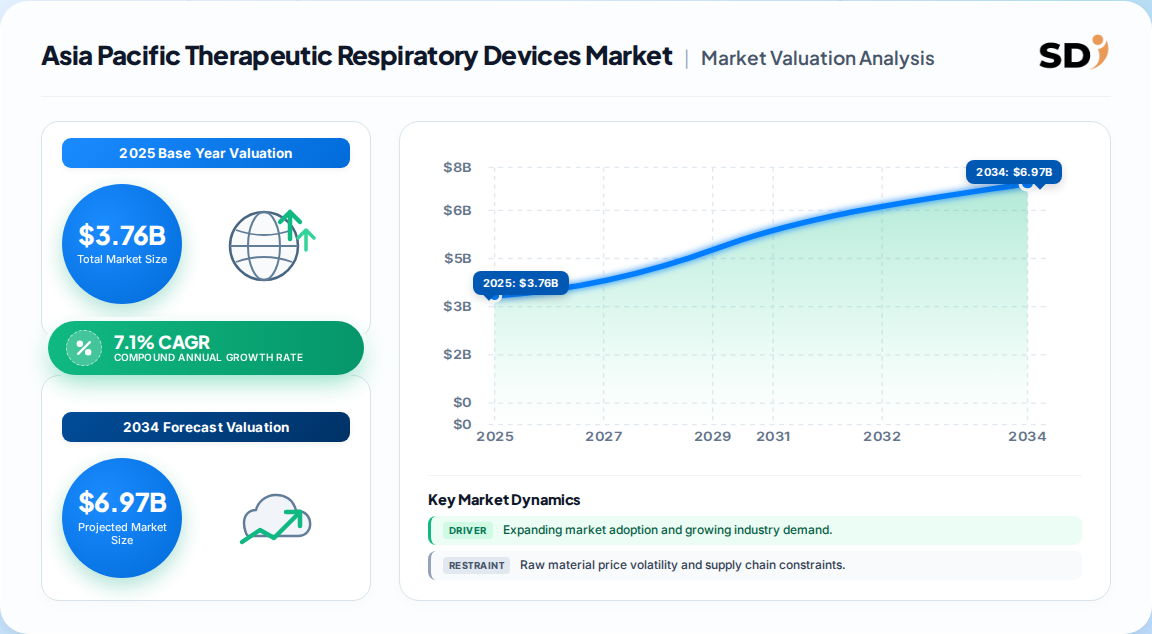
| Year | Market Size |
|---|---|
| 2024 | 3.510 B |
| 2025 | 3.760 B |
| 2026 | 4.030 B |
| 2027 | 4.310 B |
| 2028 | 4.620 B |
| 2029 | 4.950 B |
| 2030 | 5.300 B |

The Asia Pacific therapeutic respiratory devices market covers medical equipment used to treat, support, or manage respiratory conditions — including oxygen concentrators, ventilators, nebulizers, humidifiers, positive airway pressure devices, gas analyzers, and capnographs — sold to hospitals, home-care settings, and specialty clinics across the region.
This report assesses therapeutic (treatment-side) respiratory devices only: oxygen concentrators, ventilators, PAP devices, nebulizers, humidifiers, gas analyzers, and capnographs, segmented by technology and filter type across Asia Pacific countries. This analysis does not cover diagnostic-only imaging, sleep-lab services, pharmaceutical inhaler formulations, or non-respiratory critical-care capital equipment.
Published estimates cluster tightly around a USD 3.7–3.9 billion base year with a 7.1–7.2% CAGR to 2030, confirming a stable consensus view of roughly USD 6.0–6.1 billion by the end of the forecast horizon.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 3.9 Bn | 2023 | 2030 | 7.22% | Therapeutic devices incl. filters & technology split | One published estimate |
| USD 3.76 Bn | 2023 | 2030 | 7.1% | Therapeutic devices, seven product lines | A competing analysis |
| USD 6.07 Bn (2030) | 2023 | 2030 | 7.1% | Same scope, revenue endpoint only | Same competitor databook |
Our analysis treats the USD 3.76 billion / 7.1% line as most defensible: it reconciles product-level revenue with the 56.23% oxygen-concentrator share and avoids the double-counting risk embedded in broader "respiratory devices" totals that include diagnostics and monitoring. That divergence implies buyers should anchor procurement and investment models on the narrower therapeutic definition rather than headline respiratory-device figures, which can inflate the addressable pool by two to three times.
Segmentation follows four non-geographic axes — product type, technology, filter type, and (at geography level) country — with product type carrying the most commercial weight.
| Parent segment | Children |
|---|---|
| Product Type | Nebulizers, Humidifiers, Oxygen Concentrators, Positive Airway Pressure Devices, Ventilators, Gas Analyzers, Capnographs |
| Technology | Electrostatic Filtration, HEPA Filter Technology, Hollow Fiber Filtration, Microsphere Separation |
| Filters | Nebulizer, Humidifier, PAP Device, Oxygen Concentrator, Ventilator Filters |
Oxygen concentrators' 56.23% share is the single most decisive structural fact: it anchors revenue in home-care oxygen therapy rather than acute ventilators, which spiked in 2020–21 and have since normalized. Capnographs, though small, post the steepest growth curve — a signal that monitoring-adjacent therapeutics are the next competitive frontier.
China leads the Asia Pacific therapeutic respiratory devices market, holding the largest single-country revenue base on the back of ICU expansion under the Thousand County Project, rising disposable incomes, and government-backed procurement; India follows as the fastest-growing market.
| Country | Est. regional share |
|---|---|
| China | 34% |
| India | 19% |
| Japan | 16% |
| South Korea | 9% |
| Australia | 7% |
| Rest of Asia Pacific | 15% |
The implication is a two-speed market: China supplies scale and Japan supplies premium margin, while India supplies the growth vector. Our analysis suggests vendors who treat "Asia Pacific" as one pricing tier will lose share in India to local and Chinese manufacturers and lose margin in Japan to incumbents with installed-base lock-in.
Growth is driven primarily by chronic disease burden and government-funded respiratory infrastructure, while the strongest brakes are capital cost, maintenance burden, and skilled-staff shortages in lower-tier facilities.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising COPD/asthma/sleep-apnea prevalence | Driver | High | Long-term therapy and oxygen demand |
| Ageing population | Driver | High | Chronic home-care device adoption |
| Government ICU & county-hospital programs | Driver | High | Public procurement volume |
| Air pollution & tobacco use | Driver | Medium-high | Disease incidence escalation |
| Home-care and telemedicine expansion | Driver | Medium | Channel widening in remote areas |
| High equipment and maintenance cost | Restraint | High | Budget caps in developing economies |
| Skilled respiratory professional shortage | Restraint | Medium-high | Under-utilization of installed base |
| Reimbursement limitations | Restraint | Medium | Slower premium-device adoption |
The balance favors growth, but with an important second-order effect: post-pandemic ventilator stockpiles have depressed near-term acute-care orders, pushing revenue toward consumables, filters, and home-therapy devices. This divergence implies that vendors with filter and consumable annuity streams — not one-off ventilator sales — will show the most resilient revenue through 2027.
The competitive field is highly fragmented but multinational-dominated, with ResMed, Philips, Medtronic, and Fisher & Paykel anchoring therapeutic categories and Mindray gaining ground on domestic cost advantage.
| Company | Home base | Notable strength |
|---|---|---|
| ResMed | US | PAP devices, connected sleep therapy |
| Koninklijke Philips | Netherlands | Oxygen concentrators, ventilators, connected care |
| Medtronic | Ireland/US | Ventilation and airway management |
| Fisher & Paykel Healthcare | New Zealand | Humidification and non-invasive support |
| GE HealthCare | US | Critical-care monitoring integration |
| Drägerwerk | Germany | High-acuity ventilation |
| Mindray | China | Domestic cost-competitive ICU devices |
| Linde | UK | Oxygen supply and concentrator network |
Competitive moats rest on installed-base service contracts, consumable lock-in (filters, circuits, masks), and regulatory approvals rather than hardware spec alone. Our analysis suggests the most durable moat in this region is the combination of a filter/consumable annuity with a connected-care software layer — the model that converts a device sale into a multi-year revenue relationship.
Procurement in this region is unforgiving on total cost of ownership. Oxygen concentrators and ventilators carry multi-year filter, sieve-bed, and service costs that frequently exceed the initial capital outlay, so tender evaluation must score consumable pricing and service response separately from device price. Second, regulatory pathways diverge materially — Chinese NMPA registration, Indian CDSCO licensing, and Japanese PMDA approval are non-transferable — creating launch sequencing risk and lengthening time-to-revenue for new entrants. Third, power reliability and consumable supply chains in rural India and Southeast Asia favor devices with low power draw, local service depots, and standardized parts. Operators should also model switching costs carefully: once a hospital standardizes on one ventilation platform, retraining and spare-parts standardization make replacement expensive, which favors incumbents but also creates an opening for vendors offering interoperability and open data protocols.
The balance of evidence favors home-and-chronic care over acute capital: oxygen concentrators already hold 56.23% of regional revenue, and the post-COVID ventilator correction means acute-device demand is mean-reverting while chronic therapy needs compound. Vendors and investors should weight portfolios toward portable oxygen, PAP, and consumable filters rather than high-acuity ICU hardware. The strongest counter-argument is that government ICU expansion programs in China and India will re-stimulate acute-device procurement — a real effect, but one that is project-driven and lumpy rather than a durable annual growth engine.
Geographically, the data supports a "China scale, India growth, Japan margin" strategy. India's highest-CAGR status is well supported by disease burden and affordability-led volume, but it rewards local manufacturing and price-tiered products far more than imported premium devices. Our analysis suggests the smartest entry structure is a China-based manufacturing footprint paired with an India-focused distribution and service network, capturing both cost position and growth.
Actionable Strategy
We would revise this conclusion upward for acute-care devices if county-level ICU procurement in China accelerates materially, or if reimbursement for home oxygen therapy expands in India; conversely, a sustained price war among Chinese device makers would compress the home-care segment's margin outlook.
| Region | Market Share (%) |
|---|---|
| China | 0.34% |
| India | 0.19% |
| Japan | 0.16% |
| South Korea | 0.09% |
| Australia | 0.07% |
| Rest of Asia Pacific | 0.15% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.1% from 2020-2034 |
| Segmentation |
|
It was valued at roughly USD 3.76 billion in the base year and is projected to reach about USD 6.07 billion by 2030, growing at a 7.1% CAGR across the seven-year forecast.
Capnographs register the fastest growth, while oxygen concentrators dominate revenue at 56.23% share, reflecting strong demand for at-home oxygen therapy.
China holds the largest revenue base, supported by county-level ICU expansion and government procurement. India is the fastest-growing country market through 2030.
Leading players include ResMed, Koninklijke Philips, Medtronic, Fisher & Paykel Healthcare, GE HealthCare, Drägerwerk, Mindray, and Linde, competing on installed-base service and consumables.
High equipment and maintenance costs, skilled respiratory professional shortages, and reimbursement limitations in developing economies slow premium-device adoption across parts of the region.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split. In-depth interviews were conducted across the respiratory device value chain with device OEMs, component and filter suppliers, contract manufacturers, and regional distributors. Decision-maker designations interviewed include VP-level sourcing leads, heads of R&D and product engineering, technical directors, and commercial operations leads responsible for hospital and home-care channels.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement Leads | 35% |
| R&D & Product Engineering Heads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Quality Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Device OEMs | 40% |
| Component & Filter Suppliers | 25% |
| Contract Manufacturers | 20% |
| Regional Distributors | 15% |
We triangulate against UN Comtrade and WTO medical-device trade flows, national regulator databases (NMPA, CDSCO, PMDA), corporate 10-K and annual investor filings, patent databases, and non-profit technical standards from ISO and regional respiratory-care associations. No competitor market-research publications are used as validation inputs.
Top-down macroeconomic allocation (healthcare spend, disease prevalence, device penetration) runs simultaneously with bottom-up modeling of manufacturer capacity, product pricing, and end-use consumption. Divergences between the two are resolved through segment-level reconciliation and expert re-interview.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |