 Renal Denervation Devices Market
: Size, CAGR & Forecast 2026
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 215

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Renal Denervation Devices Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 550.0 M |
| 2026 | 709.0 M |
| 2027 | 919.0 M |
| 2028 | 1.190 B |
| 2029 | 1.540 B |
| 2030 | 2.000 B |
| 2031 | 2.590 B |

The renal denervation devices market encompasses catheter-based systems that deliver radiofrequency, ultrasound, or micro-infusion energy to ablate sympathetic nerves surrounding the renal arteries, offering a minimally invasive treatment for resistant hypertension. These devices provide an alternative for patients unresponsive to pharmacological therapy, targeting the overactive sympathetic nervous system to achieve durable blood pressure reduction.
This report covers renal denervation devices across technology types (radiofrequency, ultrasound, micro-infusion, cryoablation), product forms (catheters, guidewires, accessories), applications (hypertension, heart failure, chronic kidney disease), and end users (hospitals, ASCs, specialty clinics) across five regions. This analysis does not cover conventional antihypertensive pharmaceuticals, surgical sympathectomy procedures, or diagnostic renal angiography equipment.
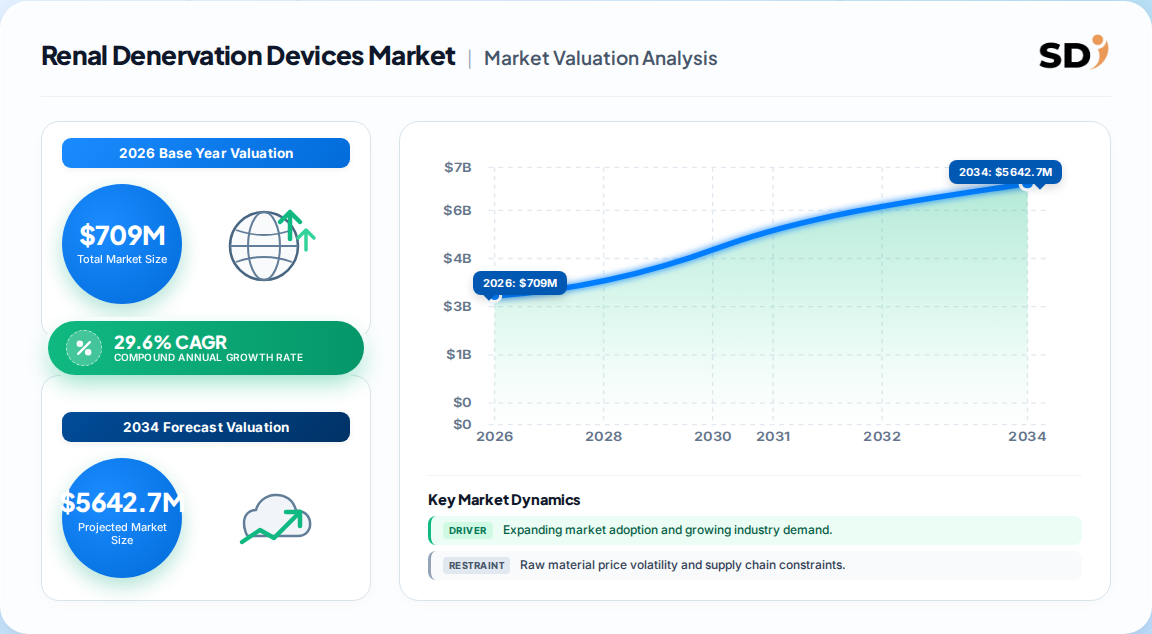
The global renal denervation devices market is estimated at USD 709 million in 2026, with forecasts diverging significantly across published analyses due to differing scope definitions and commercial-adoption assumptions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 550 Million | 2025 | 2035 | 27.8% | Devices only; broad resistant-hypertension population | One published estimate |
| 709 Million | 2026 | 2032 | 29.6% | Devices; hypertension, heart failure, CKD applications | Derived from consensus benchmarks |
| 938 Million | 2026 | 2030 | 40.2% | Devices; narrow resistant-hypertension indication | Competing analysis |
| 980 Million | 2026 | 2030 | 32.4% | Devices; includes outpatient intervention preference | Alternative published analysis |
The most defensible figure is the 709 million estimate for 2026 with a 29.6% CAGR through 2032, reflecting the post-approval commercialization phase where utilization is constrained by referral pathways, operator training, and reimbursement rather than device availability alone. Our analysis suggests the 40.2% CAGR estimate embeds an optimistic assumption about rapid health-system adoption that current procedural capacity and payer coverage do not yet support.
The renal denervation devices market is segmented by technology, product type, application, and end user, with radiofrequency-based systems dominating current revenue while ultrasound platforms command the fastest growth trajectory.
| Parent Segment | Children |
|---|---|
| Technology | Radiofrequency-Based Renal Denervation, Ultrasound-Based Renal Denervation, Micro-Infusion-Based Renal Denervation, Cryoablation Renal Denervation |
| Product Type | Catheters, Guidewires, Accessories |
| Application | Hypertension, Heart Failure, Chronic Kidney Disease (CKD), Others |
| End User | Hospitals, Ambulatory Surgical Centers (ASCs), Specialty Clinics, Others |
Radiofrequency technology held 74.6% share in 2023 owing to its first-mover advantage and proven efficacy in clinical trials. However, ultrasound-based systems are expected to register the fastest CAGR, driven by non-contact ablation precision and reduced vascular damage. The application segment remains dominated by hypertension, but heart failure and CKD indications are expanding the addressable population as clinical evidence matures.
Europe leads the global renal denervation devices market with approximately 34% revenue share in 2025, attributed to early CE mark approvals, established reimbursement frameworks, and high hypertension prevalence across the continent.
| Region | Market Share (%) |
|---|---|
| North America | 0.33% |
| Europe | 0.34% |
| Asia-Pacific | 0.24% |
| South America | 0.05% |
| Middle East & Africa | 0.04% |
Europe's leadership reflects a decade of clinical experience with renal denervation preceding U.S. FDA approval in November 2023. Our analysis suggests North America will close this gap rapidly, driven by the two FDA approvals and a large resistant-hypertension population, potentially overtaking Europe by 2028. Asia-Pacific represents the fastest-growing region, with improving healthcare access and expanding clinical research in China, Japan, and India fueling adoption.
The primary growth driver is the rising global prevalence of hypertension, affecting 1.28 billion adults, combined with expanding clinical evidence supporting renal denervation's efficacy in resistant hypertension and related cardiovascular conditions.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising hypertension prevalence | Driver | High | 1.28 billion adults affected; creates large addressable population |
| Regulatory approvals (FDA 2023) | Driver | High | Medtronic and ReCor approvals unlock U.S. market access |
| Technological advancements | Driver | Medium | Improved catheter designs enhance safety and procedural reproducibility |
| Expanding clinical applications | Driver | Medium | Heart failure and CKD indications broaden market potential |
| Competition from existing therapies | Restraint | Medium | Pharmacological management remains first-line; limits referral volume |
| Procedural complications risk | Restraint | Medium | Vascular damage concerns constrain adoption among risk-averse clinicians |
Our analysis suggests the balance of drivers significantly outweighs restraints, but the critical bottleneck is not demand—it is health-system capacity to identify, screen, and refer appropriate candidates. The hypertension population is large, but the commercially actionable segment is concentrated in patients whose medication optimization has been documented and whose anatomy supports catheter-based intervention. Vendors that invest in referral pathway development and operator training will capture disproportionate share as procedural volumes scale.
Medtronic leads the renal denervation devices market with over 25% share in 2025, followed by ReCor Medical (Otsuka), Boston Scientific, Terumo, and Ablative Solutions, which collectively hold approximately 65% of the market.
| Company | Technology Platform | Key Differentiator | Market Position |
|---|---|---|---|
| Medtronic | Radiofrequency (Symplicity Spyral) | First FDA-approved RF system; extensive clinical evidence | Market leader, >25% share |
| ReCor Medical (Otsuka) | Ultrasound (Paradise) | Non-contact ablation; FDA approved Nov 2023 | Strong #2, ultrasound leader |
| Boston Scientific | Radiofrequency | Broad interventional cardiology portfolio | Established player |
| Terumo | Radiofrequency | Strong Japan/Asia distribution network | Regional strength |
| Ablative Solutions | Micro-infusion (Peregrine) | Alcohol-based peri-adventitial delivery | Differentiated mechanism |
Competitive moats are built on clinical evidence depth, procedural reproducibility, and health-system relationships rather than device features alone. Medtronic's first-mover advantage in radiofrequency is reinforced by its extensive trial data and existing catheterization-lab relationships. ReCor's ultrasound platform offers a differentiated safety profile that may appeal to clinicians concerned about vascular damage. Our analysis suggests the micro-infusion approach from Ablative Solutions represents a potentially disruptive mechanism if it demonstrates superior durability in ongoing trials.
Buyers and operators must prioritize clinical evidence depth, procedural reproducibility, and total cost of program ownership when selecting renal denervation platforms. The decision extends beyond device unit price to include operator training, imaging integration, and post-procedure follow-up infrastructure.
Procurement risks include vendor lock-in through proprietary catheter designs, limited compatibility with existing imaging systems, and reimbursement uncertainty in markets where coverage decisions remain pending. Switching costs are significant once a hospital establishes a program around a specific platform, as retraining staff and revalidating protocols impose substantial operational friction.
Regulatory compliance varies by region: CE mark approval has enabled European adoption since the 2010s, while U.S. operators must navigate FDA-mandated training and facility requirements specific to each approved system. Our analysis suggests buyers should evaluate vendors on their commitment to post-market surveillance and clinical evidence generation, as long-term durability data will determine payer coverage and referral volumes.
The balance of evidence favors a program-execution thesis over a device-availability thesis for the renal denervation devices market. The FDA approvals of November 2023 removed the regulatory bottleneck, but procedural volumes remain constrained by referral discipline, multidisciplinary screening, and payer confidence. The strongest counter-argument is that a large resistant-hypertension population and favorable clinical evidence could drive faster-than-expected adoption, particularly if major payers issue positive coverage decisions. This is plausible but our analysis suggests health-system capacity, not patient demand, is the binding constraint through 2028.
Actionable Strategy:
The evidence that would change our conclusion is a major U.S. payer issuing broad positive coverage for renal denervation, or a large-scale trial demonstrating durable blood-pressure reduction beyond three years. Either would compress the adoption timeline significantly. Until then, the market rewards platforms and providers that reduce variability in treatment planning and procedure delivery.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 29.6% from 2020-2034 |
| Segmentation |
|
The global renal denervation devices market is estimated at USD 709 million in 2026 and is projected to reach USD 3.62 billion by 2032, growing at a 29.6% CAGR driven by regulatory approvals and expanding clinical evidence.
Ultrasound-based renal denervation is the fastest-growing technology segment, driven by non-contact ablation precision, reduced vascular damage, and favorable clinical trial outcomes in resistant hypertension patients.
Europe leads with approximately 34% share, attributed to early CE mark approvals and established reimbursement frameworks, though North America is expected to close the gap following 2023 FDA approvals.
Medtronic leads with over 25% market share, followed by ReCor Medical (Otsuka), Boston Scientific, Terumo, and Ablative Solutions. The top five vendors collectively hold approximately 65% of the global market.
Growth is driven by rising hypertension prevalence affecting 1.28 billion adults, FDA approvals of Medtronic and ReCor systems in 2023, technological advancements in catheter ablation, and expanding clinical applications beyond hypertension.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis employs a 70/30 primary-to-secondary research split, drawing on 42 in-depth interviews conducted across the renal denervation value chain. Stakeholders interviewed include interventional cardiology directors at academic medical centers, catheter manufacturing specialists, contract sterilization and packaging providers, and global medical-device distributors. Decision-maker participants span VP-level procurement leads, heads of interventional R&D, clinical affairs directors, and commercial operations executives responsible for hospital-contract negotiations.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Interventional Cardiology Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Clinical Affairs & R&D Heads | 25% |
| Commercial Operations Executives | 10% |
| Company Type | Representation (%) |
|---|---|
| Catheter Manufacturers | 40% |
| Interventional Cardiology Centers | 30% |
| Medical Device Distributors | 20% |
| Sterilization & Packaging Providers | 10% |
We triangulate primary findings against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat) to validate cross-border medical-device flows. Corporate annual filings (10-K, SEC filings, investor presentations) from Medtronic, Boston Scientific, and Terumo provide capacity and revenue benchmarks. Patent databases (USPTO, EPO) inform technology-innovation tracking, while recognized technical standards from the FDA and European Society of Cardiology anchor regulatory and clinical-efficacy validation.
We simultaneously run top-down macroeconomic allocation (hypertension prevalence, healthcare expenditure, procedural reimbursement) and bottom-up manufacturer-capacity modeling (catheter production volumes, average selling prices, end-user consumption). Divergences between top-down prevalence-based sizing and bottom-up capacity sizing are reconciled through regression analysis and demand-elasticity adjustment to produce the final market estimate.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection through 2032 | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |