 Canada Corporate Wellness Market
 Size & Forecast 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 204

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Canada Corporate Wellness Market
Amit Mardhekar
Research Analyst

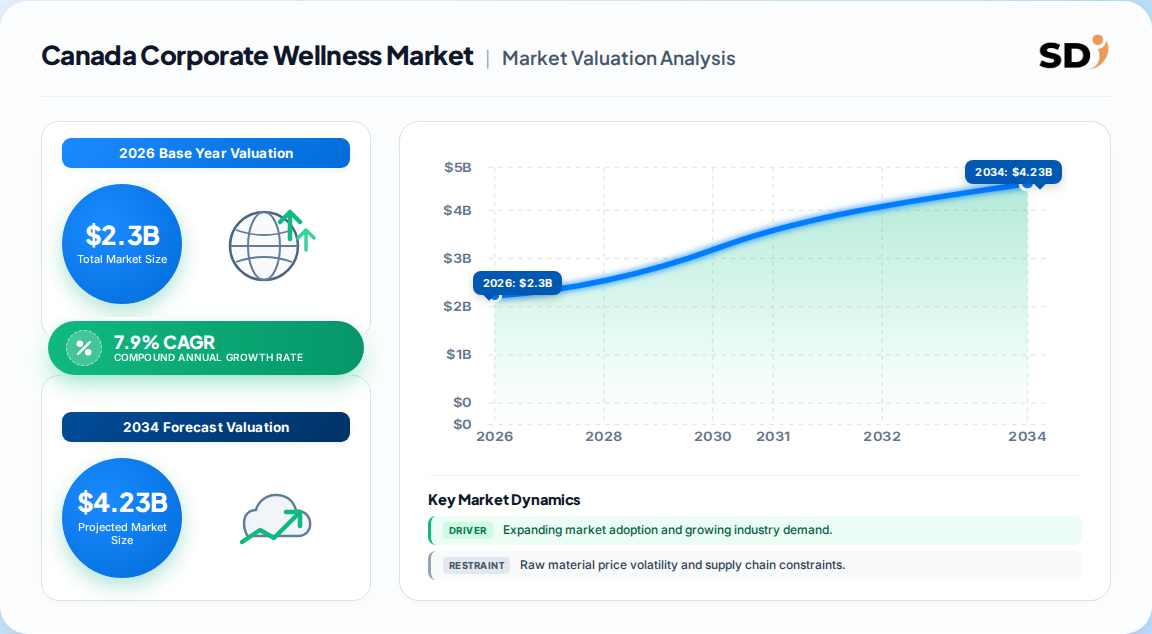
| Year | Market Size |
|---|---|
| 2026 | 2.300 B |
| 2027 | 2.480 B |
| 2028 | 2.680 B |
| 2029 | 2.890 B |
| 2030 | 3.120 B |
| 2031 | 3.360 B |
| 2032 | 3.630 B |

The Canada corporate wellness market covers employer-funded programs and services that improve employees' physical and mental health — health risk assessments, fitness and nutrition programs, smoking cessation, screenings, stress and mental-health support — delivered onsite, offsite or virtually, and procured directly or through insurers and benefits consultants.
This analysis covers employer-sponsored wellness services purchased by private, public and non-profit organizations in Canada, segmented by service, category, delivery model and end use. It includes services delivered by specialist vendors, insurers and in-house teams, and considers both direct-purchase and benefits-embedded procurement.
This analysis does not cover the broader occupational health and safety compliance market, clinical primary care, pharmaceutical or GLP-1 prescribing economics, group insurance premium pricing itself, or consumer fitness memberships purchased without employer subsidy.
The Canada corporate wellness market was valued at approximately 2.3 Billion in 2026, with published estimates diverging meaningfully on both size and growth rate depending on definition and vintage.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 2.4 Billion | 2022 | 2023–2030 | 4.42% | Employer-sponsored wellness services, Canada | One published estimate |
| 2.3 Billion | 2026 | 2016–2031 | 7.9% (historical 5-yr) | Corporate wellness service providers, NAICS S004CA | A competing analysis (industry database) |
| 7.9% implied growth | 2026 | to 2032 | 7.9% | Derived from stated 2026 base and historical CAGR | Our synthesis |
Which figure is most defensible? Our analysis suggests the 2026 estimate of 2.3 Billion with a high-single-digit growth rate is the better working number. The 4.42% figure dates from 2022 and predates the full normalization of hybrid work and the post-pandemic mental-health procurement surge; the 7.9% historical CAGR is measured through 2026 and therefore captures that structural step-up. The divergence implies the earlier forecast understates current momentum by roughly three percentage points annually — a gap worth several hundred million dollars by 2030, and a key reason buyers should not anchor budgets on legacy forecasts.
Canada's corporate wellness market segments along four non-geographic axes — service, category, delivery model and end use — with health risk assessment and onsite delivery dominating current spend.
| Parent segment | Children |
|---|---|
| By Service | Health Risk Assessment, Fitness, Smoking Cessation, Health Screening, Nutrition & Weight Management, Stress Management, Others |
| By Category | Organizations/Employers, Fitness & Nutrition Consultants, Psychological Therapists |
| By Delivery Model | Onsite, Offsite / Virtual, Hybrid |
| By End Use | Large-Scale Organizations, Small & Medium Organizations, Public Sector |
Service-level structure matters most for procurement: HRA and screenings are episodic, low-margin and highly commoditized, while stress management and psychological therapy are recurring, higher-margin and stickier. Our analysis suggests vendors that lead with HRA to win the account, then cross-sell mental-health and coaching modules, capture materially better lifetime value than single-service providers.
Ontario leads the Canada corporate wellness market, generating roughly 39% of national wellness revenue, followed by Quebec at about 23% and British Columbia at about 14% — a concentration that mirrors provincial head-office and public-sector density.
| Province | Estimated share |
|---|---|
| Ontario | 39% |
| Quebec | 23% |
| British Columbia | 14% |
| Alberta | 12% |
| Prairies (SK & MB) | 7% |
| Atlantic Canada | 5% |
Two implications follow. First, a vendor without credible Ontario and Quebec coverage cannot reach scale, and Quebec specifically demands bilingual clinical staff — a real barrier to entry. Second, Alberta's energy-linked corporate profits create boom-bust procurement, which argues for contract structures with minimum-spend floors rather than pure per-participant pricing.
Mental-health demand, hybrid-work digitization and demonstrated ROI are the dominant growth drivers, while low sustained engagement and data-privacy compliance are the binding restraints on the Canada corporate wellness market.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Workplace mental-health burden (~20% of employees report problems) | Driver | High | Expands stress-management and therapy procurement |
| Demonstrated ROI up to 2.62 CAD per dollar spent | Driver | High | Justifies budget retention with CFOs |
| Hybrid and remote work adoption | Driver | High | Drives virtual and telehealth wellness uptake |
| Employer healthcare cost escalation | Driver | Medium-High | Pushes preventive screening investment |
| Low sustained employee engagement (often <30% by Q2) | Restraint | High | Erodes measured ROI and renewal confidence |
| Data-privacy and health-information compliance | Restraint | Medium-High | Raises cost and slows employer sign-off |
| SME budget constraints | Restraint | Medium | Caps addressable spend in smaller employers |
| Shortage of qualified wellness professionals | Restraint | Medium | Constrains service capacity and raises delivery cost |
The balance favors growth, but conditionally. Mental-health need is structural and unlikely to reverse; engagement and privacy are execution problems that determine whether that need converts into renewals. Notably, 42% of Canadian business leaders report interest in mental-health initiatives but no action, citing time, resources or knowledge gaps — a demand pool that exists but is not yet transacting. Our analysis suggests this latent segment is the single largest near-term upside, and it will be unlocked by simplified, pre-packaged SME offerings rather than bespoke enterprise programs.
The Canada corporate wellness market is moderately concentrated, with integrated health and benefits platforms competing against specialist point solutions and group-benefit insurers.
| Vendor / archetype | Positioning | Differentiation |
|---|---|---|
| LifeWorks (Telus Health) | Integrated EAP, mental health and wellness platform | Scale, national footprint, clinical credibility |
| Group-benefit insurers (Manulife, Sun Life, Canada Life) | Wellness bundled into group benefits | Distribution through existing plan sponsors |
| Specialist EAP and counselling providers | Mental-health-first services | Depth of clinical network |
| Digital wellness platforms | App-based fitness, challenges, coaching | Engagement design and analytics |
| Fitness & nutrition consultancies | Onsite programming and coaching | Local presence and customization |
Competitive moats in Canada rest less on technology than on three assets: clinical network density (especially bilingual clinicians), insurer or consultant distribution relationships, and provable ROI reporting in CAD. The emergence of integrated platforms that combine EAP, digital coaching and benefits data threatens standalone point solutions, whose differentiation is easily replicated. Our analysis suggests mid-sized vendors should either specialize deeply in a defensible clinical niche — menopause support, sleep health, chronic-condition coaching — or secure channel partnerships with insurers rather than compete head-on on breadth.
Selection should hinge on measured outcomes, not catalogue breadth. Buyers should demand baseline health metrics, defined engagement targets after 90 and 180 days, and contractual reporting in CAD-adjusted ROI terms; wellness contracts without these clauses routinely renew on inertia and hide underperformance.
Procurement risk concentrates in three areas: engagement decay, data handling, and clinician scarcity. Engagement typically falls below 30% by the second quarter, so contracts should include participation floors and remediation obligations rather than per-seat fees alone. Because wellness platforms touch protected health information, buyers must confirm segregation from HR personnel files and compliance with Canadian privacy law; provincial health-information statutes add complexity in Ontario, Quebec and Alberta. Finally, reliance on a single clinical network creates continuity risk — bilingual capacity in Quebec is the most acute bottleneck.
Switching costs are moderate and rising. Multi-year platform integrations, benefits-carrier bundling and accumulated participant data make mid-contract migration costly, which strengthens incumbent vendors but also raises the bar for initial vendor selection. Operators should expect buyers to increasingly request pilot-then-scale structures, with the pilot judged on hard biometric and absenteeism data.
The balance of evidence favors a high-single-digit growth outlook for the Canada corporate wellness market, but with a decisive shift in where value accrues. Mental health, hybrid delivery and measured outcomes are the growth vectors; commodity screening and generic EAP are commoditizing. The strongest counter-argument is that employer budgets are cyclical and Alberta-linked profit volatility could drag aggregate spend — but mental-health demand is largely non-discretionary, so we view this as a mix risk rather than a growth risk.
Actionable strategy:
What would change our conclusion: sustained engagement below 25% across major accounts, or provincial privacy rules restricting wellness data use, would materially compress the 7.9% trajectory. While this overview establishes the strategic frame, precise sub-segment forecasting and vendor-level share analysis require the full report.
| Region | Market Share (%) |
|---|---|
| Ontario | 0.39% |
| Quebec | 0.23% |
| British Columbia | 0.14% |
| Alberta | 0.12% |
| Prairies (SK & MB) | 0.07% |
| Atlantic Canada | 0.05% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
The Canada corporate wellness market is approximately 2.3 Billion in 2026, based on industry-database estimates. Older published figures near 2.4 Billion for 2022 used narrower definitions and lower growth assumptions, so current spend is likely higher than legacy forecasts suggest.
The most defensible growth rate is 7.9% annually, derived from historical provider revenue through 2026. Broader North American models cite 4.2–4.4%, but those predate the hybrid-work and mental-health procurement step-up now visible in Canadian data.
Health risk assessment leads service revenue at roughly 20–21% share, driven by employer emphasis on preventive screening. Stress management and digital mental-health services are the fastest-growing segments, reflecting high workplace mental-health prevalence.
Key players include LifeWorks (Telus Health), group-benefit insurers such as Manulife, Sun Life and Canada Life, specialist EAP and counselling providers, digital wellness platforms, and regional fitness and nutrition consultancies serving onsite programs.
Ontario generates roughly 39% of national wellness revenue and offers the largest opportunity, followed by Quebec at about 23%. Quebec requires bilingual clinical capacity, while British Columbia and Alberta offer strong hybrid-work and energy-sector demand respectively.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split. We conduct in-depth interviews with stakeholders across the value chain, including corporate wellness platform operators, group-benefit insurers, clinical network and EAP providers, benefits consultants and brokers, and in-house HR and total-rewards teams. Interviewees include VP-level benefits and total rewards leaders, Heads of Wellness and Occupational Health, benefits consultants and commercial operations leads at wellness providers. Interviews probe contract structures, engagement metrics, renewal drivers, procurement timelines and pricing benchmarks.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Benefits & Total Rewards | 38% |
| Heads of Wellness & Occupational Health | 32% |
| Benefits Consultants & Brokers | 18% |
| Provider Commercial Operations Leads | 12% |
| Company Type | Representation (%) |
|---|---|
| Wellness Platform & EAP Operators | 40% |
| Group-Benefit Insurers | 30% |
| Clinical & Counselling Networks | 18% |
| Benefits Consultants & Brokers | 12% |
We triangulate against official statistics and public filings: Statistics Canada employment and workplace health data, provincial privacy and health-information regulators, corporate annual reports and securities filings, benefits-industry association publications, and peer-reviewed occupational-health literature. No competitor market-research publications are used as validation sources.
We model demand simultaneously top-down (employer base by province and size band, benefits spend allocation) and bottom-up (provider revenue, per-employee pricing, participant counts and service mix). Divergences between the two are reconciled against interview evidence and public benchmarks.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in CAD/USD for base year | Bottom-up provider revenue and per-employee triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis and hybrid-work elasticity | High |
| Regional Distribution | Provincial share breakdown | Employer-density analysis and provider footprint mapping | High |
| Competitive Landscape | Leading market players | Annual reports, contract wins and service-mix mapping | High |