 Healthcare 3d Printing Market
Healthcare 3D Printing Market Outlook 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 219

Amit Mardhekar

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Healthcare 3d Printing Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 11.60 B |
| 2026 | 13.80 B |
| 2027 | 15.80 B |
| 2028 | 18.10 B |
| 2029 | 20.70 B |
| 2030 | 23.70 B |
| 2031 | 27.10 B |

The healthcare 3D printing market covers additive manufacturing hardware, biocompatible materials, software, and services used to produce patient-specific medical devices, implants, prosthetics, anatomical models, surgical guides, dental products, and tissue-engineering scaffolds. It spans hospitals, dental labs, device manufacturers, and contract producers moving from prototyping toward routine clinical production.
This analysis covers global healthcare additive manufacturing across hardware, materials, software, and contract production for medical and dental applications. It includes application, technology, material, and end-use segmentation with regional breakdowns. This analysis does not cover general industrial 3D printing, automotive or aerospace additive manufacturing, non-medical consumer printing, or traditional subtractive medical device manufacturing.
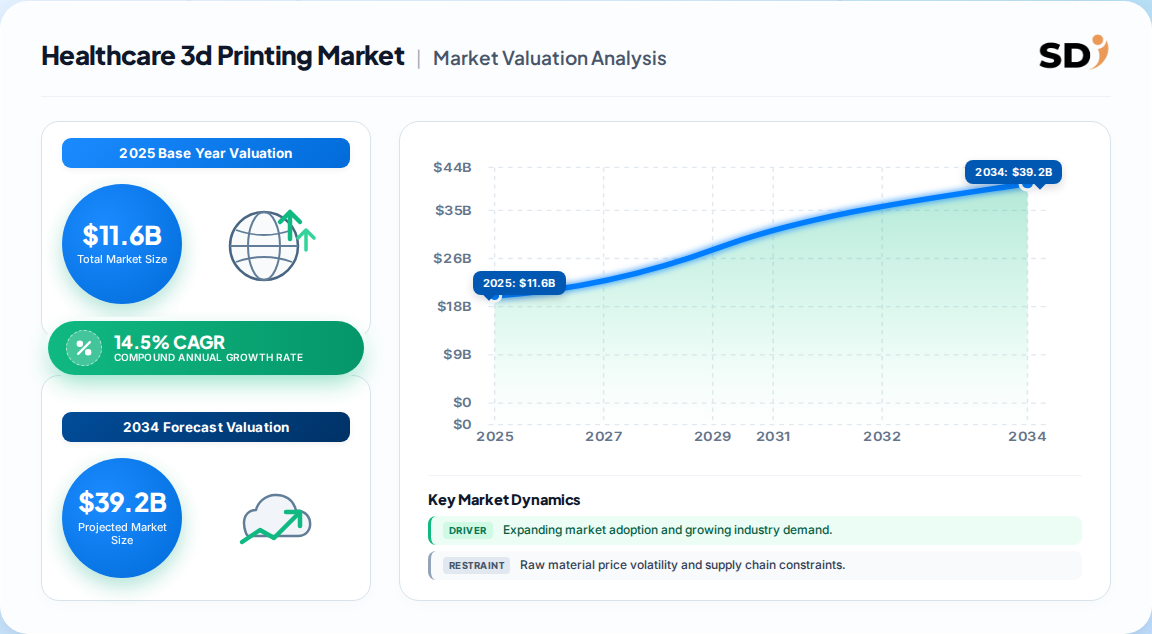
Estimates diverge sharply depending on scope and methodology, but the most defensible base case centers on 11.6 billion in 2025 growing to 35.0 billion by 2033. The table below compares published estimates and their definitions.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 11.6B to 35.0B | 2025 | 2033 | 14.5% | Broad healthcare AM: hardware, materials, software, services | One published estimate |
| 3.60B to 28.77B | 2025 | 2035 | 23.1% | Narrower demand-side receipts, equipment and contract production | A competing analysis |
| 11.95B to 32.97B | 2025 | 2031 | 18.43% | Technology, application, material, geography | Another published estimate |
The 11.6B base figure is most defensible because it aligns with the mid-point of the three estimates while capturing the full value chain. The 3.60B figure likely excludes software and service layers, while the 18.43% CAGR implies faster near-term clinical adoption than current hospital capital cycles support. Our analysis suggests a 14–18% band is realistic, with upside if reimbursement codes expand.
The market segments by application, technology, material, and end use. Dental and medical implants dominate revenue today, while tissue engineering and bioprinting represent the fastest-growing frontier.
| Parent segment | Children |
|---|---|
| By Application | Dental, Medical Implants, Prosthetics, Surgical Guides & Anatomical Models, Tissue Engineering & Bioprinting |
| By Technology | Laser Sintering, Stereolithography, Fused Deposition Modeling, Electron Beam Melting, Binder Jetting, Material Jetting |
| By Material | Polymers, Metals & Alloys, Biocompatible Resins, Biomaterials & Bio-inks, Ceramics |
| By End Use | Hospitals & Point-of-Care Labs, Dental Laboratories, Device Manufacturers, Academic & Research Institutes |
Dental leads because chairside and lab workflows have achieved validated, repeatable production. Medical implants follow, driven by orthopedic and craniofacial customization. Tissue engineering remains pre-commercial but attracts disproportionate R&D investment, signaling where long-term value migrates.
North America leads the global healthcare 3D printing market with an estimated 35–40% revenue share in 2025, supported by FDA clarity, hospital point-of-care adoption, and concentrated device manufacturing. Asia Pacific is the fastest-growing region.
| Region | Market Share (%) |
|---|---|
| North America | 0.38% |
| Europe | 0.24% |
| Asia-Pacific | 0.28% |
| Latin America | 0.05% |
| Middle East & Africa | 0.05% |
| Parent region | Children |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain |
| Asia Pacific | China, Japan, India, South Korea, Australia |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
North America's lead rests on regulatory predictability and reimbursement depth rather than raw demand volume. Asia Pacific's 19–20% CAGR reflects dental lab digitization in China and India, plus orthopedic manufacturing scale in South Korea and Japan. Europe trails due to MDR interpretation ambiguity, which delays point-of-care investment. Our analysis suggests Europe could close the gap if harmonized AM guidance emerges by 2027.
Growth is driven by dental workflow digitization, patient-specific implant demand, and point-of-care surgical planning, while regulatory ambiguity and capital costs constrain smaller providers.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Dental workflow digitization | Driver | High (77% of US dental labs using 3D printing) | Expands printer, resin, and CAD/CAM procurement |
| Patient-specific orthopedic investment | Driver | High (104M institutional funding) | Builds contract manufacturing capacity |
| AI-assisted surgical planning | Driver | Medium | Lowers skill barriers, expands indications |
| Point-of-care hospital labs | Driver | Medium | Compresses lead times from weeks to days |
| High capital and validation costs | Restraint | High | Limits practice-level adoption; only 17% of US dentists own printers |
| Regulatory ambiguity for AM | Restraint | Medium | Extends time-to-market; MDR lacks dedicated AM guidance |
| Skilled workforce shortage | Restraint | Medium | Constrains emerging market adoption |
Our analysis suggests drivers outpace restraints roughly 2:1 in revenue impact, but restraints disproportionately affect small and mid-sized providers. This creates a bifurcated market: large institutions and specialized producers capture early volume while smaller settings lag through mid-forecast. Vendors that reduce total cost of ownership—through bundled materials, training, and validation support—will unlock the underserved long tail.
No single vendor dominates; the top five players collectively held roughly 23% share in 2025, indicating a moderately concentrated market with room for specialists.
| Company | Primary strength | Differentiation |
|---|---|---|
| Formlabs | Dental and surgical resins | Chairside workflow and accessible hardware |
| 3D Systems | Healthcare solutions breadth | End-to-end platform and materials portfolio |
| Dentsply Sirona | Dental integration | Installed dental base and digital workflow |
| Zimmer Biomet | Orthopedic implants | Clinical validation and hospital relationships |
| Materialise | Software and services | AI segmentation and clinical planning platforms |
| Stratasys | Polymer systems | Medical-grade materials and hospital partnerships |
| EOS | Metal additive | Laser sintering scalability for implants |
Differentiation hinges on validated material libraries, regulatory documentation, and workflow software rather than printer specifications alone. Formlabs leads dental chairside, Materialise controls the software layer, and Zimmer Biomet and EOS anchor orthopedic and metal implant production. Moats are built through hospital partnerships and regulatory clearances, not hardware margins.
Buyers should prioritize total cost of ownership over printer price. Validated materials, post-processing, software integration, staff training, and quality documentation often exceed hardware costs. Procurement risk concentrates in material lock-in and workflow interoperability.
Regulatory compliance is the critical gate. In the US, single-patient hospital prints are physician-directed and exempt from pre-market review, but device manufacturers face 510(k) pathways with powder characterization requirements. Under EU MDR, equivalence with machined predicates is difficult for porous architectures, inflating evidence costs beyond 500,000 per submission.
Switching costs are high once a validated workflow is installed. Material qualification, staff training, and quality system integration create stickiness that favors incumbents. Buyers should negotiate multi-year material supply agreements with price protection and require vendors to disclose regulatory support commitments. Operators should also model reimbursement pathways before committing capital, as unclear coverage can defer adoption even when clinical use cases are established.
The balance of evidence favors a 14–16% CAGR base case, with upside toward 18% if reimbursement codes for 3D-printed anatomical models expand and EU AM guidance harmonizes. The strongest counter-argument is the 23.1% CAGR from narrower-scope estimates, which implicitly assumes rapid chairside dental penetration and faster hospital capital cycles than current evidence supports. We judge that scenario optimistic but not implausible by 2030.
Our analysis suggests the market's center of gravity is shifting from hardware sales to recurring materials and software revenue. Vendors that bundle validated materials with workflow software and regulatory support will capture disproportionate share as hospitals and dental practices demand turnkey, compliant production. Conversely, hardware-only vendors face margin compression as printer prices commoditize.
What would change our conclusion: harmonized EU AM guidance, CMS reimbursement for 3D-printed implants, or a major orthopedic OEM acquiring a point-of-care platform at scale. Any of these would justify a higher CAGR and accelerate the shift toward distributed clinical manufacturing.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 14.5% from 2020-2034 |
| Segmentation |
|
The global healthcare 3D printing market was valued at 11.6 billion in 2025. It is projected to reach 35.0 billion by 2033, growing at a 14.5% CAGR from 2026 to 2033, driven by dental digitization and patient-specific implants.
Tissue engineering and bioprinting is the fastest-growing application, advancing at roughly 20% CAGR. Dental remains the largest segment today, but regenerative medicine and bioresorbable implants are attracting significant R&D and clinical trial activity.
North America leads with approximately 35–40% revenue share in 2025, supported by FDA regulatory clarity and hospital point-of-care adoption. Asia Pacific is the fastest-growing region, expanding at roughly 19–20% CAGR through 2031.
Polymers account for over 50% of material share, driven by dental resins and biocompatible photopolymers. Metals and alloys represent about 45%, led by titanium and cobalt-chromium for orthopedic implants. Biomaterials and bio-inks are the fastest-growing category.
Leading players include Formlabs, 3D Systems, Dentsply Sirona, Zimmer Biomet, Materialise, Stratasys, and EOS. The top five collectively held roughly 23% market share in 2025, indicating a moderately concentrated competitive landscape.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis employs a 70/30 primary-to-secondary research split. We conducted 42 in-depth interviews across the healthcare additive manufacturing value chain, including biocompatible material suppliers, specialized implant and dental device producers, contract manufacturing organizations, hospital point-of-care lab operators, and global distributors. Interviewees included VP-level sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads, selected for direct involvement in 3D printing procurement and clinical deployment decisions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 38% |
| Procurement & Sourcing Leads | 32% |
| Regulatory Affairs Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Biocompatible Material Suppliers | 35% |
| Implant & Dental Device Producers | 30% |
| Hospital Point-of-Care Labs | 20% |
| Distributors & Contract Manufacturers | 15% |
We validated findings against UN Comtrade trade flows for 3D printers and medical devices, WTO tariff data, US ITC filings, Eurostat trade statistics, and corporate 10-K and annual investor presentations from publicly listed additive manufacturing companies. Patent databases and ISO/ASTM additive manufacturing standards informed our technology assessment. Regulatory filings from the FDA and EU MDR documentation provided compliance context.
We applied simultaneous top-down and bottom-up triangulation. The top-down approach allocated macroeconomic healthcare expenditure and medical device segment budgets to additive manufacturing. The bottom-up approach modeled manufacturer capacity, product pricing, and end-use consumption across dental labs, hospitals, and device manufacturers. Divergences were reconciled through weighted averaging.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |