 Hospital Microbiology Testing Market
 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 204

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Hospital Microbiology Testing Market
Amit Mardhekar
Research Analyst

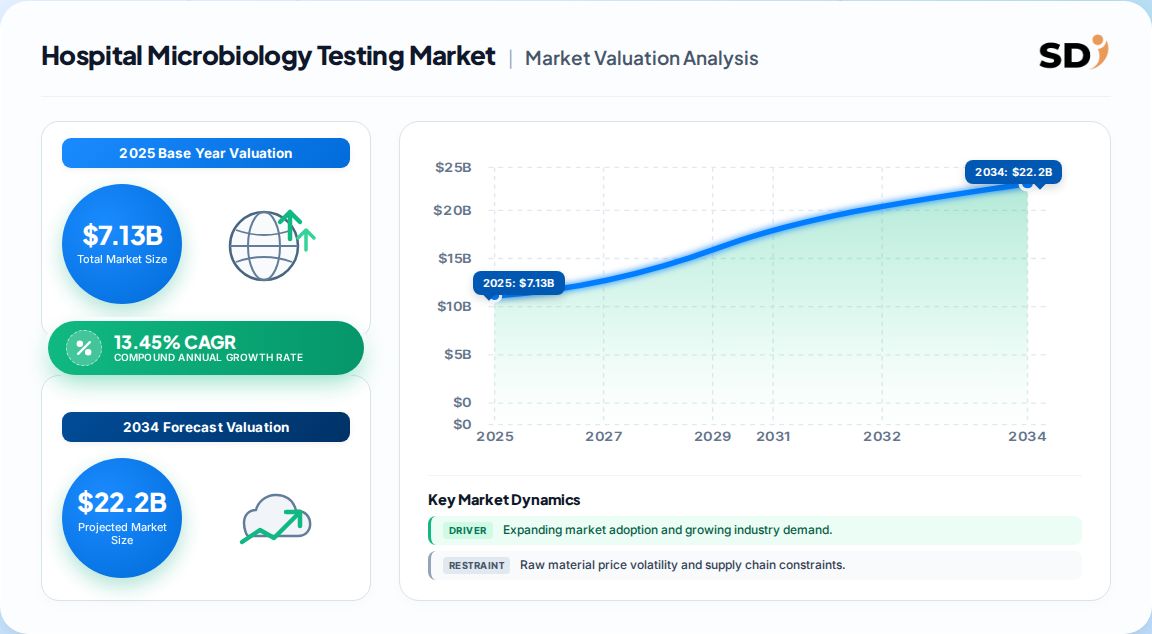
| Year | Market Size |
|---|---|
| 2025 | 7.130 B |
| 2026 | 8.090 B |
| 2027 | 9.180 B |
| 2028 | 10.41 B |
| 2029 | 11.81 B |
| 2030 | 13.40 B |
| 2031 | 15.20 B |

The hospital microbiology testing market covers laboratory tests that detect, identify, and monitor bacteria, viruses, fungi, and parasites in patient samples within hospital settings. It supports infection diagnosis, antimicrobial susceptibility testing, hospital-acquired infection surveillance, and antimicrobial stewardship, and it is delivered through culture, molecular, immunochemical, and automated identification platforms.
This analysis covers hospital-based and hospital-affiliated microbiology testing across clinical diagnostics for respiratory, bloodstream, gastrointestinal, urinary tract, sexually transmitted, and parasitic infections, spanning reagents, instruments, consumables, and laboratory software. This analysis does not cover industrial, food and beverage, environmental, cosmetic, or veterinary microbiology testing, nor standalone pathology or clinical chemistry markets.
Published estimates diverge by a wide margin. The table below normalizes each benchmark to its base year and definitional scope so buyers can see why headline figures are not directly comparable.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 7.13 billion | 2025 | 2035 | 13.45% | Hospital microbiology testing, global | One published hospital-specific estimate |
| USD 4.9 billion | 2022 | 2032 | 9.3% | Total microbiology testing, all end users | One published broad-market estimate |
| USD 6.7 billion | 2026 | 2031 | 9.09% | Microbiology testing, hospital labs ~52% | One published broad-market estimate |
| USD 7.9 billion | 2025 | 2033 | 7.1% | Industrial microbiology and bacterial culture | One published industrial estimate |
The hospital-specific figure is the most defensible anchor for this report because it isolates the hospital channel and the 2026-2035 horizon. Broad microbiology estimates include industrial and food testing, which dilutes growth. Our analysis suggests the true hospital CAGR lands between 9% and 13%, with the upper band achievable only if automation adoption accelerates in Asia-Pacific secondary hospitals.
The market splits along product, test type, application, and end user. Reagents and consumables dominate revenue today, but instruments, software, and molecular workflows carry the growth premium.
| Parent segment | Children |
|---|---|
| By Product | Instruments, Reagents, Consumables, Software |
| By Test Type | Bacterial testing, Viral testing, Fungal testing, Parasitic testing |
| By Application | Respiratory infections, Bloodstream infections, Gastrointestinal infections, Urinary tract infections, Sexually transmitted infections, Others |
| By End User | Hospitals, Diagnostic laboratories, Ambulatory surgical centers, Academic and research institutes |
Bacterial testing remains the largest revenue block on the back of urinary tract, bloodstream, and surgical-site infection volumes. Molecular and multiplex platforms are the fastest-growing technology tier, because they collapse multi-day culture pathways into same-shift results and directly support antimicrobial stewardship programs.
North America leads with roughly 42% of global hospital microbiology revenue, supported by advanced laboratory infrastructure, high molecular adoption, and stringent infection-control mandates. Asia-Pacific is the fastest-growing region, expanding at a double-digit pace as China and India modernize secondary and tertiary hospital laboratories.
| Region | Market Share (%) |
|---|---|
| North America | 0.42% |
| Europe | 0.26% |
| Asia-Pacific | 0.24% |
| Latin America | 0.05% |
| Middle East & Africa | 0.03% |
| Region | Share of global revenue |
|---|---|
| North America | 42% |
| Europe | 26% |
| Asia-Pacific | 24% |
| Latin America | 5% |
| Middle East & Africa | 3% |
Antimicrobial resistance and hospital-acquired infections are the strongest demand catalysts, while capital cost and laboratory staffing shortages cap the pace of adoption.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Antimicrobial resistance and HAIs | Driver | High | Rapid susceptibility testing guides targeted therapy and stewardship |
| Diagnostic automation and AI | Driver | High | Robotics and AI plate reading cut turnaround ~40% |
| Rapid and point-of-care testing | Driver | Medium-high | Sepsis and respiratory triage demand same-shift results |
| Healthcare funding expansion | Driver | Medium | Capital budgets for laboratory modernization in APAC |
| High instrument and infrastructure cost | Restraint | High | Limits adoption in resource-constrained hospitals |
| Skilled laboratory staff shortage | Restraint | High | Vacancy rates near 25% raise training and operations risk |
| Evolving regulatory frameworks | Restraint | Medium | Compliance cost and approval timelines slow launches |
The balance favors growth. Our analysis suggests the binding constraint is not demand but laboratory capacity to absorb new platforms. Vendors that reduce the training burden and offer managed service models will convert more of the latent demand into revenue.
A concentrated group of diagnostic majors controls the installed base, differentiated by menu breadth, automation depth, and connectivity into hospital information systems.
| Vendor | Core strength | Strategic posture |
|---|---|---|
| bioMérieux SA | Automated ID/AST and culture | Broadest hospital microbiology franchise |
| Becton, Dickinson and Company | Blood culture and identification | Installed-base lock-in and informatics |
| F. Hoffmann-La Roche Ltd | Molecular diagnostics | High-throughput PCR and syndromic panels |
| Abbott Laboratories | Rapid and point-of-care testing | Decentralized testing expansion |
| Bruker Corporation | MALDI-TOF identification | Fast, low-cost species-level ID |
| QIAGEN N.V. | Sample preparation and molecular | Menu expansion in hospital labs |
| Bio-Rad Laboratories | Quality control and diagnostics | Recurring consumables strength |
The moat is workflow integration, not instrument hardware. Once a hospital standardizes on a blood-culture or identification platform, switching costs rise sharply because validation, staff training, and interface builds must be repeated. This is why the market remains only moderately concentrated despite active vendor competition.
Procurement should be judged on total cost of ownership, not instrument price. Reagents and consumables typically account for the large majority of lifetime spend, so negotiation leverage lies in multi-year reagent contracts, uptime guarantees, and menu-expansion clauses rather than capital discounts. Validation burden is the hidden switching cost: a platform change requires re-verification against accredited methods and retraining of technologists, which can consume laboratory capacity for months.
Regulatory compliance is non-negotiable. Hospitals must maintain accreditation and demonstrate antimicrobial stewardship reporting, so buyers should prioritize vendors whose platforms generate audit-ready data and integrate with hospital information systems. Staffing is the operational risk: any platform that does not reduce manual steps will fail in a laboratory with double-digit vacancy rates. Operators should weight automation and remote support above incremental analytical sensitivity.
The balance of evidence favors a structural, not cyclical, growth story. Antimicrobial resistance, hospital-acquired infection surveillance, and laboratory staffing shortages are durable forces that make microbiology testing a defensive clinical spending line. The strongest counter-argument is that hospital capital budgets are constrained and that point-of-care decentralization could erode central laboratory volumes; however, decentralized testing typically complements rather than replaces central microbiology for culture and susceptibility work.
Our analysis suggests the revenue pool will shift toward vendors that sell workflow outcomes. Hospitals are not buying analyzers; they are buying turnaround time, staff substitution, and audit-ready data. Vendors that cannot connect to hospital information systems or reduce manual steps will face pricing pressure even as volumes grow. The competitive risk is not a rival instrument but a rival business model built on managed service contracts and cloud analytics.
What would change this conclusion: a sustained deceleration in molecular panel reimbursement, or evidence that point-of-care platforms can deliver susceptibility results at parity with central laboratories. Neither is visible in current data, but the full report tracks both signals quarterly.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 13.45% from 2020-2034 |
| Segmentation |
|
The global hospital microbiology testing market was estimated at USD 7.13 billion in 2025 and is projected to reach USD 25.19 billion by 2035, growing at a 13.45% CAGR. Broader microbiology testing estimates are lower because they exclude the hospital-specific channel premium.
North America leads with roughly 42% of global hospital microbiology revenue, driven by advanced laboratory infrastructure and high molecular diagnostics adoption. Asia-Pacific is the fastest-growing region as China and India modernize hospital laboratories.
Antimicrobial resistance, hospital-acquired infections, and laboratory staffing shortages are the primary drivers. Rapid molecular and multiplex diagnostics shorten turnaround times, while automation helps hospitals offset vacancy rates near 25% in clinical laboratories.
bioMérieux, Becton Dickinson, F. Hoffmann-La Roche, Abbott Laboratories, and Bruker Corporation lead the market. Differentiation rests on installed-base lock-in, menu breadth, automation depth, and connectivity into hospital information systems rather than instrument hardware alone.
Molecular and multiplex platforms deliver pathogen identification and resistance markers within hours instead of days, supporting earlier targeted therapy and antimicrobial stewardship. This clinical advantage is driving faster adoption even where culture-based methods retain the largest revenue share.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis follows a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the hospital microbiology value chain, including reagent and consumable manufacturers, instrument and automation suppliers, molecular diagnostics developers, hospital laboratory networks, and group purchasing organizations. Decision-maker designations interviewed included hospital laboratory directors, infection-control and antimicrobial stewardship leads, procurement and sourcing heads, and vendor commercial operations executives. Interviews focused on procurement criteria, switching costs, automation adoption timelines, and reimbursement dynamics.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Laboratory Directors & Clinical Leads | 35% |
| Procurement & Sourcing Heads | 30% |
| Infection Control & Stewardship Leads | 20% |
| Vendor Commercial Operations | 15% |
| Company Type | Representation (%) |
|---|---|
| Reagent & Consumable Manufacturers | 40% |
| Instrument & Automation Suppliers | 25% |
| Molecular Diagnostics Developers | 20% |
| Hospital Laboratory Networks | 15% |
We validated findings against official multilateral trade and standards databases, including UN Comtrade, WTO trade statistics, US ITC data, and Eurostat, alongside corporate annual filings (10-K, SEC filings, investor presentations) and patent databases. We also referenced recognized technical standards and clinical guidance from ISO, CLSI, and the WHO's antimicrobial resistance surveillance frameworks. No third-party market research publisher data was used as a primary validation source.
We applied simultaneous top-down and bottom-up triangulation. The top-down model allocated macroeconomic healthcare spending and hospital diagnostic budgets across regions and segments. The bottom-up model built test-volume estimates from hospital bed capacity, testing rates, reagent pricing, and instrument installed base, then reconciled both against public trade flows and corporate revenue disclosures.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |