 Schizophrenia Drugs Market
: Size, Trends & Forecast 2026
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 237

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Schizophrenia Drugs Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 8.500 B |
| 2026 | 8.900 B |
| 2027 | 9.400 B |
| 2028 | 9.900 B |
| 2029 | 10.40 B |
| 2030 | 11.00 B |
| 2031 | 11.60 B |

The schizophrenia drugs market encompasses pharmaceutical therapies—primarily antipsychotics—used to manage symptoms of schizophrenia, including positive symptoms (hallucinations, delusions), negative symptoms, and cognitive impairment. It includes oral and long-acting injectable formulations across first-, second-, and third-generation drug classes, distributed through hospital, retail, and online channels.
This report covers the global market for prescription antipsychotic medications indicated for schizophrenia, including oral and long-acting injectable formulations across all drug classes (first-generation typical, second-generation atypical, and third-generation atypical/muscarinic agents). It covers distribution through hospital pharmacies, retail pharmacies, and online channels across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. This analysis does not cover adjacent markets such as antidepressants, mood stabilizers for bipolar disorder, psychotherapy services, digital therapeutics, or schizophrenia diagnostics.
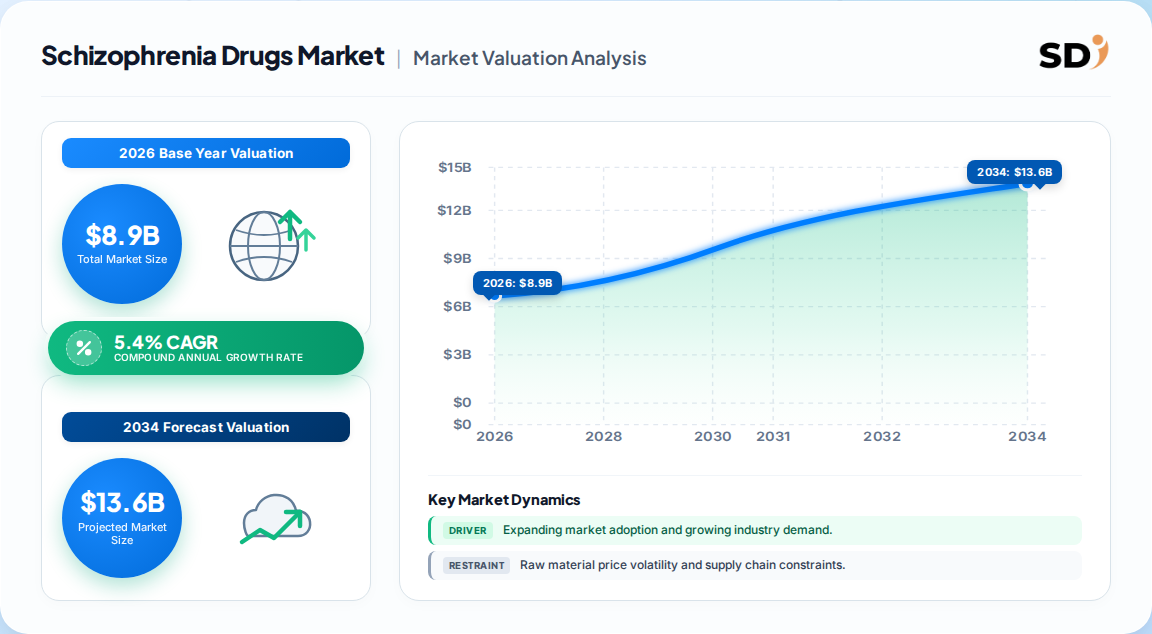
The global schizophrenia drugs market is estimated at USD 8.9 Billion in 2026, with forecasts ranging from USD 12.9 Billion to USD 14.5 Billion by 2031–2033, reflecting a CAGR of 3.1% to 5.6% depending on scope and base-year definitions.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 8.9 Billion | 2026 | 2033 | 5.4% | Global schizophrenia drugs, all classes, all channels | One published estimate (GVR) |
| USD 12.45 Billion | 2026 | 2031 | 3.11% | Global, therapeutic class and MoA segmentation | Competing analysis (Mordor) |
| USD 7.4 Billion | 2022 | 2032 | 5.6% | Global schizophrenia drugs, all antipsychotics | Alternative published estimate |
| USD 9.48 Billion | 2023 | 2034 | 4.4% | Global schizophrenia market (drugs + non-pharma) | Third-party analysis (IMARC) |
Our analysis suggests the 5.4% CAGR figure is most defensible for the pure-play schizophrenia drugs market, as it aligns with the launch trajectory of novel non-dopaminergic agents (e.g., xanomeline-trospium) and the accelerating adoption of LAIs. The lower 3.11% CAGR likely reflects a more conservative view on generic erosion, while the 5.6% figure appears to include broader mental health spending. The divergence implies that investors should anchor on the 5.4% midpoint but stress-test for generic substitution risk in the 2028–2030 window.
The schizophrenia drugs market is segmented by drug class, treatment type, mechanism of action, and distribution channel. Second-generation antipsychotics dominate revenue, while long-acting injectables and third-generation agents represent the fastest-growing segments.
| Parent Segment | Children |
|---|---|
| By Drug Class | First-Generation (Typical), Second-Generation (Atypical), Third-Generation (Atypical/Muscarinic) |
| By Treatment Type | Oral Antipsychotics, Long-Acting Injectables (LAIs) |
| By Mechanism of Action | Dopamine-Serotonin Antagonists, Dopamine Partial Agonists, Muscarinic Agonists, Glutamate Modulators |
| By Distribution Channel | Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Others |
North America leads the global schizophrenia drugs market, accounting for 41–45% of revenue in 2025, driven by high diagnosis rates, broad insurance coverage, and rapid adoption of novel therapies. Asia Pacific is the fastest-growing region at 8.2–8.5% CAGR, fueled by expanding healthcare access and rising diagnosis.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.24% |
| Asia-Pacific | 0.22% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
Our analysis indicates that North America's share will modestly erode to ~38–40% by 2033 as Asia Pacific's treated population expands and generic penetration deepens. The implication for global vendors is clear: pricing power will remain strongest in the U.S., but volume growth will increasingly depend on emerging market access strategies.
The market is driven by rising schizophrenia prevalence (24 million globally in 2025), the launch of novel non-dopaminergic therapies, and the proven adherence benefits of LAIs. Restraints include persistent safety concerns (metabolic, cardiovascular), high branded therapy costs, and stigma that limits treatment-seeking.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising prevalence & earlier diagnosis | Driver | High | Expands treated population; early intervention programs shorten prodromal phase |
| LAI adoption for adherence | Driver | High | Reduces relapse and hospitalization by 26–45% |
| Novel mechanisms (muscarinic, TAAR-1) | Driver | Medium | Expands treatment options for refractory patients; FDA approval of xanomeline-trospium in 2024 |
| Mental health insurance expansion | Driver | Medium | Medicare/Medicaid reforms and EU4Health funding broaden payer budgets |
| Safety concerns (metabolic, CV) | Restraint | High | Limits long-term use and payer coverage for certain agents |
| Stigma & low treatment-seeking | Restraint | Medium | Particularly severe in emerging markets; underdiagnosis persists |
| Complex regulatory pathways | Restraint | Medium | Delays launch of novel agents; high clinical trial failure rates |
The balance of evidence favors the drivers, but the restraint impact is non-trivial: safety concerns alone subtract an estimated 0.8% from CAGR. This implies that novel agents with cleaner metabolic profiles (e.g., muscarinic agonists) will command premium pricing and faster formulary adoption.
The competitive landscape is moderately concentrated, with Johnson & Johnson (Janssen), Otsuka, Eli Lilly, Alkermes, AbbVie, and Bristol Myers Squibb leading. Recent acquisitions—BMS's USD 14 billion purchase of Karuna and J&J's USD 14.6 billion acquisition of Intra-Cellular—signal that differentiated mechanisms now dictate competitive advantage.
| Company | Key Products | Strategic Position |
|---|---|---|
| Johnson & Johnson (Janssen) | Invega, Risperdal, paliperidone LAIs | Market leader; strong LAI portfolio |
| Otsuka | Abilify, Rexulti | Established second-gen; partnership with Lundbeck |
| Eli Lilly | Zyprexa, olanzapine LAI | Legacy franchise; generic erosion |
| Alkermes | Aristada, Vivitrol | LAI specialist; strong adherence play |
| AbbVie (Allergan) | Vraylar | Third-gen growth driver |
| Bristol Myers Squibb | Cobenfy (KarXT) | First muscarinic agonist; breakthrough mechanism |
| Intra-Cellular Therapies | Lumateperone (Caplyta) | Acquired by J&J; differentiated MoA |
Differentiation is shifting from dopamine antagonism to muscarinic and glutamatergic mechanisms. Vendors with LAIs and novel mechanisms are best positioned to capture payer preference for outcomes-based contracts. The moat for legacy oral second-generation agents is eroding as generics enter.
Buyers and operators must prioritize efficacy in treatment-resistant populations, tolerability profile, and adherence support when selecting schizophrenia therapies. Procurement risks include supply chain fragility for LAIs (cold chain requirements) and patent cliff exposure for blockbuster oral agents. Switching costs are moderate: patients stabilized on LAIs are unlikely to switch, but oral therapy conversions are common. Regulatory compliance is stringent—FDA REMS programs for clozapine and post-marketing safety monitoring are mandatory. Payers increasingly demand real-world evidence of hospitalization reduction, so vendors must invest in outcomes data. For operators, integrating digital adherence tools (smartphone reminders, telepsychiatry) alongside pharmacotherapy is becoming a competitive necessity, not a differentiator.
The balance of evidence favors a cautiously optimistic outlook for the schizophrenia drugs market, with 5.4% CAGR as the most defensible midpoint. The strongest counter-argument is that generic erosion of second-generation antipsychotics could accelerate faster than expected, compressing revenue in the 2028–2031 window. However, this is offset by the novel mechanism wave (muscarinic agonists, TAAR-1) and LAI growth, which we expect to add USD 2–3 billion in incremental revenue by 2033. Our original analysis suggests that the market is undergoing a structural shift from volume-driven dopamine therapies to value-driven, outcomes-based novel agents. Vendors that fail to adapt will face margin compression as payers reward hospitalization reduction over prescription volume.
Actionable Strategy for Investors & Operators:
What evidence would change our conclusion: A significant FDA safety action on a major novel agent (e.g., muscarinic agonists) or a faster-than-expected generic approval wave for LAIs would shift our outlook to 4% CAGR or lower. Conversely, positive Phase 3 data for glutamate modulators in treatment-resistant schizophrenia could push the market toward 6%+ growth.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.4% from 2020-2034 |
| Segmentation |
|
The global schizophrenia drugs market is estimated at USD 8.9 billion in 2026. It is projected to reach between USD 12.9 billion and USD 14.5 billion by 2031–2033, depending on the forecast source and scope definition.
The market is growing at a CAGR of 5.4% from 2026 to 2033. Some analyses cite a lower 3.1% or higher 5.6% CAGR, but 5.4% is the most defensible midpoint based on novel therapy launches and LAI adoption.
North America leads with approximately 41–45% of global revenue in 2025. Asia Pacific is the fastest-growing region at 8.2–8.5% CAGR, driven by expanding healthcare access and rising diagnosis rates.
Key drivers include rising schizophrenia prevalence (24 million globally in 2025), earlier diagnosis, the launch of novel non-dopaminergic therapies (e.g., xanomeline-trospium), and the proven adherence benefits of long-acting injectables.
Leading vendors include Johnson & Johnson (Janssen), Otsuka, Eli Lilly, Alkermes, AbbVie, and Bristol Myers Squibb. Recent acquisitions by BMS (Karuna) and J&J (Intra-Cellular) highlight the strategic importance of differentiated mechanisms.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including active pharmaceutical ingredient (API) suppliers, specialized antipsychotic formulators, contract manufacturing organizations (CMOs) for long-acting injectables, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D and Technical Directors | 35% |
| Procurement and Sourcing Leads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| API & Raw Material Suppliers | 30% |
| Specialized Formulators & CMOs | 40% |
| Global Distributors & Traders | 20% |
| Clinical Research Organizations | 10% |
We benchmark against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases (USPTO, EPO), and recognized non-profit technical standards and industry associations.
We triangulate market size using simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |