 Dental Protein Combined Products Market
 2026 Guide
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 271

Amit Mardhekar

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Dental Protein Combined Products Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 1.000 B |
| 2025 | 1.060 B |
| 2026 | 1.170 B |
| 2027 | 1.290 B |
| 2028 | 1.420 B |
| 2029 | 1.570 B |
| 2030 | 1.730 B |

The dental protein combined products market covers dental materials that combine proteins, growth factors or bioactive agents with implants, bone grafts, cements and guided tissue regeneration membranes to stimulate bone formation, tissue healing and oral regeneration. These products support implant placement, periodontal repair and restoration of damaged oral tissues.
This analysis covers protein-combined dental implants, bone grafts, dental cements and guided tissue regeneration (GTR) membranes, segmented by protein type, application, end user and region, with a 2024 base year and forecast horizon to 2035. This analysis does not cover conventional metal-only implant hardware, orthodontic appliances, general restorative composites without protein or bioactive loading, or standalone dental practice software and imaging systems.
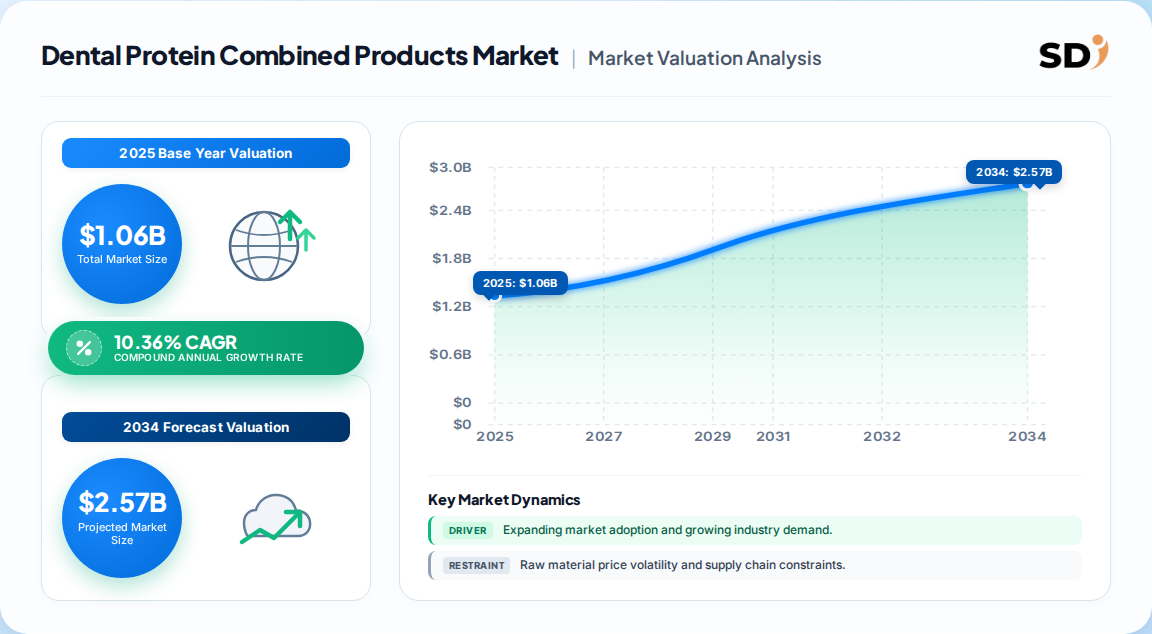
Published estimates place the 2025 global market at approximately USD 1.06 Billion, rising to between USD 1.78 Billion by 2030 and USD 2.84 Billion by 2035 — a spread that reflects horizon length and product-scope definitions rather than any disagreement about underlying demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 1.0 Billion → 1.78 Billion | 2024 | 2030 | 10.0% | Implants, bone grafts, cements, GTR membranes | One published estimate |
| USD 1.06 Billion → 2.84 Billion | 2025 | 2035 | 10.36% | Adds protein-type and application splits | A competing analysis |
Our assessment: the 2030 figure is the more defensible near-term anchor because the 2024 base of USD 1.0 Billion is corroborated by two independent sources and the implied 2025 value (USD 1.1 Billion) sits comfortably alongside the USD 1.06 Billion estimate. The 2035 number is credible only if protein-based grafts penetrate beyond implant dentistry into routine periodontal therapy. Buyers should treat the 10–10.4% band as the planning range and the longer horizon as scenario upside, not a budget number.
Segmentation runs along four axes — product, protein type, application and end user — with dental clinics dominating consumption at roughly 71% of 2024 revenue.
| Parent segment | Children |
|---|---|
| Product | Dental implants, dental bone grafts, dental cements, GTR membranes, other combined protein products |
| Protein type | Collagen, recombinant proteins, growth factors, other proteins |
| Application | Dental implants, periodontal treatment, bone regeneration, restorative dentistry |
| End user | Dental clinics, hospitals, dental laboratories, academic and research institutions |
Implication: collagen remains the workhorse protein because of established reimbursement and clinician familiarity, but recombinant proteins and growth factors carry materially higher per-unit value. Vendors weighted toward commodity collagen face margin erosion; those with recombinant portfolios capture the premium tier.
North America leads with 38–41% of global revenue, underpinned by high dental spending, advanced implant infrastructure and active NIH/NIDCR and FDA engagement in regenerative materials.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.25% |
| Asia-Pacific | 0.22% |
| Latin America | 0.07% |
| Middle East & Africa | 0.05% |
| Parent region | Countries / markets |
|---|---|
| North America | U.S., Canada, Mexico |
| Europe | UK, Germany, France, Italy, Spain, Denmark, Sweden, Norway |
| Asia Pacific | Japan, China, India, South Korea, Australia, Thailand |
| Latin America | Brazil, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa, Kuwait |
Asia Pacific is the fastest-growing region, driven by rising implant procedure volumes, expanding dental infrastructure and public programmes such as India's National Oral Health Programme. Europe holds the second-largest share but grows near GDP levels. Our analysis suggests the Asia Pacific growth premium is roughly 3–4 percentage points above the global average — enough to justify regional capacity commitments, but only where distributor quality and reimbursement clarity are verified.
Growth is driven by an exceptionally large disease burden, rising consumer willingness to pay for oral care, and rapid material innovation; constraints are regulatory timelines and clinical training gaps rather than demand.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Oral disease prevalence (~3.5B affected) | Driver | High | Expands addressable surgical and regenerative case volume |
| Consumer spending on dental care | Driver | High | 91% of adults equate dental visits with annual physicals |
| Bioactive and regenerative material innovation | Driver | Medium | Improves healing outcomes, widens clinical indications |
| Government and academic research funding | Driver | Medium | Accelerates preclinical-to-clinic translation |
| Stringent regulatory approval pathways | Restraint | High | Delays launches and raises cost of portfolio breadth |
| Clinician training and technique adoption | Restraint | Medium | Limits uptake of advanced graft and membrane formats |
Balance of evidence: demand-side drivers are structural and multi-year; restraints are executional and easing. That asymmetry supports the upper half of the published CAGR range. The binding constraint is not patient demand but the number of clinicians trained to place protein-combined regenerative products confidently.
The field is moderately concentrated, with implant and biomaterial majors competing on clinical evidence, regulatory breadth and surgical workflow integration rather than price alone.
| Company | Primary positioning | Strategic lever |
|---|---|---|
| Institut Straumann | Premium implant and regenerative systems | Acquisition-led technology bolt-ons (GalvoSurge, 2023) |
| ZimVie | Implant and biomaterial portfolio | Spin-off focus, restorative workflow bundling |
| Dentsply Sirona | Broad dental consumables and implants | Scale distribution and chairside integration |
| 3M | Restorative and dental materials | Materials science IP and global channel |
| Medtronic | Regenerative biomaterials | Clinical evidence base and hospital access |
| Geistlich Pharma | Collagen membranes and bone grafts | Specialist regenerative credibility |
| Integra LifeSciences | Regenerative and surgical materials | Cross-specialty biomaterial transfer |
Competitive moat: regulatory clearance plus longitudinal clinical data, not manufacturing capacity. Acquisition activity — notably Straumann's 2023 purchase of GalvoSurge Dental AG to address peri-implantitis — signals that incumbents are buying technique-specific solutions rather than building them. Our analysis suggests mid-tier graft specialists will increasingly face a choice between specialty partnership and price-led commoditisation.
Procurement decisions in this category hinge on clinical evidence depth, regulatory status and resorption predictability — not unit price. Buyers should require documented histologic or radiographic outcomes for each graft or membrane format, plus clear indication boundaries between implant-site preservation and periodontal regeneration.
Switching costs are higher than they appear. Once a clinic standardises on a membrane handling characteristic or graft particle size, retraining and protocol revalidation create friction, so vendors with strong chairside education programmes retain accounts disproportionately. Regulatory compliance is a gating factor: FDA evaluation of dental materials, EU medical device requirements and jurisdictional registration differences mean a product cleared in one market may be unavailable or restricted in another — a real risk for multi-country group purchasers.
Operators should also model supply concentration. Collagen-derived inputs carry biological sourcing risk, and single-source membrane supply has caused allocation issues historically. Dual-sourcing critical regenerative components is a cheap hedge against a costly clinical disruption.
The balance of evidence favours the upper end of the published growth range: a 10.4% CAGR through the mid-2030s is achievable because demand drivers are epidemiologically anchored while the main restraints — approval timelines and clinician training — are addressable with capital rather than structural change. The strongest counter-argument is that implant procedure growth in mature markets is decelerating, which would compress the largest product segment and pull the blended CAGR toward 9%. We weight that risk as secondary because Asia Pacific volume growth and bone-graft premiumisation offset mature-market softness.
A second-order effect deserves attention: as recombinant proteins and growth factors enter mainstream workflows, the value pool shifts from material volume to licensed biological performance. That favours companies with IP and clinical trial infrastructure and penalises distributors whose only advantage is logistics. Buyers should expect consolidation among graft specialists and price pressure on undifferentiated collagen products within three to five years.
Actionable strategy:
What would change our conclusion: a sustained decline in implant placement rates across North America and Europe, or a regulatory reclassification of protein-combined grafts as higher-risk devices, would materially lower the forecast. Precise sub-segment forecasting by protein type and country requires the full report's granular dataset.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.36% from 2020-2034 |
| Segmentation |
|
The global market was approximately USD 1.06 Billion in 2025, following a 2024 baseline of roughly USD 1.0 Billion. Published forecasts project between USD 1.78 Billion by 2030 and USD 2.84 Billion by 2035.
The most current published CAGR is 10.36% for 2026 to 2035, while a competing analysis uses 10.0% through 2030. Both converge on low-double-digit expansion, making 10–10.4% the practical planning range.
Dental implants held the largest share at over 45% in 2024, supported by rising implant procedure volumes and technological advances. Dental bone grafts are the fastest-growing segment as protein-enhanced graft materials gain clinical traction.
North America led with 38–41% of global revenue in 2024–2025, driven by high dental spending and advanced implant infrastructure. Asia Pacific is the fastest-growing region on rising procedure volumes and expanding dental infrastructure.
Leading vendors include Institut Straumann, ZimVie, Dentsply Sirona, 3M, Medtronic, Geistlich Pharma, Integra LifeSciences, BTI Biotechnology, GC America, Doxa Dental and Bisco Dental.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research design applies a 70/30 primary-to-secondary split, with the majority of analytical weight placed on direct industry engagement. In-depth interviews were conducted across the value chain with raw material and collagen suppliers, specialised regenerative material producers, contract formulators of bone graft and membrane products, and global dental distributors. Interviewees were drawn from decision-maker designations including VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring both supply-side and commercial perspectives informed our estimates.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Clinical Affairs Leads | 38% |
| Procurement & Sourcing Directors | 34% |
| Regulatory Affairs Managers | 28% |
| Company Type | Representation (%) |
|---|---|
| Regenerative Material & Graft Producers | 42% |
| Collagen & Biomaterial Suppliers | 28% |
| Dental Distributors & Traders | 30% |
Secondary validation draws on official multilateral trade and standards databases including UN Comtrade, WTO tariff records, US ITC data and Eurostat, alongside corporate annual filings, 10-K submissions and investor presentations from publicly listed dental manufacturers. Patent databases and recognised non-profit technical standards bodies were reviewed to map innovation pipelines and material specifications.
We run simultaneous Top-Down allocation from macroeconomic dental expenditure and industry segment shares, and Bottom-Up modelling of manufacturer capacity, product pricing and end-use consumption. The two approaches are reconciled to produce a single defensible base-year value and compound projection.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |