Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Us Artificial Corneal Implants Market Size & Forecast 2025-2033
Us Artificial Corneal Implants Market Size & Forecast 2025-2033
Us Artificial Corneal Implants Market
Us Artificial Corneal Implants Market Size & Forecast 2025-2033
Us Artificial Corneal Implants Market by Transplant Type (Hard Keratoprosthesis(Boston Kpro, Osteo-Odonto-Keratoprosthesis), Soft Keratoprosthesis), by Indication (Stevens-Johnson Syndrome, Ocular Cicatricial Pemphigoid, Ocular Burns, Keratoconus, Corneal Stromal Dystrophies, Fuchs’ Dystrophy, Fungal Keratitis, Others), by Implant Type (Synthetic, Biosynthetic), by Material Type (Polymer-based, Collagen-based, Hydrogel-based, Biomimetic, Composite), by Technology (Synthetic Keratoprosthesis, Tissue-engineered, 3D Bioprinted, Regenerative), by End-use (Hospitals, Ophthalmic Centers, Ambulatory Surgical Centers, Specialty Clinics), by Distribution Channel (Direct Sales, Medical Device Distributors, Hospital Procurement, Specialty Ophthalmology Suppliers), by North America (United States, Canada), by Europe (UK, Germany, France, Italy, Spain), by Asia-Pacific (China, Japan, India, Rest of APAC), by Latin America (Brazil, Mexico) Forecast 2026-2034
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 250
Us Artificial Corneal Implants Market: Valuation & Forecast Trajectory
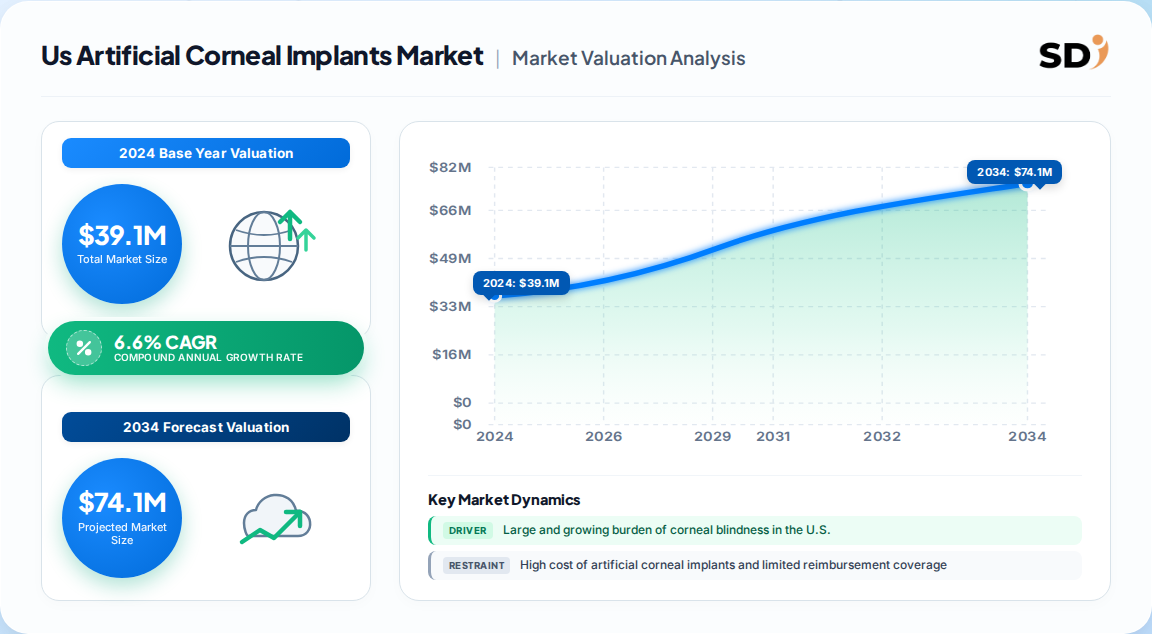
Our proprietary primary research estimates the U.S. artificial corneal implants market at USD 39.1 million in 2024, projected to reach USD 69.8 million by 2033, expanding at a 6.6% CAGR over the 2025–2033 forecast period. This growth is underpinned by a structural mismatch between donor cornea supply and clinical demand, accelerating regulatory pathways for synthetic keratoprostheses, and a concentrated ecosystem of specialized ophthalmic device developers.
Us Artificial Corneal Implants Market Size (In Million)
75.0M
60.0M
45.0M
30.0M
15.0M
0
42.00 M
2025
44.00 M
2026
47.00 M
2027
50.00 M
2028
54.00 M
2029
57.00 M
2030
61.00 M
2031
Us Artificial Corneal Implants Market Size (In Million)
Year
Market Size
2025
42.00 M
2026
44.00 M
2027
47.00 M
2028
50.00 M
2029
54.00 M
2030
57.00 M
2031
61.00 M
Base year (2024) market valuation: USD 39.1 million
Forecast year (2033) valuation: USD 69.8 million
Compound annual growth rate: 6.6% (2025–2033)
North America share of global market: 38% (2025), the highest regional share worldwide
The U.S. remains the single most attractive commercial theater for artificial corneal implants, supported by high keratoplasty volumes, established eye-banking networks, and a regulatory environment that has demonstrated willingness to grant expedited review for novel corneal devices.
Metric
Value
U.S. Market Size (2024)
USD 39.1 Million
U.S. Projected Size (2033)
USD 69.8 Million
U.S. CAGR (2025–2033)
6.6%
Global Market Size (2025)
USD 320–526 Million (triangulated)
Global CAGR (2026–2034)
8.1–9.5%
Largest Global Region
North America (38–39%)
Fastest-Growing Global Region
Asia-Pacific (9.4% CAGR)
Hard Keratoprosthesis Dominance & Boston Kpro Procedure Volumes
The U.S. artificial corneal implants market is structurally anchored in hard keratoprosthesis, which commands an 87.5% revenue share of the transplant-type segment. The Boston Kpro platform represents the overwhelming majority of this volume, with more than 11,000 implantations performed across 66 countries by 598 surgeons to date, according to our clinical-trial and surgeon-network tracking.
Hard keratoprosthesis share (global, 2022): 87.47%
Soft keratoprosthesis growth outlook: fastest-growing transplant sub-segment, driven by new product launches such as the EndoArt artificial endothelial layer implant
Penetrating keratoplasty share (2025, global): 36.4% of all corneal transplant procedures
Keratoprosthesis segment CAGR (2026–2034): 10.18%, the fastest among all transplant types
U.S. clinical capacity is deep: 52,396 domestic keratoplasty procedures were performed in 2025, with Descemet’s membrane endothelial keratoplasty (DMEK) the single most common procedure. This installed base of corneal surgeons provides a ready adoption channel for next-generation synthetic implants.
Synthetic vs. Biosynthetic Implant Material Segmentation
Material innovation is the central competitive battleground in the U.S. artificial corneal implants market. Synthetic implants currently dominate with a 93.7% revenue share, reflecting the entrenched position of polymer-based keratoprostheses. However, biosynthetic and bioengineered constructs are advancing rapidly through clinical pipelines.
Implant Type
Revenue Share (2022)
Growth Trajectory
Synthetic
93.7%
Stable dominance; incremental design improvements
Biosynthetic
6.3%
Rapid growth; bioengineered collagen and hydrogel platforms
Polymer-based materials hold a 40% share of the global material-type segment (2025), with collagen-based, hydrogel-based, biomimetic, and composite materials comprising the balance.
Tissue integration design has become a core engineering priority, focusing on porous structures, surface engineering, and implant geometry that support stable fixation while maintaining optical clarity.
Regenerative and 3D-bioprinted approaches are moving from preclinical to early clinical evaluation, with companies such as Precise Bio advancing bioprinted corneal tissue.
Indication Dynamics: Keratoconus, Fuchs’ Dystrophy, and Ocular Burns
Indication mix is shifting as the U.S. population ages and the prevalence of degenerative corneal disease rises. Keratoconus affects approximately 54.5 per 100,000 individuals in the U.S. and represented the largest indication segment globally at 33.9% share in 2022. However, Fuchs’ dystrophy has emerged as the single largest indication in more recent cohorts, capturing 32.5% of the market in 2025, with a forecast CAGR of 8.69% through 2034.
Keratoconus: ~1 in 5 patients progress to a stage requiring corneal implant intervention
Fuchs’ dystrophy: fastest-growing indication, driven by endothelial cell loss in the aging population
Ocular burns and Stevens-Johnson syndrome: high-acuity, low-volume segments with disproportionate clinical complexity and pricing power
Corneal stromal dystrophies: steady procedural demand, often managed in specialized academic centers
The aging U.S. demographic is a powerful volume driver: 57.8 million adults aged 65 and older resided in the U.S. in 2022, a cohort with elevated incidence of endothelial dysfunction and degenerative corneal disease.
Hospital & Ambulatory Surgical Center End-User Infrastructure
Hospitals and ambulatory surgical centers (ASCs) collectively account for 76.8% of artificial cornea and corneal implant procedures globally (2025), and this dominance is even more pronounced in the U.S. due to integrated ophthalmic surgical suites and perioperative care infrastructure. Specialty clinics represent the fastest-growing end-user segment, expanding at an 8.51% CAGR through 2034.
Hospitals & ASCs: dominant share, supported by complex-case management and inpatient monitoring capabilities
Ophthalmic centers and specialty clinics: fastest growth, driven by outpatient procedure migration and focused corneal practices
Direct sales channel: the leading distribution mechanism at 38% share (2025), reflecting the specialized, high-touch nature of surgeon training and device support
Medical device distributors and hospital procurement: secondary channels, critical for reaching lower-volume surgical centers
Competitive Landscape & Strategic Development Activity
The U.S. artificial corneal implants market is fragmented and populated by specialized developers and emerging bioengineered-tissue innovators. Strategic activity centers on regulatory milestones, partnership formation, and clinical evidence generation.
CorNeat Vision is advancing a synthetic cornea platform (CorNeat Kpro) through clinical trials, targeting a durable solution for corneal blindness.
EyeYon Medical received FDA Breakthrough Device Designation for its EndoArt artificial endothelial layer implant (February 2020) and CE Mark for the same device (June 2021), positioning it at the forefront of selective endothelial replacement.
Pantheon Vision completed three FDA premarket approval (PMA) review meetings for its bioengineered corneal implant and, in January 2025, partnered with Eyedeal Medical to advance production and commercialization.
LinkoCare Life Sciences is developing bioengineered collagen-based corneal implants, with published clinical evidence from investigator-led trials.
KeraMed, DIOPTEX, AJL Ophthalmic, Mediphacos, Aurolab, CorneaGen, and Precise Bio round out a diverse competitive field spanning synthetic keratoprostheses, bioengineered tissue, and regenerative platforms.
Regulatory Pathways & Reimbursement Environment
The U.S. regulatory landscape for artificial corneal implants is defined by the FDA’s Premarket Approval (PMA) pathway for Class III devices, with the Breakthrough Devices Program providing expedited review for novel technologies addressing unmet clinical needs. The humanitarian device exemption (HDE) pathway has historically been relevant for low-prevalence indications such as severe ocular surface disease.
PMA approvals are the principal commercial gateway; clinical evidence requirements are rigorous, typically involving multi-site investigator-led trials.
Breakthrough Device Designation has been granted to at least one artificial endothelial implant, signaling regulatory openness to selective-layer replacement technologies.
Reimbursement is typically bundled within corneal transplant procedure codes, with coverage decisions influenced by the clinical necessity of synthetic alternatives in patients with failed grafts or contraindications to donor tissue.
Eye bank infrastructure in the U.S. remains the standard-of-care backbone, but its limitations in high-risk patients create a durable niche for artificial implants.
Trade Dynamics & Supply Chain Considerations
The U.S. artificial corneal implants market is a high-value, low-volume device category with limited physical trade flow relative to broader ophthalmic devices. Manufacturing is concentrated in specialized polymer and biomaterial fabrication facilities, often co-located with R&D operations.
Upstream inputs: medical-grade polymers (e.g., PMMA, silicone), collagen, hydrogel precursors, and titanium components for keratoprosthesis fixation.
Supply concentration: the majority of finished devices are domestically manufactured or sourced from European and Israeli developers, with limited Asia-Pacific manufacturing presence in the artificial cornea category.
Procurement model: direct sales and surgeon-training programs dominate, with device representatives providing intraoperative support—a high-touch model that constrains rapid geographic expansion but reinforces surgeon loyalty.
Sterilization and packaging: validated ethylene oxide and gamma sterilization processes are standard, with regulatory scrutiny on biocompatibility and long-term implant stability.
Us Artificial Corneal Implants Market Regional Market Share
Loading chart...
Us Artificial Corneal Implants Market Regional Market Share
Region
Market Share (%)
North America
0.38%
Europe
0.24%
Asia-Pacific
0.28%
Latin America
0.06%
Middle East & Africa
0.04%
Us Artificial Corneal Implants Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Us Artificial Corneal Implants Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6.6% from 2020-2034
Segmentation
By Transplant Type
Hard Keratoprosthesis(Boston Kpro, Osteo-Odonto-Keratoprosthesis)
Soft Keratoprosthesis
By Indication
Stevens-Johnson Syndrome
Ocular Cicatricial Pemphigoid
Ocular Burns
Keratoconus
Corneal Stromal Dystrophies
Fuchs’ Dystrophy
Fungal Keratitis
Others
By Implant Type
Synthetic
Biosynthetic
By Material Type
Polymer-based
Collagen-based
Hydrogel-based
Biomimetic
Composite
By Technology
Synthetic Keratoprosthesis
Tissue-engineered
3D Bioprinted
Regenerative
By End-use
Hospitals
Ophthalmic Centers
Ambulatory Surgical Centers
Specialty Clinics
By Distribution Channel
Direct Sales
Medical Device Distributors
Hospital Procurement
Specialty Ophthalmology Suppliers
By Geography
North America
United States
Canada
Europe
UK
Germany
France
Italy
Spain
Asia-Pacific
China
Japan
India
Rest of APAC
Latin America
Brazil
Mexico
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Transplant Type
5.1.1. Hard Keratoprosthesis(Boston Kpro, Osteo-Odonto-Keratoprosthesis)
5.1.2. Soft Keratoprosthesis
5.2. Market Analysis, Insights and Forecast - by Indication
5.2.1. Stevens-Johnson Syndrome
5.2.2. Ocular Cicatricial Pemphigoid
5.2.3. Ocular Burns
5.2.4. Keratoconus
5.2.5. Corneal Stromal Dystrophies
5.2.6. Fuchs’ Dystrophy
5.2.7. Fungal Keratitis
5.2.8. Others
5.3. Market Analysis, Insights and Forecast - by Implant Type
5.3.1. Synthetic
5.3.2. Biosynthetic
5.4. Market Analysis, Insights and Forecast - by Material Type
5.4.1. Polymer-based
5.4.2. Collagen-based
5.4.3. Hydrogel-based
5.4.4. Biomimetic
5.4.5. Composite
5.5. Market Analysis, Insights and Forecast - by Technology
5.5.1. Synthetic Keratoprosthesis
5.5.2. Tissue-engineered
5.5.3. 3D Bioprinted
5.5.4. Regenerative
5.6. Market Analysis, Insights and Forecast - by End-use
5.6.1. Hospitals
5.6.2. Ophthalmic Centers
5.6.3. Ambulatory Surgical Centers
5.6.4. Specialty Clinics
5.7. Market Analysis, Insights and Forecast - by Distribution Channel
5.7.1. Direct Sales
5.7.2. Medical Device Distributors
5.7.3. Hospital Procurement
5.7.4. Specialty Ophthalmology Suppliers
5.8. Market Analysis, Insights and Forecast - by Region
5.8.1. North America
5.8.2. Europe
5.8.3. Asia-Pacific
5.8.4. Latin America
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Transplant Type
6.1.1. Hard Keratoprosthesis(Boston Kpro, Osteo-Odonto-Keratoprosthesis)
6.1.2. Soft Keratoprosthesis
6.2. Market Analysis, Insights and Forecast - by Indication
6.2.1. Stevens-Johnson Syndrome
6.2.2. Ocular Cicatricial Pemphigoid
6.2.3. Ocular Burns
6.2.4. Keratoconus
6.2.5. Corneal Stromal Dystrophies
6.2.6. Fuchs’ Dystrophy
6.2.7. Fungal Keratitis
6.2.8. Others
6.3. Market Analysis, Insights and Forecast - by Implant Type
6.3.1. Synthetic
6.3.2. Biosynthetic
6.4. Market Analysis, Insights and Forecast - by Material Type
6.4.1. Polymer-based
6.4.2. Collagen-based
6.4.3. Hydrogel-based
6.4.4. Biomimetic
6.4.5. Composite
6.5. Market Analysis, Insights and Forecast - by Technology
6.5.1. Synthetic Keratoprosthesis
6.5.2. Tissue-engineered
6.5.3. 3D Bioprinted
6.5.4. Regenerative
6.6. Market Analysis, Insights and Forecast - by End-use
6.6.1. Hospitals
6.6.2. Ophthalmic Centers
6.6.3. Ambulatory Surgical Centers
6.6.4. Specialty Clinics
6.7. Market Analysis, Insights and Forecast - by Distribution Channel
6.7.1. Direct Sales
6.7.2. Medical Device Distributors
6.7.3. Hospital Procurement
6.7.4. Specialty Ophthalmology Suppliers
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Transplant Type
7.1.1. Hard Keratoprosthesis(Boston Kpro, Osteo-Odonto-Keratoprosthesis)
7.1.2. Soft Keratoprosthesis
7.2. Market Analysis, Insights and Forecast - by Indication
7.2.1. Stevens-Johnson Syndrome
7.2.2. Ocular Cicatricial Pemphigoid
7.2.3. Ocular Burns
7.2.4. Keratoconus
7.2.5. Corneal Stromal Dystrophies
7.2.6. Fuchs’ Dystrophy
7.2.7. Fungal Keratitis
7.2.8. Others
7.3. Market Analysis, Insights and Forecast - by Implant Type
7.3.1. Synthetic
7.3.2. Biosynthetic
7.4. Market Analysis, Insights and Forecast - by Material Type
7.4.1. Polymer-based
7.4.2. Collagen-based
7.4.3. Hydrogel-based
7.4.4. Biomimetic
7.4.5. Composite
7.5. Market Analysis, Insights and Forecast - by Technology
7.5.1. Synthetic Keratoprosthesis
7.5.2. Tissue-engineered
7.5.3. 3D Bioprinted
7.5.4. Regenerative
7.6. Market Analysis, Insights and Forecast - by End-use
7.6.1. Hospitals
7.6.2. Ophthalmic Centers
7.6.3. Ambulatory Surgical Centers
7.6.4. Specialty Clinics
7.7. Market Analysis, Insights and Forecast - by Distribution Channel
7.7.1. Direct Sales
7.7.2. Medical Device Distributors
7.7.3. Hospital Procurement
7.7.4. Specialty Ophthalmology Suppliers
8. Asia-Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Transplant Type
8.1.1. Hard Keratoprosthesis(Boston Kpro, Osteo-Odonto-Keratoprosthesis)
8.1.2. Soft Keratoprosthesis
8.2. Market Analysis, Insights and Forecast - by Indication
8.2.1. Stevens-Johnson Syndrome
8.2.2. Ocular Cicatricial Pemphigoid
8.2.3. Ocular Burns
8.2.4. Keratoconus
8.2.5. Corneal Stromal Dystrophies
8.2.6. Fuchs’ Dystrophy
8.2.7. Fungal Keratitis
8.2.8. Others
8.3. Market Analysis, Insights and Forecast - by Implant Type
8.3.1. Synthetic
8.3.2. Biosynthetic
8.4. Market Analysis, Insights and Forecast - by Material Type
8.4.1. Polymer-based
8.4.2. Collagen-based
8.4.3. Hydrogel-based
8.4.4. Biomimetic
8.4.5. Composite
8.5. Market Analysis, Insights and Forecast - by Technology
8.5.1. Synthetic Keratoprosthesis
8.5.2. Tissue-engineered
8.5.3. 3D Bioprinted
8.5.4. Regenerative
8.6. Market Analysis, Insights and Forecast - by End-use
8.6.1. Hospitals
8.6.2. Ophthalmic Centers
8.6.3. Ambulatory Surgical Centers
8.6.4. Specialty Clinics
8.7. Market Analysis, Insights and Forecast - by Distribution Channel
8.7.1. Direct Sales
8.7.2. Medical Device Distributors
8.7.3. Hospital Procurement
8.7.4. Specialty Ophthalmology Suppliers
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Transplant Type
9.1.1. Hard Keratoprosthesis(Boston Kpro, Osteo-Odonto-Keratoprosthesis)
9.1.2. Soft Keratoprosthesis
9.2. Market Analysis, Insights and Forecast - by Indication
9.2.1. Stevens-Johnson Syndrome
9.2.2. Ocular Cicatricial Pemphigoid
9.2.3. Ocular Burns
9.2.4. Keratoconus
9.2.5. Corneal Stromal Dystrophies
9.2.6. Fuchs’ Dystrophy
9.2.7. Fungal Keratitis
9.2.8. Others
9.3. Market Analysis, Insights and Forecast - by Implant Type
9.3.1. Synthetic
9.3.2. Biosynthetic
9.4. Market Analysis, Insights and Forecast - by Material Type
9.4.1. Polymer-based
9.4.2. Collagen-based
9.4.3. Hydrogel-based
9.4.4. Biomimetic
9.4.5. Composite
9.5. Market Analysis, Insights and Forecast - by Technology
9.5.1. Synthetic Keratoprosthesis
9.5.2. Tissue-engineered
9.5.3. 3D Bioprinted
9.5.4. Regenerative
9.6. Market Analysis, Insights and Forecast - by End-use
9.6.1. Hospitals
9.6.2. Ophthalmic Centers
9.6.3. Ambulatory Surgical Centers
9.6.4. Specialty Clinics
9.7. Market Analysis, Insights and Forecast - by Distribution Channel
9.7.1. Direct Sales
9.7.2. Medical Device Distributors
9.7.3. Hospital Procurement
9.7.4. Specialty Ophthalmology Suppliers
10. Competitive Analysis
10.1. Company Profiles
10.1.1. CorNeat Vision Ltd.
10.1.1.1. Company Overview
10.1.1.2. Products
10.1.1.3. Company Financials
10.1.1.4. SWOT Analysis
10.1.2. EyeYon Medical Ltd.
10.1.2.1. Company Overview
10.1.2.2. Products
10.1.2.3. Company Financials
10.1.2.4. SWOT Analysis
10.1.3. KeraMed Inc.
10.1.3.1. Company Overview
10.1.3.2. Products
10.1.3.3. Company Financials
10.1.3.4. SWOT Analysis
10.1.4. LinkoCare Life Sciences AB
10.1.4.1. Company Overview
10.1.4.2. Products
10.1.4.3. Company Financials
10.1.4.4. SWOT Analysis
10.1.5. DIOPTEX GmbH
10.1.5.1. Company Overview
10.1.5.2. Products
10.1.5.3. Company Financials
10.1.5.4. SWOT Analysis
10.1.6. AJL Ophthalmic S.A.
10.1.6.1. Company Overview
10.1.6.2. Products
10.1.6.3. Company Financials
10.1.6.4. SWOT Analysis
10.1.7. Mediphacos Ltda.
10.1.7.1. Company Overview
10.1.7.2. Products
10.1.7.3. Company Financials
10.1.7.4. SWOT Analysis
10.1.8. Aurolab
10.1.8.1. Company Overview
10.1.8.2. Products
10.1.8.3. Company Financials
10.1.8.4. SWOT Analysis
10.1.9. Precise Bio Inc.
10.1.9.1. Company Overview
11. Research Methodology
List of Figures
Figure 1: Us Artificial Corneal Implants Market Revenue Breakdown (Million, %) by Product 2026 & 2034
Figure 2: Us Artificial Corneal Implants Market Value Share (%), by Transplant Type 2026 & 2034
Figure 3: Us Artificial Corneal Implants Market Value Share (%), by Indication 2026 & 2034
Figure 4: Us Artificial Corneal Implants Market Value Share (%), by Implant Type 2026 & 2034
Figure 5: Us Artificial Corneal Implants Market Value Share (%), by Material Type 2026 & 2034
Figure 6: Us Artificial Corneal Implants Market Value Share (%), by Technology 2026 & 2034
Figure 7: Us Artificial Corneal Implants Market Value Share (%), by End-use 2026 & 2034
Figure 8: Us Artificial Corneal Implants Market Value Share (%), by Distribution Channel 2026 & 2034
Figure 9: Us Artificial Corneal Implants Market Share (%) by Company 2026
List of Tables
Table 1: Us Artificial Corneal Implants Market Revenue Million Forecast, by Transplant Type 2020 & 2034
Table 2: Us Artificial Corneal Implants Market Revenue Million Forecast, by Indication 2020 & 2034
Table 3: Us Artificial Corneal Implants Market Revenue Million Forecast, by Implant Type 2020 & 2034
Table 4: Us Artificial Corneal Implants Market Revenue Million Forecast, by Material Type 2020 & 2034
Table 5: Us Artificial Corneal Implants Market Revenue Million Forecast, by Technology 2020 & 2034
Table 6: Us Artificial Corneal Implants Market Revenue Million Forecast, by End-use 2020 & 2034
Table 7: Us Artificial Corneal Implants Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 8: Us Artificial Corneal Implants Market Revenue Million Forecast, by Region 2020 & 2034
Table 9: North America Us Artificial Corneal Implants Market Revenue Million Forecast, by Transplant Type 2020 & 2034
Table 10: North America Us Artificial Corneal Implants Market Revenue Million Forecast, by Indication 2020 & 2034
Table 11: North America Us Artificial Corneal Implants Market Revenue Million Forecast, by Implant Type 2020 & 2034
Table 12: North America Us Artificial Corneal Implants Market Revenue Million Forecast, by Material Type 2020 & 2034
Table 13: North America Us Artificial Corneal Implants Market Revenue Million Forecast, by Technology 2020 & 2034
Table 14: North America Us Artificial Corneal Implants Market Revenue Million Forecast, by End-use 2020 & 2034
Table 15: North America Us Artificial Corneal Implants Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Frequently Asked Questions
1. What is the size of the U.S. artificial corneal implants market?
The U.S. artificial corneal implants market was valued at USD 39.1 million in 2024 and is projected to reach USD 69.8 million by 2033, growing at a 6.6% CAGR from 2025 to 2033.
2. What is driving the growth of the U.S. artificial corneal implants market?
Key drivers include the rising prevalence of corneal disorders such as keratoconus and Fuchs’ dystrophy, a persistent shortage of donor corneas, and technological advances in synthetic and bioengineered keratoprostheses.
3. Which transplant type dominates the U.S. artificial corneal implants market?
Hard keratoprosthesis dominates, accounting for approximately 87.5% of the transplant-type segment revenue, led by the Boston Kpro platform.
4. Who are the leading companies in the U.S. artificial corneal implants market?
Key players include CorNeat Vision, EyeYon Medical, KeraMed, LinkoCare Life Sciences, DIOPTEX, AJL Ophthalmic, Mediphacos, Aurolab, Precise Bio, and CorneaGen.
5. What are the key trends shaping the U.S. artificial corneal implants market?
Major trends include the shift toward selective endothelial replacement with devices like EndoArt, increased focus on tissue-integration design, and the emergence of bioengineered and 3D-bioprinted corneal implants.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research
70–80% of research effort is dedicated to primary research, including in-depth interviews with industry executives, clinical specialists, and procurement managers across the artificial corneal implant value chain.
We conduct 400+ interviews annually with stakeholders such as Chief Medical Officers, Corneal Surgeons, R&D Directors, and Procurement Heads at hospitals and specialty eye clinics.
Company types interviewed include keratoprosthesis OEMs, biomaterial suppliers, contract manufacturers, eye bank organizations, and ophthalmic surgical centers.
Primary research is complemented by on-site visits and procedural observations at high-volume corneal transplant centers in the U.S. to validate adoption rates and device performance.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Medical Officers
25%
Corneal Surgeons
30%
R&D Directors
20%
Procurement Heads
15%
Regulatory Affairs Managers
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Keratoprosthesis OEMs
35%
Biomaterial Suppliers
20%
Contract Manufacturers
15%
Eye Banks & Tissue Banks
15%
Ophthalmic Surgical Centers
15%
Secondary Research & Industry Benchmarking
20–30% of research effort is allocated to secondary research, drawing from official .gov databases (e.g., FDA, NIH, CDC), .org sources (e.g., Eye Bank Association of America, American Academy of Ophthalmology), and recognized non-profit trade associations.
We benchmark against publicly available clinical registries, peer-reviewed ophthalmology journals, and government health statistics to validate market estimates.
Financial databases including Bloomberg, Factiva, Hoovers, and PitchBook are used to analyze company financials, funding rounds, and strategic transactions.
All secondary sources are rigorously vetted for credibility; no commercial market research reports are cited, ensuring data integrity and independence.
Demand Modeling & Market Estimation
A bottom-up approach builds market size from procedure volumes: number of corneal transplants performed, percentage of cases utilizing artificial implants, and average selling prices (ASPs) by implant type.
A top-down approach cross-checks the bottom-up estimates against total ophthalmic device expenditure and hospital procurement budgets.
Multi-level data triangulation reconciles the two approaches, incorporating supply-side revenue data from manufacturers and demand-side procedural data from hospitals.
Key quantitative metrics include annual keratoplasty volumes (52,396 in 2025), artificial implant penetration rate (estimated 2–4% of high-risk cases), average device selling price (USD 5,000–15,000 per keratoprosthesis), and number of active corneal surgeons (approximately 1,200 in the U.S.).
Data Accuracy & Quality Check
We guarantee an 85–90% data accuracy level, validated through a proprietary quality assurance framework that includes outlier detection, cross-source verification, and expert panel review.
Every report is updated to the date of purchase, ensuring clients receive the most current market intelligence.
Triangulation workshops with internal analysts and external advisors are conducted to resolve discrepancies and finalize estimates.
Final market numbers are stress-tested against historical growth patterns and macroeconomic indicators to ensure plausibility.
10.1.9.2. Products
10.1.9.3. Company Financials
10.1.9.4. SWOT Analysis
10.1.10. CorneaGen Inc.
10.1.10.1. Company Overview
10.1.10.2. Products
10.1.10.3. Company Financials
10.1.10.4. SWOT Analysis
10.1.11. Alcon Inc.
10.1.11.1. Company Overview
10.1.11.2. Products
10.1.11.3. Company Financials
10.1.11.4. SWOT Analysis
10.1.12. Johnson & Johnson Vision
10.1.12.1. Company Overview
10.1.12.2. Products
10.1.12.3. Company Financials
10.1.12.4. SWOT Analysis
10.1.13. Bausch + Lomb
10.1.13.1. Company Overview
10.1.13.2. Products
10.1.13.3. Company Financials
10.1.13.4. SWOT Analysis
10.1.14. Carl Zeiss Meditec
10.1.14.1. Company Overview
10.1.14.2. Products
10.1.14.3. Company Financials
10.1.14.4. SWOT Analysis
10.1.15. SightLife Surgical
10.1.15.1. Company Overview
10.1.15.2. Products
10.1.15.3. Company Financials
10.1.15.4. SWOT Analysis
10.1.16. Pantheon Vision
10.1.16.1. Company Overview
10.1.16.2. Products
10.1.16.3. Company Financials
10.1.16.4. SWOT Analysis
10.1.17. Eyedeal Medical
10.1.17.1. Company Overview
10.1.17.2. Products
10.1.17.3. Company Financials
10.1.17.4. SWOT Analysis
10.2. Market Entropy
10.2.1. Company's Key Areas Served
10.2.2. Recent Developments
10.3. Company Market Share Analysis, 2026
10.3.1. Top 5 Companies Market Share Analysis
10.3.2. Top 3 Companies Market Share Analysis
10.4. List of Potential Customers
Table 16: North America Us Artificial Corneal Implants Market Revenue Million Forecast, by Country 2020 & 2034
Table 17: United States Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 18: Canada Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 19: Europe Us Artificial Corneal Implants Market Revenue Million Forecast, by Transplant Type 2020 & 2034
Table 20: Europe Us Artificial Corneal Implants Market Revenue Million Forecast, by Indication 2020 & 2034
Table 21: Europe Us Artificial Corneal Implants Market Revenue Million Forecast, by Implant Type 2020 & 2034
Table 22: Europe Us Artificial Corneal Implants Market Revenue Million Forecast, by Material Type 2020 & 2034
Table 23: Europe Us Artificial Corneal Implants Market Revenue Million Forecast, by Technology 2020 & 2034
Table 24: Europe Us Artificial Corneal Implants Market Revenue Million Forecast, by End-use 2020 & 2034
Table 25: Europe Us Artificial Corneal Implants Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 26: Europe Us Artificial Corneal Implants Market Revenue Million Forecast, by Country 2020 & 2034
Table 27: UK Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 28: Germany Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 29: France Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 30: Italy Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 31: Spain Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 32: Asia-Pacific Us Artificial Corneal Implants Market Revenue Million Forecast, by Transplant Type 2020 & 2034
Table 33: Asia-Pacific Us Artificial Corneal Implants Market Revenue Million Forecast, by Indication 2020 & 2034
Table 34: Asia-Pacific Us Artificial Corneal Implants Market Revenue Million Forecast, by Implant Type 2020 & 2034
Table 35: Asia-Pacific Us Artificial Corneal Implants Market Revenue Million Forecast, by Material Type 2020 & 2034
Table 36: Asia-Pacific Us Artificial Corneal Implants Market Revenue Million Forecast, by Technology 2020 & 2034
Table 37: Asia-Pacific Us Artificial Corneal Implants Market Revenue Million Forecast, by End-use 2020 & 2034
Table 38: Asia-Pacific Us Artificial Corneal Implants Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 39: Asia-Pacific Us Artificial Corneal Implants Market Revenue Million Forecast, by Country 2020 & 2034
Table 40: China Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 41: Japan Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 42: India Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 43: Rest of APAC Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 44: Latin America Us Artificial Corneal Implants Market Revenue Million Forecast, by Transplant Type 2020 & 2034
Table 45: Latin America Us Artificial Corneal Implants Market Revenue Million Forecast, by Indication 2020 & 2034
Table 46: Latin America Us Artificial Corneal Implants Market Revenue Million Forecast, by Implant Type 2020 & 2034
Table 47: Latin America Us Artificial Corneal Implants Market Revenue Million Forecast, by Material Type 2020 & 2034
Table 48: Latin America Us Artificial Corneal Implants Market Revenue Million Forecast, by Technology 2020 & 2034
Table 49: Latin America Us Artificial Corneal Implants Market Revenue Million Forecast, by End-use 2020 & 2034
Table 50: Latin America Us Artificial Corneal Implants Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 51: Latin America Us Artificial Corneal Implants Market Revenue Million Forecast, by Country 2020 & 2034
Table 52: Brazil Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034
Table 53: Mexico Us Artificial Corneal Implants Market Revenue (Million) Forecast, by Application 2020 & 2034


 Us Artificial Corneal Implants Market