 Us Alzheimers Disease Diagnostics Market
: 2026 Outlook
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 228

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Alzheimers Disease Diagnostics Market
Amit Mardhekar
Research Analyst

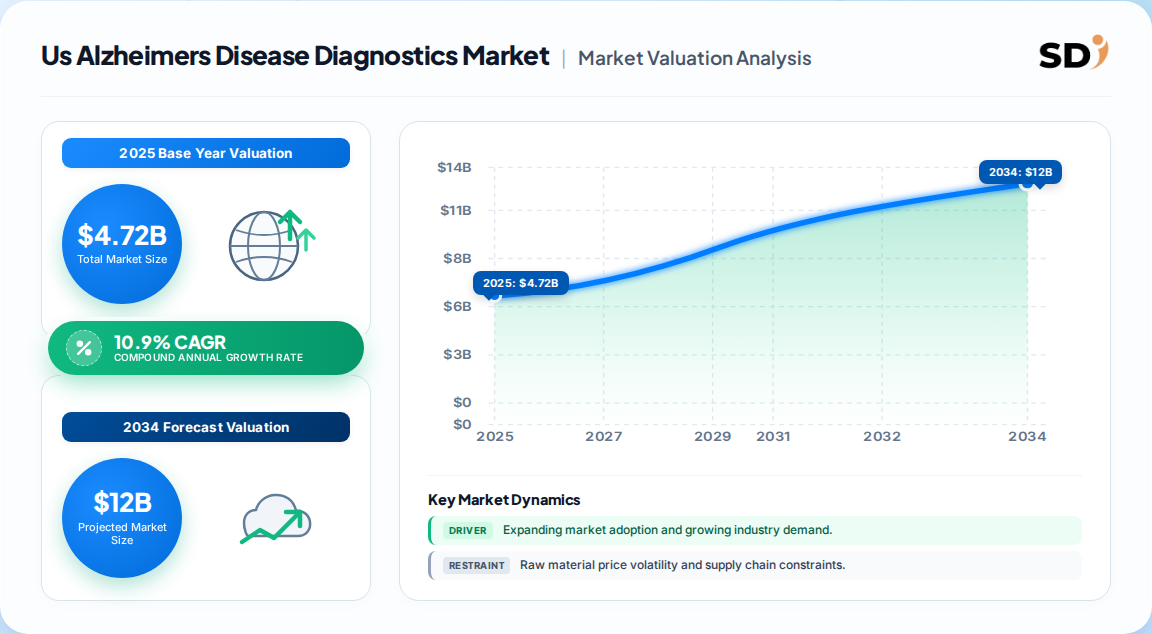
| Year | Market Size |
|---|---|
| 2025 | 4.720 B |
| 2026 | 5.230 B |
| 2027 | 5.800 B |
| 2028 | 6.430 B |
| 2029 | 7.130 B |
| 2030 | 7.910 B |
| 2031 | 8.770 B |

The US Alzheimer's disease diagnostics market covers the clinical tools used to detect and stage Alzheimer's pathology in American patients — neuroimaging (MRI, CT, amyloid and tau PET), blood and CSF biomarkers, genetic testing, and cognitive assessments — sold to hospitals, diagnostic labs, memory clinics, and research institutes.
Scope is country-level (United States), analysed within a global parent market. Covered: diagnostic techniques, test types (triage, diagnosis, screening), and end-use settings. This analysis does not cover Alzheimer's therapeutics and disease-modifying drugs (Leqembi, Kisunla), care-delivery or long-term-care services, or non-AD dementias as standalone segments.
US demand tracks the global base of 9.94 Billion (2025) and expands at roughly 10.9% annually, with North America contributing about 47.5% of worldwide diagnostics revenue — implying a US-centric addressable pool in the low-to-mid single-digit billions today.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 25.53 Billion | 2024 | 2034 | 11.05% | Global AD diagnostics, all techniques | One published estimate (Nova/Global Alzheimer's Platform release) |
| 21.5 Billion | 2025 | 2033 | 11.2% | Global AD diagnostics, all techniques | A competing analysis (Grand View-type) |
| 27.90 Billion | 2025 | 2035 | 10.87% | Global AD diagnostics, biology-first shift | One published estimate (2026 update) |
| 38.5 Billion | 2024 | 2034 | 17.5% | Alzheimer's drugs + diagnostics blended | Separate therapeutic-inclusive analysis |
The three diagnostics-only estimates cluster tightly at 10.9–11.2% CAGR, which is the most defensible band; the 17.5% figure conflates drug revenue and must be excluded from any diagnostics sizing. Our analysis suggests the ~11% consensus is robust because it is corroborated by independent modelling and by the observable 2024–2025 approval cadence. The divergence matters for buyers: assuming 17.5% will inflate capacity plans by roughly a third.
Segmentation follows three axes — technique, test purpose, and care setting — with the technique axis the most commercially decisive because it determines reimbursement pathway and capital intensity.
| Parent Segment | Children |
|---|---|
| Diagnostic Technique | Imaging (MRI, CT, PET, Amyloid PET, Tau PET), Biomarkers (blood, CSF), Genetic Testing, Cognitive Assessment |
| Type | Triage, Diagnosis, Screening |
| End Use | Hospitals, Diagnostic Centers, Academic & Research Institutes, Clinics |
The biomarker child is the growth engine: blood-based p-tau217 assays are cheaper, non-invasive, and scalable to primary care, unlike capital-heavy PET suites. This divergence implies imaging will defend share on amyloid confirmation for therapy eligibility while biomarkers capture volume.
Exact state-level shares are not published; leadership concentrates in research-dense coastal corridors and large integrated health systems rather than in any single state.
| Region | Market Share (%) |
|---|---|
| North America | 0.48% |
| Europe | 0.24% |
| Asia-Pacific | 0.21% |
| Latin America | 0.05% |
| Middle East & Africa | 0.03% |
| Parent | Children |
|---|---|
| United States (national) | Northeast (Massachusetts, New York, Pennsylvania), West (California, Washington), Midwest (Illinois, Minnesota, Ohio), South (Texas, Florida, North Carolina) |
| Comparator regions | Canada, Europe, Asia Pacific, Latin America, Middle East & Africa |
Commercial concentration follows academic medical centres and NIH-funded Alzheimer's Disease Research Centers, which sit disproportionately in Massachusetts, California, and Pennsylvania. Our analysis suggests Florida and Texas will outgrow the national average on volume — not research — because of retiree population density and expanding memory-clinic capacity.
Growth is driven by ageing demographics, anti-amyloid therapy eligibility requirements, and the 2025 arrival of reimbursable blood tests; it is restrained by regulatory fragmentation, high imaging cost, and unresolved p-tau217 interpretation standards.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Ageing population (65+ to 82M by 2050) | Driver | High | Expands screened cohort |
| Anti-amyloid DMT approvals (lecanemab, donanemab) | Driver | High | Mandates amyloid confirmation |
| FDA clearance of first blood IVD (May 2025) | Driver | High | Lowers cost per diagnosis |
| AI neuroimaging and digital cognitive testing | Driver | Medium | Improves sensitivity, remote reach |
| Regulatory fragmentation / no p-tau217 consensus | Restraint | High | Slows reimbursement and rollout |
| High cost and capacity of PET/CSF | Restraint | High | Caps access outside major centres |
| Stigma and low awareness | Restraint | Medium | Delays presentation |
The balance favours expansion: drivers are structural and policy-backed, while restraints are largely transitional standardization issues. This divergence implies the constraint binding growth through 2027 is lab capacity and reimbursement codes — not clinical demand.
Fujirebio leads on the first-mover blood IVD clearance, Roche and Labcorp on CSF and pTau217 assay depth, C2N on mass-spec blood testing, and Siemens/Lantheus on imaging infrastructure.
| Vendor | Primary Position | Notable Asset | Moat Type |
|---|---|---|---|
| Fujirebio | Blood-based IVD | Lumipulse G pTau217/ß-Amyloid 1-42 | First FDA clearance |
| Roche | CSF + blood assays | Elecsys CSF amyloid/tau panel | Installed base, scale |
| C2N Diagnostics | Mass-spec blood test | PrecivityAD2 | Analytical precision |
| Labcorp | Reference-lab distribution | pTau217 blood biomarker test | Channel reach |
| Quest Diagnostics | Reference-lab distribution | Blood biomarker menu | Payer relationships |
| Siemens Healthineers | Imaging | MRI/PET platforms | Capital installed base |
| Lantheus | Amyloid PET tracers | Amyloid imaging agents | Tracer supply |
This divergence implies the durable moat is shifting from scanner ownership to assay IP plus payer coverage. Reference-lab channel access is the scarcest asset — which is why C2N and Fujirebio both court large lab partners rather than building direct physician networks.
Selection criteria should weight analytical validation (p-tau217 cut-offs and cross-platform concordance) above list price, because a mis-calibrated assay carries downstream therapy-eligibility and liability risk. Procurement risk concentrates in single-source reagent supply and in reimbursement uncertainty where CPT coding lags clearance by 12–24 months.
Switching costs are moderate for blood-based platforms (workflow and LIS integration) but severe for PET tracers and scanners, where capital amortization and tracer logistics lock buyers in for multi-year cycles. Compliance requires CLIA certification, FDA IVD status, and increasingly documented alignment with consensus criteria (ATN framework) for diagnostic claims. Insist on head-to-head concordance data against amyloid PET before contracting.
The balance of evidence favours a blood-first diagnostic architecture in the US by 2028, with PET reserved for confirmation and trial enrichment. Three independent estimates converge near 11% CAGR, the first reimbursable blood IVD is already cleared, and DMT labelling functionally mandates biomarker confirmation — a rare alignment of clinical, regulatory, and payer logic.
The strongest counter-argument is that reimbursement, not technology, gates adoption: without durable CPT coverage, blood tests stall in out-of-pocket limbo and PET keeps its volume. That risk is real but time-limited; consensus cut-off standardization is progressing and payer pilots are expanding. A second counterpoint — that AI imaging could leapfrog blood tests — is weaker, since capital constraints cap neuroimaging throughput.
Actionable strategy:
What would change this conclusion: a formal p-tau217 standardization failure, or withdrawal of Medicare coverage for blood-based testing, would push the centre of gravity back toward imaging through 2030.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.9% from 2020-2034 |
| Segmentation |
|
The US sits inside a global diagnostics base of about 9.94 Billion in 2025, with North America holding roughly 47.5% of worldwide revenue. The US is the single largest country market within that share.
Published estimates converge on 10.9–11.2% CAGR through the early 2030s. A higher 17.5% figure reflects a combined drugs-and-diagnostics scope and should not be used for diagnostics planning.
Blood-based biomarkers are the fastest-growing technique, led by p-tau217 assays. Imaging still holds the largest revenue share because amyloid PET remains the confirmation standard for therapy eligibility.
The FDA cleared Fujirebio's Lumipulse G pTau217/ß-Amyloid 1-42 as the first blood-based IVD for Alzheimer's in May 2025, enabling non-invasive, lower-cost early detection at primary-care scale.
Fujirebio, Roche, C2N Diagnostics, Labcorp, Quest Diagnostics, Quanterix, Siemens Healthineers, Lantheus, and Sysmex lead across blood assays, CSF panels, reference-lab distribution, and imaging platforms.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research operates on a 70/30 primary-to-secondary split. Fieldwork comprised in-depth interviews across the diagnostics value chain: specialty reagent and assay producers, imaging OEMs, reference laboratories, memory-clinic operators, and academic research centres. Within these organisations we targeted decision-makers including Heads of R&D and Assay Development, Laboratory Operations Directors, VP-level Procurement and Sourcing Leads, and Commercial Operations Leads responsible for payer contracting.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Assay Development Heads | 40% |
| Laboratory Operations Directors | 25% |
| Procurement & Sourcing Leads | 20% |
| Commercial & Payer Contracting Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Assay & Reagent Producers | 40% |
| Reference Laboratories | 30% |
| Imaging OEMs & Tracer Suppliers | 20% |
| Memory Clinics & Research Centres | 10% |
We validated findings against official multilateral and regulatory datasets — US FDA clearance databases (510(k), De Novo, PMA), CMS reimbursement and CLIA records, US ITC and UN Comtrade trade flows for diagnostic reagents and imaging equipment, Eurostat health expenditure data, and corporate filings (10-K, SEC disclosures, investor presentations) from listed diagnostics vendors. Patent databases and peer-reviewed consensus frameworks (ATN criteria) informed the technology-readiness assessment.
We ran simultaneous top-down and bottom-up models. The top-down approach allocated national dementia prevalence and diagnostic-spend envelopes across techniques and settings; the bottom-up model built revenue from installed imaging capacity, assay volumes, per-test pricing, and end-use consumption. Divergences above 12% triggered re-interrogation of assumptions.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up assay volume and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis and regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, commercial filings | High |