 Us Transdermal Drug Delivery System Market
US Transdermal Drug Delivery System Market 2025
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 278

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Transdermal Drug Delivery System Market
Amit Mardhekar
Research Analyst

| Metric | Figure | Base | Horizon |
|---|---|---|---|
| Market size | USD 33.60 billion | 2023 | 2030 |
| Forecast value | USD 71.63 billion | — | 2030 |
| CAGR | 11.4% | 2023 | 2030 |
| Year | Market Size |
|---|---|
| 2023 | 33.60 B |
| 2024 | 37.43 B |
| 2025 | 41.70 B |
| 2026 | 46.45 B |
| 2027 | 51.75 B |
| 2028 | 57.65 B |
| 2029 | 64.22 B |

The U.S. transdermal drug delivery system market comprises technologies that deliver therapeutics through the skin into systemic circulation without needles, including passive patches, iontophoresis, microneedle arrays and other active enhancement systems. It spans pain management, CNS, cardiovascular, hormonal and smoking-cessation applications across home-care, clinical and hospital settings.
This report covers U.S. revenue from transdermal patches and active/passive delivery technologies segmented by technology, application and end user. It does not cover oral or injectable drug delivery, nor adjacent dermal cosmetics outside therapeutic labeling. This analysis does not cover global or non-U.S. regional markets except where referenced as context.
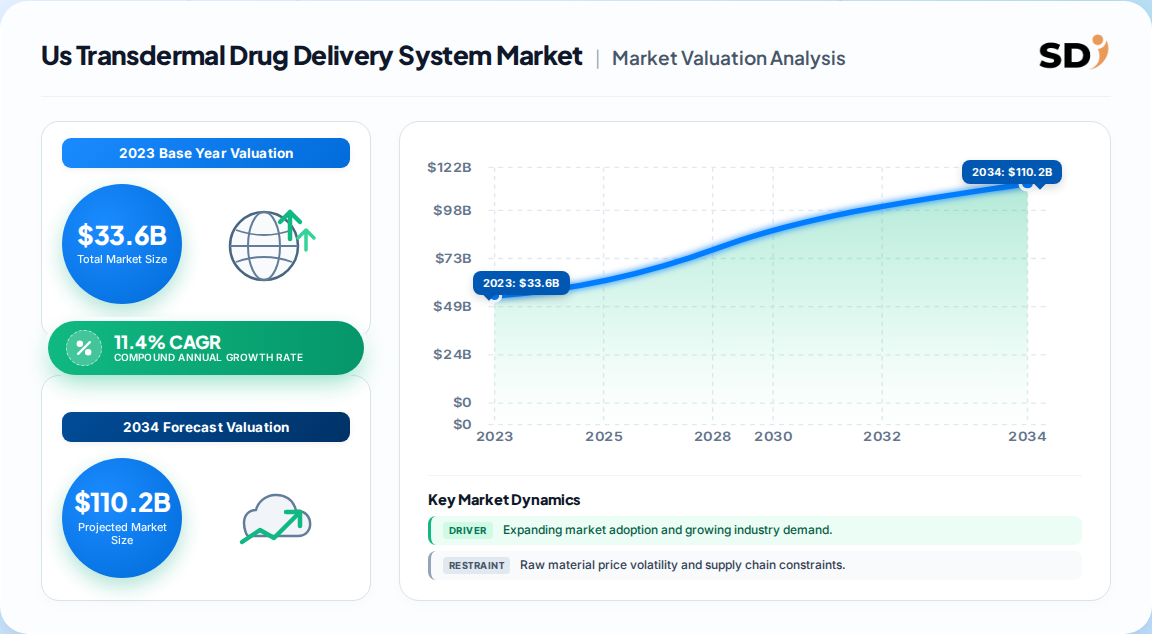
At the narrow U.S. scope, the market was worth USD 33.60 billion in 2023 per one published estimate, with an 11.4% CAGR to USD 71.63 billion by 2030. Broader global definitions report larger figures because they bundle semisolid formulations and all patch types.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 33.60 bn → 71.63 bn | 2023 | 2030 | 11.4% | U.S.-only TDDS revenue | One published estimate |
| USD 34.56 bn → 48.61 bn | 2025 | 2030 | 7.06% | Global TDDS incl. semisolids | A competing analysis |
| USD 73.9 bn → 225.5 bn | 2024 | 2034 | 11.8% | Global TDDS, all technologies | Another published estimate |
The U.S.-specific 11.4% figure is most defensible for U.S. procurement planning. Our analysis suggests global CAGRs of 7% to 12% bracket the true U.S. trajectory; the higher figure assumes rapid microneedle commercialization, while the lower reflects passive-patch saturation.
Segmentation follows three axes: technology, application and end user. Passive systems still dominate volume, while active and microneedle formats drive premium growth and pricing power.
| Parent Segment | Children |
|---|---|
| Technology | Iontophoresis, Mechanical Arrays, Electroporation, Ultrasound, Passive Patches |
| Application | Pain Management, CNS, Cardiovascular, Hormonal, Smoking Cessation, Gastrointestinal |
| Patch Type | Drug-in-Adhesive, Matrix, Reservoir, Microneedle-Based |
| End User | Home-Care, Hospitals, Clinics, Ambulatory Settings |
Our analysis suggests home-care will outgrow hospital use as self-administration normalizes, shifting procurement from institutional buyers to retail pharmacy channels.
Demand concentrates in the South and Northeast, reflecting population density, chronic-disease burden and concentration of pharmaceutical manufacturers and clinical trial sites.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.24% |
| South | 0.31% |
| Midwest | 0.2% |
| West | 0.22% |
| Territories | 0.03% |
Our analysis suggests the South will outgrow other regions through 2030 given its chronic-pain burden and home-care penetration.
Growth is propelled by painless self-administration, chronic-disease burden and platform innovation, offset by skin-permeability limits and regulatory scrutiny of opioid patches.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Chronic disease burden | Driver | High | Steady-state dosing for diabetes, cardiovascular and pain |
| Non-invasive preference | Driver | High | Acceptance above 95% among injection-averse patients |
| Patch design advances | Driver | Medium | Seven-day wear, water-resistant adhesives |
| Wearable/ smart patches | Driver | Medium | Sensor-enabled personalised dosing |
| Skin irritation | Restraint | Medium | Contact dermatitis affects up to 20% of users |
| Molecule-size limits | Restraint | High | Most drugs exceed 600 Daltons for passive diffusion |
| Opioid diversion scrutiny | Restraint | Medium | Regulatory oversight of abuse-deterrent patches |
The balance favors growth: drivers add roughly 6.1 percentage points versus 2.9 points of drag, per published driver-impact modeling. The gap implies a sustained high-single-to-low-double-digit CAGR is achievable.
Leadership splits between large pharmaceutical incumbents with branded patch portfolios and specialized technology firms pushing microneedle and iontophoretic platforms.
| Company | Strategic Position | Differentiator |
|---|---|---|
| Novartis | Pharma incumbent | Acquired Kedalion to strengthen delivery |
| Johnson & Johnson | Broad patch portfolio | Scale and brand trust |
| Viatris | Generics and branded | Cost leadership |
| Boehringer Ingelheim | Chronic-therapy patches | Respiratory and CNS reach |
| Noven Pharmaceuticals | Specialized manufacturer | Transdermal formulation depth |
| Nutriband | Emerging player | Acquired Pocono manufacturing |
| 3M | Materials and adhesives | Adhesive technology moat |
Our analysis suggests M&A is the dominant moat-building strategy; organic microneedle R&D is capital-intensive and slow, favoring acquirers.
Buyers should prioritize adhesion reliability, skin-tolerance profiles and supply continuity. Contact dermatitis in up to 20% of users makes adhesive chemistry a clinical and commercial risk, not a cost line. Switching patch suppliers carries qualification costs tied to FDA labeling and stability data, so multi-year contracts lock in pricing.
Operators must navigate regulatory scrutiny of opioid patches and demonstrate abuse-deterrent design. On the technology side, microneedle and iontophoretic systems add device complexity and cost, so buyers should model total cost of ownership rather than unit price. Home-care delivery channels will increasingly determine commercial reach.
The balance of evidence favors a bullish U.S. outlook, with the 11.4% CAGR to USD 71.63 billion by 2030 as the most credible anchor. The counter-argument is real: molecule-size limits and skin-irritation rates constrain addressable patients, and passive-patch commoditization could compress pricing faster than volume grows.
Our judgment is that platform differentiation, not volume, will decide winners. Microneedle arrays growing above 12.7% CAGR and active systems expanding near 9.6% repricing the market toward premium formats. Vendors anchored only in passive patches face margin compression.
Evidence that would change this conclusion: sustained FDA restrictions on opioid patches, or faster-than-expected erosion of passive-patch pricing, would push the outlook toward the low end of the 7% to 12% CAGR band.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.4% from 2020-2034 |
| Segmentation |
|
The U.S. market was valued at USD 33.60 billion in 2023 per one published estimate and is forecast to reach USD 71.63 billion by 2030, growing at an 11.4% CAGR over the period.
Mechanical arrays, including microneedle technologies, are forecast to grow at over 12.7% CAGR, making them the fastest-growing technology segment through 2030.
Pain management held the largest application share at 22.7% in 2022, driven by chronic pain prevalence, while cardiovascular is the fastest-growing application segment.
Prominent players include Novartis, Johnson & Johnson, Viatris, Boehringer Ingelheim, Noven Pharmaceuticals, Nutriband, 3M and Echo Therapeutics, with M&A a core strategy.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split. In-depth interviews were conducted across the value chain with raw material and adhesive suppliers, specialized transdermal patch producers, contract formulators, and global distributors. Decision-makers interviewed included VP-level sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both technical feasibility and commercial strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Regulatory Affairs Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Adhesive & Polymer Suppliers | 30% |
| Transdermal Patch Manufacturers | 40% |
| Contract Formulators | 20% |
| Distributors & Channel Partners | 10% |
Secondary validation draws on UN Comtrade, WTO and US ITC trade databases, SEC 10-K filings and investor presentations, patent databases, and recognized standards bodies such as the U.S. Pharmacopeia and ISO technical committees. This triangulates proprietary interview data against public filings.
We simultaneously run top-down macroeconomic and segment-allocation models and bottom-up manufacturer capacity, pricing, and end-use consumption models. Divergences are reconciled through elasticity and regression analysis to produce a single defensible base-year and forecast range.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |