 Us Investigational New Drug Cdmo Market
US Investigational New Drug CDMO Market 2026
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 199

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Investigational New Drug Cdmo Market
Amit Mardhekar
Research Analyst

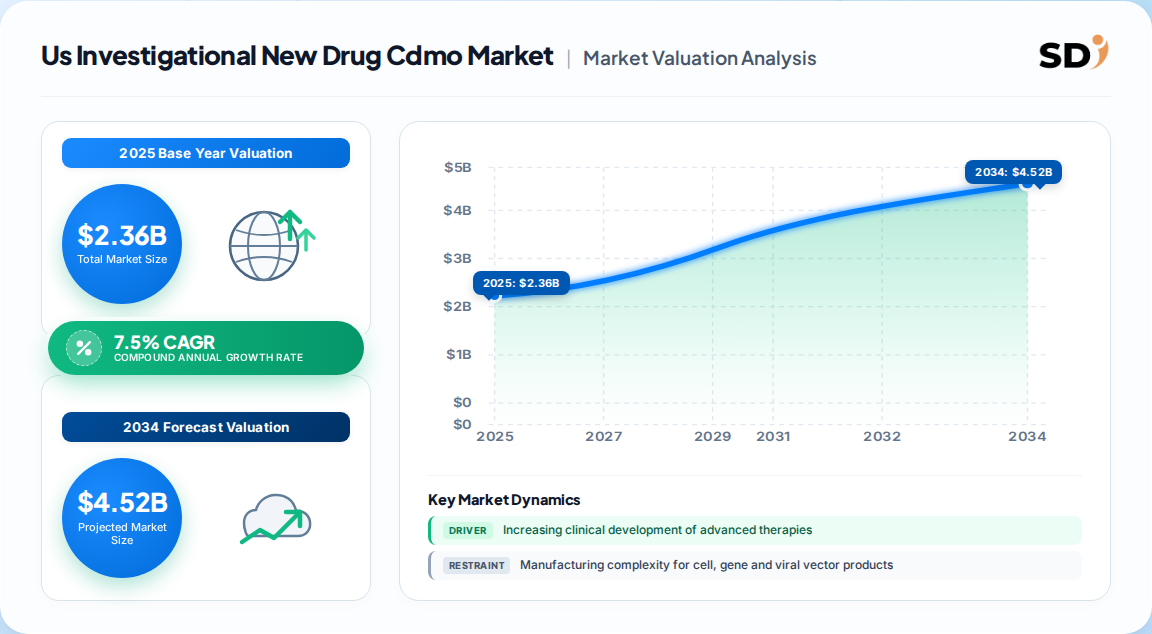
| Year | Market Size |
|---|---|
| 2025 | 2.360 B |
| 2026 | 2.540 B |
| 2027 | 2.730 B |
| 2028 | 2.930 B |
| 2029 | 3.150 B |
| 2030 | 3.390 B |
| 2031 | 3.640 B |

The U.S. IND CDMO market covers outsourced development and clinical-grade manufacturing services that prepare a drug candidate for an Investigational New Drug filing and first-in-human supply. It spans process and analytical development, CMC documentation, drug substance synthesis and GMP drug product manufacturing for Phase I and early-phase programmes.
This analysis covers U.S.-based contract development and manufacturing services tied to IND-enabling stages: preclinical through Phase I, including drug substance, drug product, analytical method development, CMC regulatory support and clinical supply. It spans both service lines (contract development, contract manufacturing) and all molecule types.
This analysis does not cover commercial-scale manufacturing, post-approval lifecycle supply, CRO-only clinical trial management, or non-IND research reagents. It also excludes pure logistics and packaging-only providers, except where they bundle IND-enabling development services.
Published estimates cluster around a U.S. market of roughly USD 2.3–2.4 billion in 2025, with the global IND CDMO sector variously sized at USD 4.7–5.8 billion. Divergence reflects differing treatment of drug product versus drug substance and of discovery-stage work.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 2.36B (U.S.) | 2025 | 2035 | 7.5% | U.S. IND-stage development + clinical manufacturing | Primary benchmark (U.S. outlook) |
| USD 5.5B (global) | 2026 | 2033 | 8.7% | Global IND CDMO, development + manufacturing | One published estimate |
| USD 6.30B (global) | 2026 | 2035 | 7.9% | Global IND CDMO, broader modality inclusion | Competing analysis |
| USD 6.0B (global) | 2026 | 2035 | 6.87% | Global IND CDMO, narrow IND-enabling definition | Alternative published view |
Our analysis suggests the U.S. figure of USD 2.36 billion is the most defensible base, because it aligns with a 41–44% North American share of global revenue and with the density of U.S. venture-backed biotech IND filers. The higher global estimates likely fold in adjacent biologics development work that is not strictly IND-enabling.
Segmentation matters because growth is concentrated in specific lines: advanced therapies and rare-disease programmes are expanding two to three times faster than the small-molecule base. Buyers should weight partner selection toward the fastest-growing segments, not the largest.
| Parent segment | Children | 2025 share / growth signal |
|---|---|---|
| Service | Contract development; contract manufacturing | Manufacturing 54% share; development ~9.2% CAGR |
| Molecule type | Small molecules; large molecules; advanced therapies | Small molecules 48%; advanced therapies ~12.4% CAGR |
| Phase | Preclinical; Phase I; Phase II+ | Phase I 38% share; preclinical ~9.8% CAGR |
| Therapeutic area | Oncology; rare diseases; others | Oncology 44%; rare diseases ~10.6% CAGR |
| End use | Emerging biotechs; pharma; academic institutions | Emerging biotechs 50%; academic ~9.1% CAGR |
The U.S. is not a single market. IND-stage demand clusters around four biotech hubs, and CDMO capacity is following sponsors into these corridors to shorten tech-transfer cycles and reduce supply-chain risk.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.26% |
| Asia-Pacific | 0.24% |
| Latin America | 0.05% |
| Middle East & Africa | 0.04% |
| Parent (U.S.) | Leading sub-regions / hubs |
|---|---|
| Northeast | Boston–Cambridge, New Jersey pharma corridor |
| West Coast | San Francisco Bay Area, San Diego |
| Southeast | Research Triangle (NC), Maryland–Virginia |
| Midwest | Michigan, Ohio, Illinois aseptic capacity |
Our analysis suggests Boston–Cambridge and the Bay Area together account for a disproportionate share of new IND submissions, while Midwest and Southeast sites are absorbing fill-finish and clinical drug product capacity. This geographic mismatch implies sponsors increasingly will trade proximity for capability in sterile fill-finish.
Growth is driven by structural outsourcing from capital-constrained biotechs plus a richer advanced-therapy pipeline; it is constrained by GMP complexity, compliance risk and thin early-phase capacity. Net direction is strongly positive, but margin quality varies sharply by capability.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Advanced therapy clinical development | Driver | High | Viral vector, cell and gene programmes need specialized suites and analytics |
| Outsourcing by emerging biotechs | Driver | High | No in-house GMP; IND timelines compressed |
| Integrated CMC and GMP demand | Driver | High | Fewer handoffs, lower tech-transfer risk |
| Compliance and chain-of-identity complexity | Restraint | Medium-High | Autologous therapies raise operational and regulatory burden |
| Early-phase capacity constraints and pricing pressure | Restraint | Medium | Small-batch suites scarce; sponsors push on price |
| Rare disease and orphan designations | Opportunity | Medium | Fast-track pathways reward speed-to-clinic partners |
The U.S. IND CDMO landscape is semi-consolidated: global CDMOs compete on breadth and regulatory depth, while specialist aseptic and biologics providers compete on speed and small-batch flexibility. Differentiation increasingly hinges on integrated development-to-Phase I capability.
| Vendor | Positioning | Notable capability signal |
|---|---|---|
| Lonza | Global integrated CDMO | Early de-risking partnerships with biotech investors |
| Charles River Laboratories | Development + testing breadth | Integrated CMC and analytical support |
| Labcorp | CRO–CDMO convergence | Clinical and central lab adjacency |
| Recipharm | European + U.S. small molecule / fill-finish | Facility expansion aligned to FDA requirements |
| Syneous Health | Specialist development services | IND-enabling CMC focus |
| Vetter | Aseptic fill-finish | EUR 250M Des Plaines clinical facility (2025) |
| Grand River Aseptic Manufacturing | U.S. sterile fill-finish | USD 100M Michigan expansion (2026) |
Our analysis suggests competitive moats are shifting from reactor capacity toward regulatory documentation depth and modality-specific know-how. Vendors that own the IND submission narrative — not just the batch — will command pricing power.
Partner selection at IND stage is a multi-year commitment, not a transactional purchase. The strongest selection criteria are integrated development-to-Phase I capability under one quality system, demonstrated regulatory documentation depth for first-time filers, and available small-batch GMP capacity within a predictable lead time. Sponsors should scrutinize chain-of-identity controls for autologous therapies and data-integrity practices before contracting.
Procurement risk concentrates in tech-transfer failure and capacity pre-emption. Switching costs rise steeply once analytical methods and process knowledge are embedded with a partner, so early diligence on scalability to Phase II is essential. Regulatory risk is non-trivial: a poorly constructed CMC package can delay an IND filing outright, and remediation costs far exceed any development fee savings.
The balance of evidence favors a capability-led, not capacity-led, view of the U.S. IND CDMO market. Growth of roughly 7.5% is real but slower than global rates, meaning incremental revenue will accrue to vendors with advanced-modality suites, integrated CMC documentation and reliable clinical fill-finish — not to generalist capacity providers.
The strongest counter-argument is that small molecules still represent nearly half of the market and will fund near-term revenue. That is valid, but small-molecule IND work is commoditizing and price-sensitive; our analysis suggests it sustains volume, not margin. The strategic prize sits in advanced therapies and rare-disease programmes, where specialized capacity and regulatory fluency are scarce.
Actionable strategy:
The evidence that would change this conclusion: a sustained downturn in early-stage biotech funding, or FDA-driven simplification of CMC filing requirements, both of which would compress demand for outsourced IND-enabling development.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.5% from 2020-2034 |
| Segmentation |
|
The U.S. IND CDMO market was approximately USD 2.36 billion in 2025, representing the largest national share of a global sector valued at roughly USD 5.4–5.8 billion. It is projected to reach about USD 4.87 billion by 2035 at roughly 7.5% CAGR.
Advanced therapies are the fastest-growing molecule segment at roughly 12.4% CAGR, followed by rare-disease programmes at about 10.6%. Contract development services are growing faster than contract manufacturing as sponsors seek integrated CMC support.
Most early-stage biotechs lack in-house GMP capacity and CMC regulatory expertise. CDMOs provide process development, analytical methods, clinical-grade manufacturing and IND documentation within one quality system, compressing time to first-in-human dosing.
Compliance and tech-transfer risk dominate. Complex modalities such as autologous cell therapies require strict chain-of-identity controls, and a weak CMC package can delay an IND filing outright, making partner diligence on regulatory documentation depth essential.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our 70/30 primary-to-secondary research split anchors this assessment in direct industry engagement. We conducted structured interviews with executives across the IND CDMO value chain, including raw material and specialized input suppliers, contract development organizations, GMP clinical manufacturers, and global distributors serving early-stage sponsors.
Interviewees were selected by decision-making authority: VP-level Sourcing and Procurement leads, Heads of R&D and CMC, Technical Directors, and Commercial Operations Leads. Interviews focused on capacity availability, pricing behaviour, modality-specific bottlenecks and IND submission timelines.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & CMC Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Regulatory Affairs Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Contract Development Organizations | 35% |
| GMP Clinical Manufacturers | 30% |
| Specialty Input & Reagent Suppliers | 20% |
| Analytical & Testing Providers | 15% |
We validated findings against official multilateral and regulatory sources, including UN Comtrade, WTO trade statistics, US ITC data and Eurostat records. Corporate annual filings (10-K, SEC filings and investor presentations) provided capacity and revenue triangulation. Patent databases and recognized technical standards from non-profit industry associations supported the modality and technology assessment.
Market sizing triangulates top-down macroeconomic and industry-segment allocation against bottom-up modelling of manufacturer capacity, batch pricing and end-use consumption. Divergent published estimates were reconciled by normalizing scope definitions before arriving at a consensus base-year valuation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |