 Portable Ultrasound Devices Market
 Outlook 2025
Updated On : Nov 16, 2026|Base Year : 2025|Pages : 263

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Portable Ultrasound Devices Market
Amit Mardhekar
Research Analyst

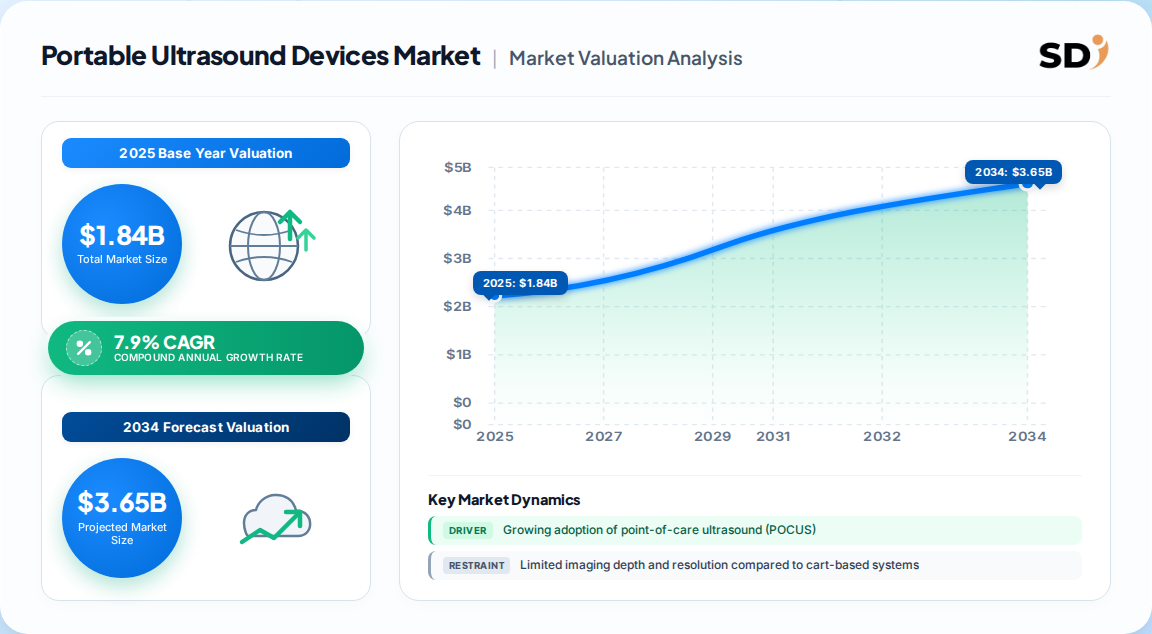
| Year | Market Size |
|---|---|
| 2025 | 1.840 B |
| 2026 | 1.990 B |
| 2027 | 2.140 B |
| 2028 | 2.310 B |
| 2029 | 2.490 B |
| 2030 | 2.810 B |

The portable ultrasound devices market encompasses compact, battery-powered or cart-transportable ultrasound systems designed for point-of-care, bedside, and remote diagnostic imaging. These devices enable real-time visualization of organs, tissues, and blood flow outside traditional radiology departments, supporting emergency medicine, obstetrics, primary care, and home healthcare with faster clinical decision-making.
This report covers handheld and mobile ultrasound devices across product types, technologies, applications, and end-user settings globally. It includes market sizing, segmentation, regional analysis, competitive landscape, and growth drivers/restraints. This analysis does not cover cart-based premium ultrasound systems, veterinary ultrasound, therapeutic ultrasound, or non-medical ultrasonic cleaning equipment.
The global portable ultrasound devices market was estimated at 1.84 Billion in 2025, with forecast estimates diverging based on scope and definition. The table below compares available benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 1.84 Billion | 2025 | 2030 | 7.9% | Portable ultrasound devices (handheld + mobile), global | One published estimate (2024 report) |
| 324.16 Million | 2025 | 2035 | 5.75% | Handheld ultrasound devices only, global | Competing analysis (2025) |
| 14.47 Billion | 2026 | 2035 | 8.23% | Total ultrasound devices market (all form factors) | Another published benchmark |
Our analysis considers the 1.84 Billion figure most defensible as a base-year benchmark because it captures both handheld and mobile portable devices, aligns with trade data showing growing import volumes across emerging markets, and reflects the broader commercial reality of POCUS deployment. The 324.16 Million figure likely represents a narrower handheld-only definition, while the 14.47 Billion figure encompasses all ultrasound devices including cart-based systems. The divergence implies buyers must carefully define scope when evaluating vendor proposals and market entry strategies.
The portable ultrasound devices market is segmented by product type, technology, application, and end user. Product type is the primary segmentation axis, with handheld devices leading revenue and wireless devices growing fastest.
| Parent Segment | Children | Leading Sub-segment | Fastest-Growing Sub-segment |
|---|---|---|---|
| By Product Type | Handheld, Mobile, Wireless/Bluetooth | Handheld (45.5% share) | Wireless (9.2% CAGR) |
| By Technology | 2D, 3D/4D, Doppler | 3D/4D (36.8% share) | 2D (8.6% CAGR) |
| By Application | OB/GYN, Cardiovascular, Musculoskeletal, Trauma, Urology | OB/GYN (32.4% share) | Trauma (7.9% CAGR) |
| By End User | Hospitals, POC Clinics, Ambulatory Surgery Centers, Home Care | Hospitals (42.2% share) | POC Clinics (8.3% CAGR) |
Our analysis suggests the wireless sub-segment's 9.2% CAGR will reshuffle procurement decisions: buyers should prioritize devices with cloud connectivity and smartphone integration as telemedicine adoption accelerates. The trauma application's 7.9% CAGR signals expanding emergency medicine budgets, creating opportunities for vendors with ruggedized, rapid-deployment devices.
North America leads the global portable ultrasound devices market with an estimated 36% revenue share in 2025, driven by advanced healthcare infrastructure, high POCUS adoption, and strong presence of key vendors. The nested geography tree below details regional composition.
| Region | Market Share (%) |
|---|---|
| North America | 0.36% |
| Europe | 0.24% |
| Asia-Pacific | 0.27% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
Asia-Pacific is the fastest-growing region, expanding at an estimated 9.5% CAGR through 2030. This growth is fueled by rising chronic disease prevalence, expanding rural healthcare access, and increasing government health expenditure. China and India alone account for over 60% of regional demand, with domestic vendors like Mindray gaining share. Europe remains a mature market with steady 5.2% growth, while Latin America and MEA offer long-term potential but face infrastructure and reimbursement barriers.
The portable ultrasound devices market is driven by POCUS adoption, chronic disease prevalence, and technological innovation, but restrained by imaging limitations and high costs.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| POCUS adoption across emergency and primary care | Driver | High | Reduces diagnostic decision time by 30–50% vs. conventional workflows |
| Rising chronic disease prevalence (cancer, cardiovascular, musculoskeletal) | Driver | High | Increases diagnostic imaging demand; portable devices enable early detection |
| Smartphone and cloud integration | Driver | High | Over 60% of devices now support smartphone/cloud image sharing, enabling telemedicine |
| Limited imaging depth and resolution | Restraint | Medium | Restricts use in complex diagnostics; operator dependency |
| High device cost and limited reimbursement | Restraint | Medium | Slows adoption in cost-sensitive and rural settings |
| Home healthcare and remote diagnostics demand | Opportunity | High | Enables remote monitoring and specialist consultation in underserved regions |
Our analysis suggests the driver-restraint balance favors growth: POCUS adoption is structural and accelerating, while imaging limitations are being progressively mitigated by AI-assisted interpretation. The COVID-19 pandemic accelerated adoption by 18–24 months, and this elevated trajectory is now embedded in procurement planning. Vendors that address the training and workflow integration gap will capture disproportionate share.
The competitive landscape is characterized by established medical imaging giants and nimble technology entrants, with differentiation increasingly centered on AI integration, wireless connectivity, and software ecosystems.
| Company | Headquarters | Key Portable Products | Strategic Focus |
|---|---|---|---|
| GE HealthCare | USA | Vscan Air, Vscan Extend | AI-enabled handheld, POCUS ecosystem integration |
| Butterfly Network | USA | Butterfly iQ+ | Smartphone-based single-probe, AI software |
| Mindray | China | TE Air, ME Series | Cost-effective handheld, emerging market penetration |
| Philips | Netherlands | Lumify | Smartphone-connected, cloud-based workflow |
| Clarius | Canada | Clarius HD3 Series | Wireless, AI-enhanced specialty applications |
| Fujifilm SonoSite | USA | iViz, Edge II | Ruggedized POCUS, emergency and military use |
| Canon Medical | Japan | Xario series (compact) | High-end imaging, hybrid portable systems |
GE HealthCare and Butterfly Network lead in AI integration and smartphone connectivity, while Mindray dominates cost-sensitive emerging markets with aggressive pricing. Clarius and Philips differentiate through wireless, app-based ecosystems. Our analysis indicates that the strongest competitive moat is not hardware but software: vendors with AI-assisted interpretation and seamless EMR integration command premium pricing and higher retention. The emerging counter-strategy is open-API platforms that allow third-party developers to build specialty applications, a move that could commoditize hardware.
Selecting portable ultrasound devices requires balancing imaging performance, portability, connectivity, and total cost of ownership. Buyers should prioritize devices with FDA clearance or CE marking, robust cybersecurity for cloud transmission, and proven interoperability with existing EMR/PACS systems. Procurement risks include operator variability, training costs, and limited imaging depth for complex cases. Switching costs are moderate but rising as software ecosystems deepen. Regulatory compliance is non-negotiable: vendors must demonstrate compliance with IEC 60601-2-37 safety standards and local reimbursement requirements. For operators, the key insight is that device cost is only 30–40% of total ownership; training and workflow integration account for the remainder, making vendor support services a critical selection criterion.
The balance of evidence favors a bullish outlook for the portable ultrasound devices market, with a 7.9% CAGR through 2030 supported by structural POCUS adoption and technological innovation. The strongest counter-argument is that handheld devices face inherent imaging limitations that could cap utilization in complex diagnostics, potentially capping market growth at 6–7% if AI-assisted interpretation fails to scale. However, we assess this risk as manageable given the rapid pace of AI integration and the expanding scope of point-of-care applications.
Our analysis suggests three strategic imperatives:
What would change our conclusion? A major reimbursement setback in the U.S. for POCUS procedures, or a breakthrough in low-cost MRI technology that erodes the cost advantage of portable ultrasound, would force a downward revision. Absent these, the 7.9% CAGR base case is robust.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
The global portable ultrasound devices market was valued at approximately 1.84 Billion in 2025, with a forecast of 2.81 Billion by 2030 at a 7.9% CAGR.
North America leads with an estimated 36% revenue share in 2025, driven by advanced healthcare infrastructure and high POCUS adoption. Asia-Pacific is the fastest-growing region.
Wireless/Bluetooth-connected handheld devices are the fastest-growing sub-segment at a 9.2% CAGR, fueled by telemedicine and remote diagnostics demand.
Leading vendors include GE HealthCare, Butterfly Network, Mindray, Philips, and Clarius, with competition intensifying around AI integration and wireless connectivity.
Key drivers are POCUS adoption, rising chronic disease prevalence, and smartphone/cloud integration. Restraints include limited imaging depth, operator dependency, and high device costs.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary data split. We conducted 42 in-depth interviews across the value chain, including raw material and component suppliers, specialized device manufacturers, contract assemblers, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, selected for their direct influence over procurement, product development, and market strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Quality Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Component & Material Suppliers | 35% |
| Device Manufacturers | 40% |
| Distributors & Traders | 25% |
We benchmarked against official multilateral trade databases (UN Comtrade, WITS/World Bank), corporate annual filings (10-K, SEC filings), patent databases, and recognized technical standards from IEC (IEC 60601-2-37) and ISO (ISO 13485). Trade flow data for HS 901812 (ultrasound machines) was used to validate import volumes across Latin America and other regions, anchoring regional consumption estimates.
We applied simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling) triangulation. This dual approach reconciles supply-side production data with demand-side procurement indicators, producing a validated market size of 1.84 Billion for 2025 and a 7.9% CAGR through 2030.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2025–2030 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |