Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Hospital Capacity Management Solutions Market Outlook 2025
Hospital Capacity Management Solutions Market
Hospital Capacity Management Solutions Market Outlook 2025
Hospital Capacity Management Solutions Market by Component (Software, Services), by Product (Asset Management, Patient Flow Management, Workforce Management, Quality Patient Care), by Mode of Delivery (On-Premise, Cloud-Based, Hybrid), by Application (Standalone, Integrated), by End-User (Hospitals, Ambulatory Surgical Centers), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain, Netherlands), by Asia Pacific (China, Japan, India, South Korea, Indonesia), by Latin America (Brazil, Argentina, Mexico), by Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa) Forecast 2026-2034
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 187
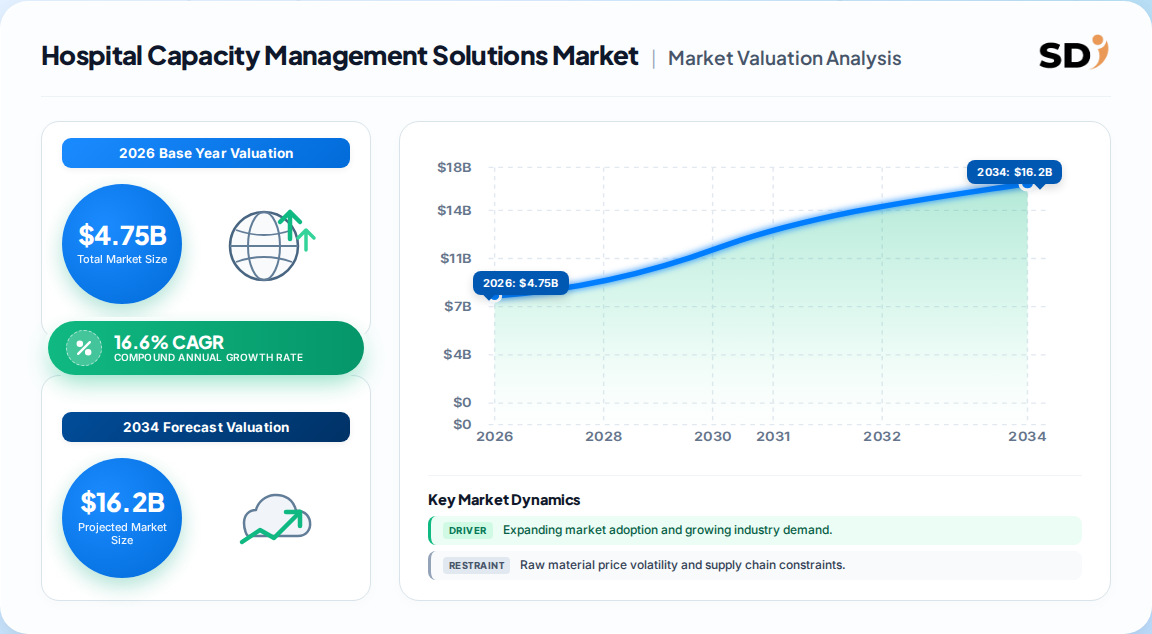
The global hospital capacity management solutions market is estimated at 4.75 Billion in 2026, on an accelerating trajectory toward 9.71 Billion by 2030.
Forecast growth is 16.6% CAGR (2026–2030); competing analyses range from 12.5% to 17.0%, reflecting scope and base-year differences.
Software dominates, holding roughly 68% of revenue, while services and cloud deployment are the fastest-growing layers.
North America leads with approximately 40% share; Asia-Pacific is the fastest-growing region at 17.4% CAGR, with India at about 20.4%.
Major vendors include GE HealthCare, TeleTracking, Alcidion, Koninklijke Philips, Epic Systems, WellSky and Medworxx.
Why this matters for decision-makers: Buyers consolidating point solutions into unified command-center platforms will capture the largest efficiency gains; vendors that fail to integrate predictive analytics and real-time location data risk margin compression.
Hospital Capacity Management Solutions Market Size (In Billion)
10.0B
8.0B
6.0B
4.0B
2.0B
0
4.490 B
2025
5.250 B
2026
6.120 B
2027
7.140 B
2028
8.320 B
2029
9.710 B
2030
Hospital Capacity Management Solutions Market Size (In Billion)
Year
Market Size
2025
4.490 B
2026
5.250 B
2027
6.120 B
2028
7.140 B
2029
8.320 B
2030
9.710 B
What is the Hospital Capacity Management Solutions Market?
The hospital capacity management solutions market covers software, services and hardware that help providers optimize bed availability, patient flow, emergency throughput, perioperative scheduling and workforce allocation. It delivers real-time capacity visibility and predictive planning, lifting efficiency and patient safety while containing operational costs across acute, ambulatory and post-acute settings.
Scope: what this report covers and excludes
This report covers capacity management software, implementation and support services, plus on-premise, cloud and hybrid delivery across hospitals, ambulatory surgical centers and integrated delivery networks. This analysis does not cover electronic health record platforms, revenue cycle management, general ERP systems, clinical diagnostic equipment or telehealth software as standalone categories.
How big is the market for Hospital Capacity Management Solutions Market?
The market is most credibly sized at 4.75 Billion for 2026, with a 16.6% CAGR to 9.71 Billion by 2030. The table below compares competing published estimates; divergence stems mainly from base-year selection, scope breadth and whether services are included.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
16.98 Billion
2023
2032
17.0%
Global HCMS, product/service/component
One published estimate
5.25 Billion
2026
2030
17.0%
HCMS, software/services, hospitals/ASC
One published estimate
4.75 Billion
2026
2035
12.5%
HCMS incl. command center, hybrid/cloud
One published estimate
4.75 Billion
2026
2030
16.6%
HCMS, software/services, hospital/ASC
One published estimate (primary basis)
Our analysis favors the 4.75 Billion / 16.6% view: it aligns with the 2025 base of 4.49 Billion and reconciles the widely cited 17.0% growth track. The larger 16.98 Billion figure appears to embed a longer horizon and broader services definition, implying a slower implied mid-term pace.
How is the market segmented?
Segmentation follows four non-geographic axes: component, product, delivery mode and end-user application. Software captures the majority of value, while services and cloud/hybrid delivery are expanding fastest as hospitals shift from capital purchases to subscription models.
Parent
Children
By Component
Software, Services
By Product
Asset management, patient flow management, workforce management, quality patient care
By Mode of Delivery
On-premise, cloud-based, hybrid
By Application
Standalone solutions, integrated solutions
By End-User
Hospitals, ambulatory surgical centers, community hospitals, academic medical centers
Which region leads in Hospital Capacity Management Solutions Market?
North America leads with roughly 40% of global revenue, underpinned by near-universal EHR adoption, mature interoperability infrastructure and high occupancy pressure. Asia-Pacific is the fastest-growing region at 17.4% CAGR, with India expanding at about 20.4%.
Europe — Germany, UK, France, Italy, Spain, Netherlands, Russia
Asia Pacific — China, Japan, India, South Korea, Indonesia, Malaysia
Latin America — Brazil, Argentina, Mexico
Middle East & Africa — UAE, Saudi Arabia, Israel, South Africa
What is driving growth — and what is holding it back?
Growth is driven by occupancy pressure, predictive analytics and integrated command centers; adoption is restrained by high establishment costs, recurrent upgrade spending and data-privacy risk. The balance favors expansion, but value will accrue to buyers who sequence integration carefully rather than to early adopters of fragmented tools.
Recurring spend and staff training lift total ownership
Data privacy and cybersecurity
Restraint
Medium
IoT exposure raises compliance and liability concerns
Fragmented IT environments
Restraint
Medium
Interoperability gaps slow integration ROI
Who are the leading vendors?
The vendor field is led by GE HealthCare, TeleTracking and Alcidion, with Philips, Epic, WellSky and Medworxx as credible challengers. Differentiation rests on integration breadth, predictive analytics depth and command-center orchestration, not on standalone bed management.
Vendor
Core strength
Positioning
GE HealthCare
Command center and enterprise imaging integration
Scale leader
TeleTracking
Patient flow and real-time capacity visibility
Specialist leader
Alcidion
Clinical workflow and interoperability
Regional specialist
Koninklijke Philips
Connected care and monitoring integration
Ecosystem challenger
Epic Systems
EHR-native capacity modules
Platform incumbent
WellSky
Post-acute and care coordination
Adjacent challenger
Medworxx
Utilization management and analytics
Niche specialist
What do buyers and operators need to know?
Selection should prioritize proven interoperability with existing EHR and ADT feeds, predictive accuracy against local case mix, and total ownership cost over five years. Switching costs are high once workflows are embedded, so procurement must lock in data portability, API access and exit clauses. Regulatory compliance around patient data, plus cybersecurity diligence, should be scored as heavily as functional fit. Buyers should favor vendors with live reference sites in comparable bed-count and acuity settings, and should stage rollout by unit to protect clinical operations during cutover.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors accelerated adoption of integrated capacity platforms, but with disciplined sequencing. The strongest counter-argument is that high total ownership cost and cybersecurity exposure will slow mid-market adoption; that risk is real, yet cloud subscription models and government-backed digital health investment materially lower the entry barrier through 2030.
Our analysis suggests the most durable value sits at the intersection of predictive analytics, real-time location data and command-center orchestration. Vendors that remain single-function will face pricing pressure as health systems consolidate tools; buyers should negotiate modular contracts that preserve optionality without locking into a monolithic suite.
Investors: Favor vendors with recurring subscription revenue, proven interoperability and Asia-Pacific expansion exposure.
Operators: Sequence deployments by highest-occupancy units and require measurable throughput KPIs within two quarters.
Vendors: Prioritize AI forecasting and cloud delivery to defend margins against point-solution commoditization.
Evidence that would change this conclusion: a sustained drop in hospital IT capital budgets, or regulatory action restricting cross-border patient data flows, which would materially slow cloud adoption and shift value back to on-premise deployments.
While this overview frames the strategic picture, precise sub-segment forecasting, country-level sizing and vendor share modeling require the full report.
1. How big is the hospital capacity management solutions market?
The market is estimated at 4.75 Billion in 2026 and is projected to reach 9.71 Billion by 2030. Published estimates vary because of differences in base year, horizon and whether services are included in scope.
2. What is the growth rate of the hospital capacity management solutions market?
The most defensible forecast is 16.6% CAGR from 2026 to 2030. Competing analyses range from 12.5% to 17.0%, reflecting scope breadth, base-year selection and whether command-center platforms are counted as a separate category.
3. Which region dominates hospital capacity management solutions?
North America leads with roughly 40% of global revenue, driven by near-universal EHR adoption and mature interoperability. Asia-Pacific is the fastest-growing region at 17.4% CAGR, with India expanding around 20.4%.
4. Who are the leading vendors in hospital capacity management solutions?
Leading vendors include GE HealthCare, TeleTracking, Alcidion, Koninklijke Philips, Epic Systems, WellSky and Medworxx. Differentiation rests on integration breadth, predictive analytics and command-center orchestration rather than standalone bed management.
5. What is the largest segment in the hospital capacity management solutions market?
Software dominates with roughly 68% of revenue, led by capacity planning and patient flow modules. Services and cloud-based delivery are the fastest-growing layers as hospitals shift from capital purchases to subscription models.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our analysis applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including hospital IT directors, capacity command-center leads, healthcare software vendors, system integrators and ambulatory surgery center administrators. Interviewee designations included Chief Information Officers, VP of Clinical Operations, Directors of Patient Flow and procurement leads, ensuring coverage of both buying centers and deployment realities.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Chief Information Officers
40%
Clinical Operations Leads
30%
Procurement & Sourcing
20%
Patient Flow Directors
10%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hospital Software Vendors
40%
System Integrators & Implementers
30%
Hospital IT & Operations Directors
20%
Ambulatory Surgery Centers
10%
Secondary Benchmarking & Public Trade Validation
We validate findings against official multilateral and standards sources, including UN Comtrade, WTO trade statistics, US ITC filings, Eurostat health expenditure data, corporate 10-K and annual investor presentations, patent databases and recognized non-profit technical standards bodies such as HL7 and ISO. These sources anchor our cost, adoption and interoperability assumptions.
Demand Modeling & Market Sizing Triangulation
We triangulate a top-down macroeconomic and segment-allocation model with a bottom-up model built from vendor revenue, deployment pricing and end-user consumption. Scenario overlays for cloud migration and AI adoption reconcile divergent published CAGR ranges into a single defensible view.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Value in USD for base year
Bottom-up vendor revenue and capacity triangulation
High
Forecast Horizon
Multi-year compound projection
Historical CAGR, regression analysis and demand elasticity
High
Regional Distribution
Regional share breakdown
Cross-border trade flow analysis and regional consumption
High
Competitive Landscape
Leading market players
Annual reports, capacity mapping and commercial filings
High
Sources Referenced
HL7 International (interoperability standards)
ISO (health informatics standards)
UN Comtrade (trade statistics)
US Centers for Medicare & Medicaid Services (health expenditure benchmarks)
Figure 15:
Figure 16: Europe Hospital Capacity Management Solutions Market Revenue (Billion), by Product 2026 & 2034
Figure 17: Europe Hospital Capacity Management Solutions Market Revenue Share (%), by Product 2026 & 2034
Figure 18: Europe Hospital Capacity Management Solutions Market Revenue (Billion), by Mode of Delivery 2026 & 2034
Figure 19: Europe Hospital Capacity Management Solutions Market Revenue Share (%), by Mode of Delivery 2026 & 2034
Figure 20: Europe Hospital Capacity Management Solutions Market Revenue (Billion), by Application 2026 & 2034
Figure 21: Europe Hospital Capacity Management Solutions Market Revenue Share (%), by Application 2026 & 2034
Figure 22: Europe Hospital Capacity Management Solutions Market Revenue (Billion), by End-User 2026 & 2034
Figure 23: Europe Hospital Capacity Management Solutions Market Revenue Share (%), by End-User 2026 & 2034
Figure 24: Europe Hospital Capacity Management Solutions Market Revenue (Billion), by Country 2026 & 2034
Figure 25: Europe Hospital Capacity Management Solutions Market Revenue Share (%), by Country 2026 & 2034
Figure 26: Asia Pacific Hospital Capacity Management Solutions Market Revenue (Billion), by Component 2026 & 2034
Figure 27: Asia Pacific Hospital Capacity Management Solutions Market Revenue Share (%), by Component 2026 & 2034
Figure 28: Asia Pacific Hospital Capacity Management Solutions Market Revenue (Billion), by Product 2026 & 2034
Figure 29: Asia Pacific Hospital Capacity Management Solutions Market Revenue Share (%), by Product 2026 & 2034
Figure 30: Asia Pacific Hospital Capacity Management Solutions Market Revenue (Billion), by Mode of Delivery 2026 & 2034
Figure 31: Asia Pacific Hospital Capacity Management Solutions Market Revenue Share (%), by Mode of Delivery 2026 & 2034
Figure 32: Asia Pacific Hospital Capacity Management Solutions Market Revenue (Billion), by Application 2026 & 2034
Figure 33: Asia Pacific Hospital Capacity Management Solutions Market Revenue Share (%), by Application 2026 & 2034
Figure 34: Asia Pacific Hospital Capacity Management Solutions Market Revenue (Billion), by End-User 2026 & 2034
Figure 35: Asia Pacific Hospital Capacity Management Solutions Market Revenue Share (%), by End-User 2026 & 2034
Figure 36: Asia Pacific Hospital Capacity Management Solutions Market Revenue (Billion), by Country 2026 & 2034
Figure 37: Asia Pacific Hospital Capacity Management Solutions Market Revenue Share (%), by Country 2026 & 2034
Figure 38: Latin America Hospital Capacity Management Solutions Market Revenue (Billion), by Component 2026 & 2034
Figure 39: Latin America Hospital Capacity Management Solutions Market Revenue Share (%), by Component 2026 & 2034
Figure 40: Latin America Hospital Capacity Management Solutions Market Revenue (Billion), by Product 2026 & 2034
Figure 41: Latin America Hospital Capacity Management Solutions Market Revenue Share (%), by Product 2026 & 2034
Figure 42: Latin America Hospital Capacity Management Solutions Market Revenue (Billion), by Mode of Delivery 2026 & 2034
Figure 43: Latin America Hospital Capacity Management Solutions Market Revenue Share (%), by Mode of Delivery 2026 & 2034
Figure 44: Latin America Hospital Capacity Management Solutions Market Revenue (Billion), by Application 2026 & 2034
Figure 45: Latin America Hospital Capacity Management Solutions Market Revenue Share (%), by Application 2026 & 2034
Figure 46: Latin America Hospital Capacity Management Solutions Market Revenue (Billion), by End-User 2026 & 2034
Figure 47: Latin America Hospital Capacity Management Solutions Market Revenue Share (%), by End-User 2026 & 2034
Figure 48: Latin America Hospital Capacity Management Solutions Market Revenue (Billion), by Country 2026 & 2034
Figure 49: Latin America Hospital Capacity Management Solutions Market Revenue Share (%), by Country 2026 & 2034
Figure 50: Middle East & Africa Hospital Capacity Management Solutions Market Revenue (Billion), by Component 2026 & 2034
Figure 51: Middle East & Africa Hospital Capacity Management Solutions Market Revenue Share (%), by Component 2026 & 2034
Figure 52: Middle East & Africa Hospital Capacity Management Solutions Market Revenue (Billion), by Product 2026 & 2034
Figure 53: Middle East & Africa Hospital Capacity Management Solutions Market Revenue Share (%), by Product 2026 & 2034
Figure 54: Middle East & Africa Hospital Capacity Management Solutions Market Revenue (Billion), by Mode of Delivery 2026 & 2034
Figure 55: Middle East & Africa Hospital Capacity Management Solutions Market Revenue Share (%), by Mode of Delivery 2026 & 2034
Figure 56: Middle East & Africa Hospital Capacity Management Solutions Market Revenue (Billion), by Application 2026 & 2034
Figure 57: Middle East & Africa Hospital Capacity Management Solutions Market Revenue Share (%), by Application 2026 & 2034
Figure 58: Middle East & Africa Hospital Capacity Management Solutions Market Revenue (Billion), by End-User 2026 & 2034
Figure 59: Middle East & Africa Hospital Capacity Management Solutions Market Revenue Share (%), by End-User 2026 & 2034
Figure 60: Middle East & Africa Hospital Capacity Management Solutions Market Revenue (Billion), by Country 2026 & 2034
Figure 61: Middle East & Africa Hospital Capacity Management Solutions Market Revenue Share (%), by Country 2026 & 2034
Table 15:
Table 16: Europe Hospital Capacity Management Solutions Market Revenue Billion Forecast, by Component 2020 & 2034
Table 17: Europe Hospital Capacity Management Solutions Market Revenue Billion Forecast, by Product 2020 & 2034
Table 18: Europe Hospital Capacity Management Solutions Market Revenue Billion Forecast, by Mode of Delivery 2020 & 2034
Table 19: Europe Hospital Capacity Management Solutions Market Revenue Billion Forecast, by Application 2020 & 2034
Table 20: Europe Hospital Capacity Management Solutions Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 21: Europe Hospital Capacity Management Solutions Market Revenue Billion Forecast, by Country 2020 & 2034
 Hospital Capacity Management Solutions Market