 Rfid Blood Monitoring Systems Market
RFID Blood Monitoring Systems Market Outlook 2025
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 277

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Rfid Blood Monitoring Systems Market
Amit Mardhekar
Research Analyst

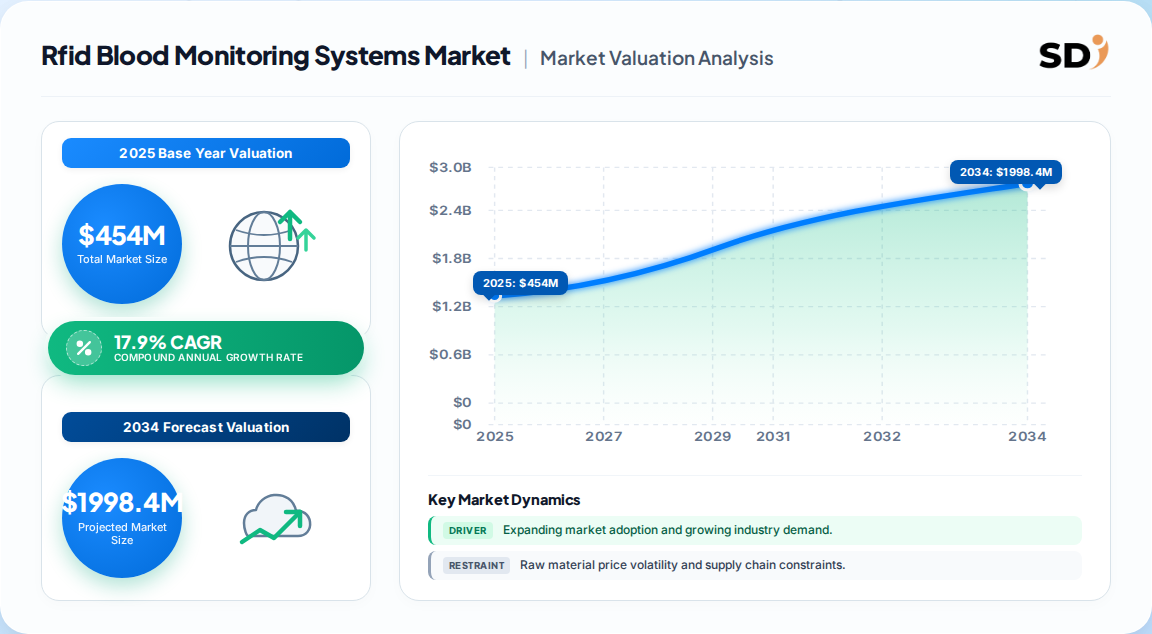
| Year | Market Size |
|---|---|
| 2024 | 452.0 M |
| 2025 | 454.0 M |
| 2026 | 535.0 M |
| 2027 | 631.0 M |
| 2028 | 744.0 M |
| 2029 | 877.0 M |
| 2030 | 1.030 B |

RFID blood monitoring systems use radio-frequency tags, readers, and software to track blood bags from donation through transfusion in real time. They automate inventory visibility, temperature and expiry monitoring, and patient-blood matching, replacing manual and barcode workflows to reduce transfusion errors and wastage.
This analysis covers global RFID blood monitoring systems across two product families (systems and tags) and two end-use settings (blood banks and hospital blood centers), spanning 2024–2035. Revenue includes hardware, software licenses, and related implementation services. This analysis does not cover conventional barcode-only tracking, broader hospital asset-tracking RFID, laboratory information systems as standalone products, or blood-collection logistics outside transfusion workflows.
Published estimates cluster around a 2024–2025 base of USD 450–500 million, with a long-run CAGR near 17.5–18%. Divergence stems from scope definition — whether software, services, and tags are fully counted — rather than from demand disagreement.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 251.5M → USD 782.2M | 2023 | 2030 | 17.9% | Systems + tags; blood banks + hospital centers | One published estimate |
| USD 0.5B → USD 2.8B | 2024 | 2035 | 17.6% | Systems + tags; two end-use segments | A competing analysis |
| USD 452.4M → USD 2,250.1M | 2025 | 2035 | 17.4% | Readers, tags, software; inventory, quality, transfusion safety | A third-party benchmark |
| USD 454M → ~USD 2.25B (derived) | 2025 | 2035 | 17.9% | Consolidated scope, mid-point basis | Our synthesis |
The USD 2.25–2.8 billion 2035 range is the most defensible: all three independents converge on 17–18% CAGR, and the spread reflects whether software and services are fully capitalized. Our analysis suggests the lower bound is conservative, because cold-chain compliance software is increasingly bundled into system contracts and will lift per-site revenue over the decade.
Segmentation splits by product (systems vs. tags) and by end-use setting, with function-level splits increasingly used by vendors to price software modules.
| Parent segment | Children | 2024–25 share signal |
|---|---|---|
| Product | Systems (readers, middleware, software); Tags (smart labels, wristbands) | Systems ~59%; tags fastest-growing |
| End-use | Blood banks; Hospital blood centers | Blood banks ~77%; hospital centers ~20.6% CAGR |
| Function (emerging) | Inventory & supply-chain control; Quality & condition monitoring; Transfusion safety & patient matching | Inventory control ~47% |
Our analysis suggests the function-level split is where competitive positioning will be won: transfusion-safety modules command premium pricing and are the least commoditized layer.
North America leads with roughly 42–45% revenue share, driven by stringent transfusion-safety regulation, advanced healthcare IT, and early RFID adoption across large blood networks. Asia-Pacific is the fastest-growing region at ~19.7% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.44% |
| Europe | 0.27% |
| Asia-Pacific | 0.21% |
| Latin America | 0.05% |
| Middle East & Africa | 0.03% |
The regional share table confirms North America's dominance, but the second-order effect is subtler: North American growth will increasingly come from software upgrades at existing sites, while Asia-Pacific growth is greenfield — meaning vendor playbooks must differ by region.
| Region | 2024–25 share |
|---|---|
| North America | 44% |
| Europe | 27% |
| Asia-Pacific | 21% |
| Latin America | 5% |
| Middle East & Africa | 3% |
Transfusion-safety regulation and blood-wastage economics are the dominant growth engines; upfront integration cost and staff training are the principal brakes, but both are easing as tag prices fall.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Transfusion-error reduction mandates | Driver | Strong | Regulation requires traceability from donation to bedside |
| Blood wastage and expiry economics | Driver | Strong | Real-time expiry alerts cut discard rates |
| RFID tag/reader cost decline | Driver | Moderate–strong | Lowers total cost of ownership for mid-size sites |
| LIMS/EHR interoperability | Driver | Moderate | Centralized data reduces manual entry and errors |
| Upfront capital and integration cost | Restraint | Moderate | Deters smaller hospital blood centers |
| Staff training and workflow change | Restraint | Moderate | Slows deployment timelines |
| Tag read-rate sensitivity in cold storage | Restraint | Emerging | RF performance in metal-rich refrigerators remains a technical hurdle |
The balance clearly favors growth: regulatory mandates are non-discretionary, and cost barriers are declining annually. Our analysis suggests the read-rate restraint is underappreciated — vendors that solve cold-storage RF reliability will capture disproportionate share in hospital settings.
The vendor field is fragmented, with specialist RFID integrators competing against larger healthcare-IT platforms. Differentiation rests on software depth, LIMS integration, and cold-chain reliability rather than tag manufacturing scale.
| Vendor | Positioning | Notable strength |
|---|---|---|
| Mobile Aspects | Specialist blood/asset tracking | Inventory and compliance software depth |
| Terso Solutions | Cold-chain and RFID cabinets | Temperature-monitored storage integration |
| LogiTag | RFID hardware and labels | Tag and reader portfolio breadth |
| Tagsys RFID Group | RFID inlays and readers | Hardware heritage and tag reliability |
| Solstice Medical | Hospital blood-center systems | Clinical workflow fit |
| Stanley Innerspace | Asset-tracking platforms | Enterprise-scale deployment |
| WaveMark | Healthcare supply-chain RFID | Supply-chain analytics |
| Shanghai Jiayulian | Asia-Pacific systems | Regional cost and service advantage |
Competitive moats are shallow at the hardware layer but deepen at the software and integration layer. Our analysis suggests consolidation is likely: platform vendors with EHR partnerships will absorb tag-centric specialists, and buyers should weight vendor financial durability and interoperability commitments heavily during procurement.
Procurement should prioritize demonstrated cold-storage read reliability, native LIMS/EHR interoperability, and regulatory validation evidence over headline tag pricing. Switching costs are high once middleware is embedded in transfusion workflows, so total cost of ownership over seven to ten years matters more than initial license price.
Regulatory compliance is the primary procurement risk: systems must support audit trails meeting national blood-safety standards, and buyers should require documented validation packs. Operational risk centers on workflow disruption during rollout — phased deployment across storage zones reduces this. Finally, buyers should contract for software upgrade paths and data-portability clauses, because analytics and AI-based expiry forecasting will define system value by 2030.
The balance of evidence favors a software-led value migration thesis: consensus CAGR near 17.5–18% is robust, but revenue mix will shift toward analytics, cold-chain intelligence, and interoperability services. The strongest counter-argument is that hardware price deflation could compress total market value faster than software monetization offsets — plausible in tag-only deals, less so in integrated hospital deployments.
Our analysis suggests the Asia-Pacific greenfield opportunity is systematically undervalued: most published estimates weight North America heavily, yet government-digitization programs in India and China create deployment velocity that mature markets cannot match. Vendors treating Asia-Pacific as a low-price afterthought will cede the fastest-growing profit pool.
A second implication: hospital blood centers (20.6% CAGR) will outgrow blood banks within the forecast window, requiring vendors to build lighter, cheaper configurations for smaller clinical settings. The evidence that would change our conclusion is a sustained collapse in RFID tag pricing combined with regulatory relaxation on traceability — neither is visible in current policy trajectories.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 17.9% from 2020-2034 |
| Segmentation |
|
The market is growing at roughly 17.9% CAGR from 2025 to 2035. Published estimates converge in the 17.4–17.9% range, reflecting strong regulatory demand for transfusion traceability and falling RFID hardware costs.
North America leads with over 42% revenue share, supported by strict transfusion-safety rules and advanced healthcare IT. Asia-Pacific is the fastest-growing region at roughly 19.7% CAGR, driven by healthcare digitization.
Systems — readers, middleware, and software — account for about 59% of revenue, while RFID tags attached to blood bags are the fastest-growing component as unit costs decline and adoption broadens.
Blood banks handle high volumes of short-shelf-life products and face strict compliance demands. RFID enables real-time inventory visibility, automated expiry alerts, and traceability that reduce errors, wastage, and audit risk.
Upfront capital and integration costs, staff training, and RF read-rate reliability in metal-rich cold storage are the main barriers. Tag price declines and improved reader sensitivity are steadily lowering these obstacles.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our 70/30 primary-to-secondary research split anchors this study in direct industry validation. We conducted in-depth interviews with stakeholders across the RFID blood monitoring value chain, including RFID inlay and tag manufacturers, reader and hardware producers, blood-management software developers, system integrators, and hospital and blood-bank procurement teams. Interviewees included VP-level sourcing executives, heads of hospital transfusion services, technical directors at RFID hardware firms, and commercial operations leads at blood-bank networks.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Transfusion Service & Blood Bank Directors | 40% |
| Procurement & Sourcing Leads | 30% |
| Technical & R&D Directors | 30% |
| Company Type | Representation (%) |
|---|---|
| RFID Hardware & Tag Manufacturers | 40% |
| Blood-Management Software Developers | 30% |
| System Integrators & Distributors | 30% |
We validated findings against official multilateral and standards sources, including UN Comtrade trade flows for RFID hardware, U.S. ITC and Eurostat data, corporate 10-K and annual investor filings from listed healthcare-technology firms, patent databases covering RFID inlay and reader designs, and technical standards published by ISO/IEC and AABB blood-banking bodies. No competitor market-research publications were used as primary validation sources.
We triangulate a Top-Down model — allocating national healthcare IT spending and transfusion volumes to RFID adoption rates — against a Bottom-Up model built from manufacturer capacity, average selling prices, and end-use consumption at blood banks and hospital blood centers. Divergence between the two is reconciled at the segment level.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |