 Powered Surgical Instruments Market
: Global Outlook 2025
Updated On : Nov 19, 2026|Base Year : 2025|Pages : 250

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Powered Surgical Instruments Market
Amit Mardhekar
Research Analyst

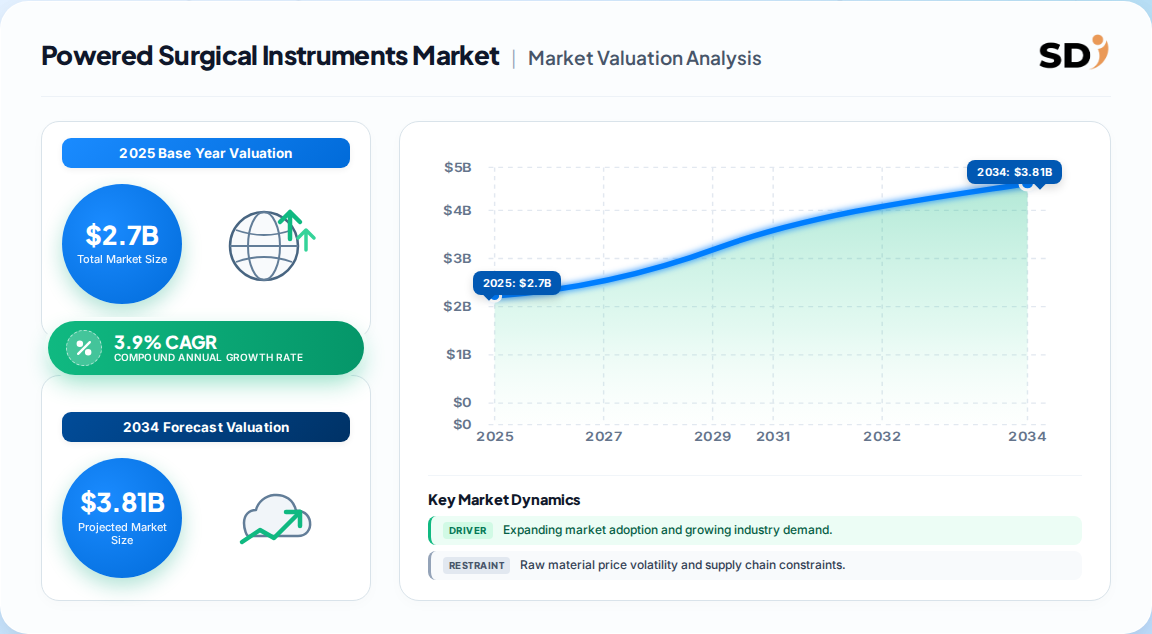
| Year | Market Size |
|---|---|
| 2025 | 2.700 B |
| 2026 | 2.810 B |
| 2027 | 2.920 B |
| 2028 | 3.030 B |
| 2029 | 3.150 B |
| 2030 | 3.270 B |
| 2031 | 3.400 B |

The powered surgical instruments market comprises electrically or pneumatically driven surgical tools — drills, saws, reamers, staplers, and shavers — used to cut, shape, or remove bone and tissue with precision. These devices replace manual effort in orthopedics, neurosurgery, ENT, and cardiothoracic procedures, improving operative speed, accuracy, and surgeon ergonomics across hospital and ambulatory settings.
This report covers global powered surgical instruments across product type (handpieces and accessories), power source (wired-electric, battery-powered), application (orthopedic, neurosurgery, ENT, cardiovascular, plastic, and others), and end-user (hospitals, ASCs, specialty clinics). It addresses market sizing, segmentation, regional dynamics, vendor positioning, and procurement considerations. This analysis does not cover manual surgical instruments, robotic surgical systems as a standalone category, electrosurgical generators, or single-use disposable-only instrument segments.
The global powered surgical instruments market was valued at approximately USD 2.7 billion in 2025, with forecasts converging on USD 3.4–3.7 billion by 2032–2033 at a 3.9% CAGR. Competing estimates differ mainly on base-year inclusion of accessories, power consoles, and battery aftermarket revenue.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.6B | 2023 | 2032 | 4.0% | Handpieces + accessories, global | One published estimate (GMI) |
| USD 2.37B | 2026 | 2031 | 3.88% | Handpieces, wired + battery, global | A competing analysis (Mordor) |
| USD 2.7B | 2025 | 2033 | 2.7% | Product, power source, accessories | A competing analysis (GVR) |
Our analysis suggests the USD 2.7B (2025) base is most defensible for buyer benchmarking because it reconciles handpiece ASPs with installed-base servicing and accessory pull-through. The 2.7% figure likely under-weights battery replacement cycles; the 4.0% figure may over-count consumable accessories. The consensus mid-point of 3.9% CAGR is the appropriate planning anchor.
Segmentation follows four non-geographic axes: product type, power source, application, and end-user. Handpieces and orthopedic applications anchor revenue today, while battery-powered systems and ASC end-users represent the fastest-growing wedges.
| Parent | Children |
|---|---|
| Product Type | Handpieces (drills, reamers, saws, staplers, shavers, other), Accessories (surgical, electrical) |
| Power Source | Wired-Electric, Battery-Powered (Li-Ion, NiMH), Pneumatic |
| Application | Orthopedic & Trauma, Neurosurgery, ENT Surgery, Cardiovascular, Plastic & Reconstructive, Other |
| End-User | Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Academic Institutions |
Handpieces held ~60% share in 2025 but accessories are compounding at ~5.0% CAGR — a signal that vendors should treat consumables as a strategic profit pool, not a footnote.
North America leads the powered surgical instruments market with roughly 35–43% revenue share in 2025, driven by high surgical volumes, premium reimbursement, and rapid ASC adoption. Asia-Pacific is the fastest-growing region at ~5.2% CAGR, reflecting infrastructure build-out and rising procedure penetration.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.24% |
| Asia-Pacific | 0.26% |
| Latin America | 0.08% |
| Middle East & Africa | 0.07% |
| Region | 2025 Share | Growth Outlook |
|---|---|---|
| North America | ~35% | Steady, ASC-led |
| Europe | ~24% | Moderate, day-surgery shift |
| Asia-Pacific | ~26% | Fastest (5.2% CAGR) |
| Latin America | ~8% | Emerging, price-sensitive |
| Middle East & Africa | ~7% | Infrastructure-led |
The divergence between North America's revenue dominance and APAC's growth trajectory implies vendors should run dual playbooks: defend premium installed base in the West while localizing mid-tier systems for APAC and MEA tenders.
Growth is anchored by rising surgical procedure volume (~234 million major operations annually per WHO), an aging population (1 in 6 people over 65 by 2050 per UN), and MIS adoption (~70% of surgeries). Restraints center on high capital and maintenance costs, regulatory burden, and a shortage of trained surgical staff.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising surgical & trauma volume | +1.2% CAGR | High (WHO data) | Higher OR throughput → instrument demand |
| Aging population / degenerative disease | +0.8% CAGR | High (UN demography) | Joint replacement & spine volumes |
| Technological advancement (battery, smart consoles) | +0.7% CAGR | Medium-High | Premium mix & replacement cycles |
| MIS & outpatient shift | +0.6% CAGR | High | ASC expansion → portable battery tools |
| High capital & maintenance costs | –0.9% CAGR | Medium | Budget constraints in LMICs & small ASCs |
| Skilled professional shortage | –0.5% CAGR | Medium | Slower adoption in emerging markets |
The net balance favors growth, but the –0.9% cost drag is decisive in price-sensitive geographies. Vendors that fail to offer financing, refurbishment, or service-bundled pricing will cede share in Latin America and MEA.
The competitive field is moderately concentrated, with the top five vendors controlling an estimated 55–60% of global revenue. Differentiation rests on handpiece ergonomics, battery ecosystem lock-in, robotic/OR integration, and service network depth.
| Company | HQ | Core Strength | Strategic Moat |
|---|---|---|---|
| Stryker | USA | Broad handpiece + power console portfolio | Installed base + hospital relationships |
| Medtronic | Ireland/USA | Neuro & spine powered systems | Neuro/ENT integration |
| J&J (DePuy Synthes) | USA | Orthopedic power tools | Ortho implant pull-through |
| Zimmer Biomet | USA | Joint replacement power systems | Ortho bundle economics |
| B. Braun (Aesculap) | Germany | Precision power systems | EU clinical preference |
| CONMED | USA | Arthroscopy & MIS | ASC channel depth |
| Smith & Nephew | UK | Arthro & trauma power tools | Sports medicine adjacency |
| Arthrex | USA | Arthroscopic shavers & resection | Surgeon loyalty / training |
The real moat is battery ecosystem lock-in and service contracts — once a hospital standardizes on a handpiece platform, switching costs (sterilization validation, surgeon habituation, service training) are material. Our analysis suggests the accessories/consumables attach rate is the single best predictor of vendor profitability, not unit share.
Procurement of powered surgical instruments is mission-critical, not commodity. Buyers should evaluate five domains: (1) clinical fit — torque, ergonomics, and procedure-specific handpiece availability; (2) total cost of ownership — capital, batteries, service, and sterilization cycle time; (3) regulatory compliance — FDA 510(k), EU MDR, and ISO 13485 validation; (4) service network depth — response time and loaner availability; and (5) ecosystem integration — compatibility with robotics, navigation, and OR data platforms.
Switching costs are high: re-validating sterilization protocols, retraining surgical staff, and renegotiating service contracts can consume 6–12 months of operational bandwidth. Buyers should therefore avoid single-vendor lock-in on battery platforms and insist on interoperability clauses. Small ASCs face the steepest affordability barrier, making refurbished, leasing, or pay-per-use models a rational entry path.
The balance of evidence favors a 'premium-mix, not volume' thesis. The powered surgical instruments market is growing at ~3.9% CAGR — respectable but not explosive. Value creation will come from shifting revenue toward battery-powered handpieces (4.7% CAGR), consumables (5.0% CAGR), and ASC end-users (5.6% CAGR), which collectively outpace the market average by 100–170 basis points.
The strongest counter-argument is that capital constraints and MDR/FDA scrutiny could compress near-term demand, particularly in LMICs and small ASCs. If regulatory delays extend device approval cycles beyond 18 months, the 3.9% CAGR could settle closer to 2.7%. However, we view this as a timing risk rather than a structural one, given demographic tailwinds.
Actionable strategy for investors and operators:
What would change our conclusion: A sustained deceleration in orthopedic procedure volumes, a major safety recall on Li-ion battery platforms, or a reimbursement shock to ASCs would materially revise the forecast downward. Conversely, accelerated robotic-OR integration could pull forward premium demand by 12–18 months. For sub-segment-level forecasting and vendor-by-vendor share analysis, the full report provides the granularity this overview cannot.
Our analysis is grounded in a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material and component suppliers, specialized instrument manufacturers, contract sterilizers, and global distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads across hospital procurement and OEM channels.
Secondary benchmarking drew on UN Comtrade, WTO, US ITC, and Eurostat trade databases, corporate 10-K and SEC filings, investor presentations, patent databases (USPTO, EPO), and recognized technical standards bodies (ISO 13485, IEC 60601). These sources were cross-referenced to validate unit volumes and pricing corridors.
We applied simultaneous top-down (macroeconomic surgical volume and segment allocation) and bottom-up (manufacturer capacity, ASP, and end-use consumption) modeling. Divergences between the two were reconciled through elasticity adjustments and regional price indexing.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.9% from 2020-2034 |
| Segmentation |
|
The global powered surgical instruments market was valued at approximately USD 2.7 billion in 2025. Estimates range from USD 2.6B to USD 2.7B depending on accessory and battery inclusion, with consensus forecast reaching USD 3.4–3.7 billion by 2033.
The market is growing at a 3.9% CAGR through 2032–2033. Battery-powered systems (4.7% CAGR) and accessories (5.0% CAGR) outpace the overall market, while Asia-Pacific leads regional growth at 5.2% CAGR.
North America leads with approximately 35–43% revenue share in 2025, driven by high surgical volumes and ASC adoption. Asia-Pacific is the fastest-growing region at 5.2% CAGR, fueled by infrastructure investment and rising procedure penetration.
Leading vendors include Stryker, Medtronic, Johnson & Johnson (DePuy Synthes), Zimmer Biomet, B. Braun (Aesculap), CONMED, Smith & Nephew, and Arthrex. The top five control an estimated 55–60% of global revenue.
Orthopedic and trauma surgery is the largest application at ~21–25% share, followed by neurosurgery, ENT, cardiovascular, and plastic surgery. Plastic and reconstructive surgery is the fastest-growing application at ~5.96% CAGR.
Wired-electric systems held ~40.8% share in 2025 due to consistent torque and no battery logistics. Battery-powered systems are growing faster at 4.7% CAGR, favored for portability, ASC use, and reduced OR tripping hazards.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is grounded in a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material and component suppliers, specialized instrument manufacturers, contract sterilizers, and global distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations Leads across hospital procurement and OEM channels.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP-Level Sourcing & Procurement Leads | 35% |
| R&D & Technical Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Affairs Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Component Suppliers | 25% |
| Specialized Instrument Manufacturers | 40% |
| Contract Sterilizers & Service Providers | 15% |
| Global Distributors & OEM Channel Partners | 20% |
Secondary benchmarking drew on UN Comtrade, WTO, US ITC, and Eurostat trade databases, corporate 10-K and SEC filings, investor presentations, patent databases (USPTO, EPO), and recognized technical standards bodies (ISO 13485, IEC 60601). These sources were cross-referenced to validate unit volumes and pricing corridors.
We applied simultaneous top-down (macroeconomic surgical volume and segment allocation) and bottom-up (manufacturer capacity, ASP, and end-use consumption) modeling. Divergences between the two were reconciled through elasticity adjustments and regional price indexing.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping, commercial filings | High |