 Middle East Healthcare Digital Twins Market
 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 214

Amit Mardhekar

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Middle East Healthcare Digital Twins Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2026 | 188.0 M |
| 2027 | 270.0 M |
| 2028 | 388.0 M |
| 2029 | 558.0 M |
| 2030 | 802.0 M |
| 2031 | 1.150 B |
| 2032 | 1.660 B |

The Middle East healthcare digital twins market covers software and services that build virtual replicas of patients, organs, care pathways, or hospital systems, fed by EHR, genomic, imaging, and wearable data. It spans personalized medicine, workflow optimization, device testing, drug discovery, and surgical planning across Saudi Arabia, the UAE, and GCC peers.
This analysis covers regional revenue for healthcare-focused digital twin software and services across Saudi Arabia, the UAE, Kuwait, Qatar, and Oman, segmented by component, twin type, technology, application, end user, and deployment. This analysis does not cover broader industrial or urban digital twin markets, general hospital IT systems, or AI diagnostic software without a simulation-twin component.
Two published estimates diverge sharply — roughly a 2.1x gap at comparable base years — which is the single most important sizing caveat for any buyer building a business case on this market.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
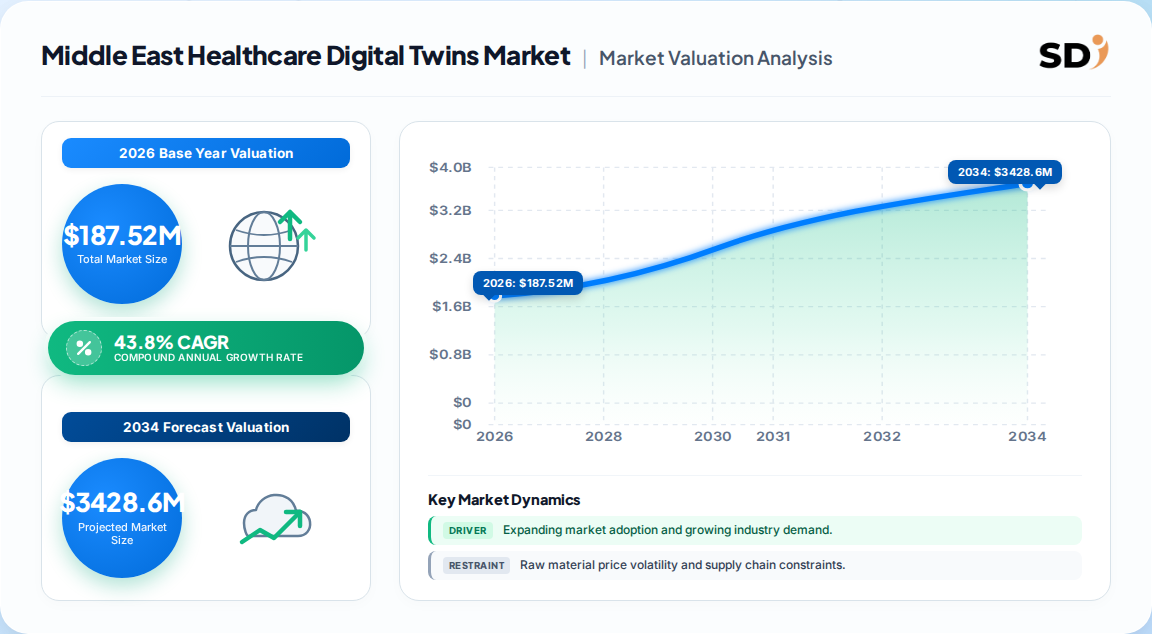
| USD 187.52 million → USD 4,930.22 million | 2026 (USD 130.4M in 2025) | 2035 | 43.8% | Regional healthcare digital twins, software + services | One published estimate |
| USD 29.56 million → USD 135.20 million | 2025 | 2033 | 20.58% | GCC healthcare digital twins, narrower definition | A competing analysis |
| USD 2,222.4 million → USD 22,442.7 million | 2025 | 2033 | 32.6% | MEA all-industry digital twin market, incl. healthcare & life sciences | A third published estimate |
Our analysis suggests the truth sits between the two healthcare-specific estimates: the 43.8% figure likely embeds adjacent simulation and cloud infrastructure spend, while the 20.6% figure appears restricted to core twin platforms. The defensible planning number is a mid-30s CAGR with roughly USD 60–90 million of 2026 regional healthcare-specific revenue.
Segmentation below excludes geography; the parent categories reflect how vendors actually package and price healthcare digital twin capability across the region.
| Parent segment | Children | 2025 share signal |
|---|---|---|
| Component | Software, Services | Software 52%; Services 31% (fastest) |
| Digital twin type | Patient, Organ, Hospital/System, Population | Patient 38%; Organ 24% (fastest) |
| Technology | AI & ML, IoT, Cloud, Big Data, Quantum (emerging) | AI & ML 31% (largest, fastest) |
| Application | Personalized medicine, Workflow & asset optimization, Device design/testing, Drug discovery, Surgical planning | Personalized medicine 27% (largest, fastest) |
| End user | Hospitals & providers, Pharma & biotech, Medical device firms, Research & academia | Hospitals 42%; Pharma 25% (fastest) |
| Deployment | Cloud, On-premise | Cloud 61% (largest, fastest) |
The shape of this segmentation is the strategy: cloud and services growing fastest means the buyer's real commitment is an operating relationship, not a product purchase. Organ twins and pharma end-use growing fastest points to clinical-trial simulation as the near-term revenue engine.
Saudi Arabia leads with 34% of 2025 regional revenue, followed by the UAE at 26%, with the UAE expected to post the fastest CAGR through the forecast period on the back of federal digital health mandates.
This concentration implies that two countries control roughly 60% of regional demand — vendor go-to-market should be Riyadh-and-Abu-Dhabi-first, and country-level forecasts in the full report are what separate a credible pipeline from a wish list.
Growth is driven by government digitization mandates and personalized-medicine demand, but constrained by data fragmentation, scarce clinical-data talent, and cybersecurity exposure at national scale.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Government digital health initiatives & smart hospitals | Driver | High | Public funding converts directly into twin pilots and cloud contracts |
| Personalized medicine & genomic integration | Driver | High | Twin simulation reduces trial sample sizes and adverse-event risk |
| AI/IoT/cloud convergence | Driver | High | Real-time data feeds make twins continuously accurate, not static |
| Aging population & capacity pressure | Driver | Medium | Workflow twins cut wait times and resource waste |
| Data fragmentation across providers | Restraint | High | Poor interoperability delays time-to-value and raises integration cost |
| Cybersecurity & patient-data sovereignty | Restraint | High | Regional data-residency rules raise compliance overhead |
| Scarcity of clinical-modeling talent | Restraint | Medium | Services dependency grows; vendor lock-in risk rises |
The balance favors growth, but the restraints are structural, not cyclical. Our analysis suggests the binding constraint by 2028 is not capital but qualified people — which is precisely why services and managed-operations offerings will outgrow software licenses in revenue terms.
The vendor field splits into hyperscale cloud-AI platforms, imaging and clinical-systems incumbents, and specialized simulation/engineering firms, creating a layered competitive structure rather than a single-front battle.
| Vendor | Archetype | Regional positioning signal |
|---|---|---|
| Microsoft | Hyperscale cloud & AI | Cloud infrastructure and AI twin tooling; largest enterprise footprint |
| Oracle | Cloud & data platform | Health data platforms and cloud regions in KSA/UAE |
| Philips Healthcare | Clinical imaging & monitoring | Twins embedded in imaging/monitoring workflows |
| Dassault Systèmes | Simulation & engineering | Organ and device-simulation heritage (3DS platform) |
| Atos | Systems integration & IT services | Sovereign and public-sector digital health delivery |
| Galderma | Pharma/dermatology | Clinical and dermatology simulation use cases |
| Siemens Healthineers | Imaging & diagnostics | Twin-enabled imaging and outcomes modeling |
Differentiation rests on three moats: access to sovereign cloud regions, validated clinical evidence for twin predictions, and integration depth into provider workflows. Our analysis suggests the incumbents' moat is integration, not algorithms — the twin models themselves are becoming commoditized.
Procurement should be structured around four mission-critical criteria: interoperability with existing EHR and PACS estates, validated predictive accuracy with published clinical evidence, sovereign data residency compliant with national health-data rules, and contractual exit and model-portability rights. Demand references from comparable regional deployments before pilot expansion. Switching costs rise steeply once a twin is trained on a provider's longitudinal data, so negotiate model-ownership and data-export terms at the outset, not at renewal. Budget for services at 40–50% of total cost of ownership; license-only business cases typically underrun by a wide margin.
The balance of evidence favors a high-growth, services-heavy trajectory for this market. Even discounting the most aggressive published CAGR, the mid-30s growth band is robust across independent estimates, and the underlying drivers — sovereign digital health mandates and personalized-medicine funding — are policy-backed, not sentiment-driven. The strongest counter-argument is definitional inflation: broad "digital twin" categorization pulls in cloud and analytics spend that would have occurred anyway, overstating healthcare-specific demand. Buyers should treat headline CAGR as direction, not precision.
Positioning implication: vendors that lead with managed model operations — not software licenses — will capture disproportionate share as talent scarcity binds. For investors, the asymmetry sits in organ-twin and pharma-trial simulation, where clinical evidence and regulatory acceptance are still forming and defensible positions can be built.
Actionable strategy:
The conclusion would change if regional data-residency rules tighten to require on-premise-only deployment, or if a major health system publishes negative clinical-accuracy results for twin-based decision support.
| Region | Market Share (%) |
|---|---|
| Saudi Arabia | 0.34% |
| UAE | 0.26% |
| Kuwait | 0.14% |
| Qatar | 0.13% |
| Oman | 0.13% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 43.8% from 2020-2034 |
| Segmentation |
|
Published estimates range from 20.6% to 43.8% CAGR. A defensible planning band is mid-30s, driven by government digital health mandates and personalized-medicine investment across the GCC.
Saudi Arabia leads with 34% of 2025 revenue. The UAE holds 26% and is expected to grow fastest due to federal smart-hospital and digital health programs.
Software leads components at 52%, patient digital twins lead twin types at 38%, and hospitals and providers lead end use at 42% of 2025 regional revenue.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. We conducted in-depth interviews across the healthcare digital twin value chain — sovereign cloud and platform vendors, clinical software and imaging-system producers, systems integrators, hospital IT and informatics teams, and pharma clinical-innovation groups. Interview designations included Chief Digital/Information Officers, Heads of Clinical Informatics, VP-level procurement and sourcing leads, and commercial operations directors across GCC provider and life-science organizations.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Digital & Information Officers | 35% |
| Clinical Informatics Heads | 30% |
| Procurement & Sourcing Leads | 20% |
| Commercial Operations Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Cloud & Platform Vendors | 35% |
| Clinical Software & Imaging Producers | 30% |
| Systems Integrators & IT Services | 20% |
| Providers & Pharma Innovation Teams | 15% |
We validated findings against official multilateral and standards sources, including UN Comtrade and WTO services-trade data, national health-ministry digital health strategies, corporate annual filings and investor presentations, patent databases, and technical standards from ISO and HL7/FHIR interoperability bodies. No competitor market-research publications are used as validation sources.
We run simultaneous top-down allocation (macro health-IT spend and segment share) and bottom-up modeling (platform deployments, pricing, and end-use consumption) to triangulate market size, reconciling divergent published estimates into a defensible planning band.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up deployment & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border procurement flow & regional consumption analysis | High |
| Competitive Landscape | Leading market players | Annual reports, deployment mapping & commercial filings | High |