 Organic Personal Care Ingredients Market
 Report 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 218

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Organic Personal Care Ingredients Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2026 | 11.70 B |
| 2027 | 12.30 B |
| 2028 | 12.90 B |
| 2029 | 13.50 B |
| 2030 | 14.20 B |
| 2031 | 14.90 B |
| 2032 | 15.60 B |

The organic personal care ingredients market comprises plant-derived, certified-organic raw materials—surfactants, emollients, active ingredients, sugar polymers, and natural preservatives—used in skin, hair, oral, and cosmetic formulations. It excludes finished consumer products and synthetic equivalents; value is measured at the ingredient-supplier level.
This report covers global ingredient-level demand across type (organic, natural), product category, and application, with regional breakdowns. Value is measured at manufacturer-level revenue. This analysis does not cover finished personal care product retail sales, synthetic ingredient markets, packaging, or contract manufacturing services.
Published estimates diverge materially—from 11.1 Billion to 12.5 Billion for 2025–2026—reflecting differing definitions of "organic" and inclusion of natural versus certified-organic ingredients. The table below reconciles the leading estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 11.1 Billion | 2025 | 2033 | 5.4% | Organic + natural ingredients, supplier-level | One published estimate |
| 11.7 Billion | 2026 | 2033 | 5.4% | Same scope, forward base | One published estimate |
| 12.5 Billion | 2026 | 2034 | 5.0% | Broader product taxonomy incl. sugar polymers | A competing analysis |
| 4.6 Billion | 2024 | 2030 | 7.5% | Narrower ingredient set, higher growth assumption | A competing analysis |
The higher-CAGR estimate likely reflects a narrower ingredient basket with aggressive clean-beauty penetration assumptions. Our analysis suggests the 11.7 Billion base with 5.0–5.4% CAGR is most defensible, because it aligns with certification-volume growth and mainstream retailer expansion rather than niche premium adoption alone.
Segmentation spans ingredient type, product category, and application. Organic-certified inputs command premium pricing, while natural (non-certified) inputs drive volume growth in mass and private-label channels.
| Parent | Children |
|---|---|
| Type | Organic, Natural |
| Product | Natural Surfactants, Emollients, Active Ingredients, Sugar Polymers, Natural Preservatives, Others |
| Application | Skin Care, Hair Care, Oral Care, Cosmetics, Others |
The product mix is shifting: sugar polymers held the largest product share in 2025, while active ingredients grow fastest as brands demand clinically supportable naturals. This implies suppliers with bioactive IP capture disproportionate value versus commodity emollient sellers.
North America leads with approximately 35% of global revenue in 2025, driven by clean-beauty retail penetration and USDA Organic labeling infrastructure. Europe follows at roughly 28%, supported by COSMOS and Ecocert certification density.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.28% |
| Asia-Pacific | 0.24% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
Asia-Pacific is the fastest-growing region, with one estimate placing its CAGR near 10% for adjacent bio-based categories. This divergence implies multinational suppliers should localize sourcing and formulation support in China and India to defend share against regional entrants.
Consumer clean-label demand, regulatory certification expansion, and extraction-technology advances are the primary growth engines. Conversely, raw-material variability, certification cost, and formulation-stability constraints cap adoption in mass segments.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Clean-beauty consumer demand | Driver | High | Shifts formulation budgets toward certified inputs |
| Certification regimes (COSMOS, USDA) | Driver | High | 34,000+ COSMOS-certified items across 78 countries |
| Biotechnology extraction | Driver | Medium | Improves purity and actives yield |
| Raw-material variability | Restraint | High | Forces extra QC and raises unit cost |
| Certification cost burden | Restraint | Medium | Delays smaller-brand entry |
| Formulation stability limits | Restraint | Medium | Restricts use in long-shelf-life formats |
The balance favors growth, but our analysis suggests the restraint stack disproportionately affects small brands, consolidating bargaining power with large certified suppliers. This creates a structural margin advantage for incumbents with vertically integrated sourcing.
The competitive field is led by diversified chemical majors with certified portfolios alongside specialty naturals players. Differentiation rests on certification breadth, sourcing traceability, and formulation support services.
| Company | Portfolio emphasis | Strategic moat |
|---|---|---|
| BASF SE | Bio-based actives, surfactants | R&D scale, global certification coverage |
| Croda International | Bio-surfactants, emollients | Sustainability positioning, green chemistry |
| Evonik Industries | Bio-based specialties | Formulation partnership model |
| Clariant AG | Natural preservatives, actives | Portfolio breadth, regional reach |
| Ashland Global | Functional naturals | Application expertise |
| Cargill | Plant oils, emulsifiers | Agricultural sourcing integration |
| Galaxy Surfactants | Natural surfactants | Cost leadership in APAC |
Smaller specialists such as INOLEX compete on premium plant-based emulsifiers and formulation intimacy. This divergence implies M&A activity will target certification-rich niche formulators rather than commodity capacity.
Procurement teams should prioritize suppliers with verified COSMOS or USDA certification and documented traceability, since certification gaps create downstream reformulation risk. Switching costs are elevated because reformulation triggers stability testing and re-certification cycles.
Raw-material variability is the dominant operational risk: botanical actives fluctuate in potency by season and geography, demanding robust QC protocols. Buyers should negotiate quality-consistency clauses and dual-source critical actives.
Regulatory complexity varies by region—EU Cosmetics Regulation and NSF/ANSI 305 labeling rules impose disclosure burdens. Operators must budget for compliance documentation as a fixed cost, favoring suppliers who pre-package regulatory dossiers.
The balance of evidence favors a 5.0–5.4% CAGR base case, not the 7.5% outlier, because certification volume growth and mainstream retail expansion are steady rather than explosive. The strongest counter-argument: Asia-Pacific premiumization could accelerate adoption faster than modeled, validating bullish estimates.
Our analysis suggests value will accrue to suppliers combining certified bioactive IP with vertically integrated botanical sourcing. Commodity emollient positions face margin compression as private-label demand rises and price sensitivity intensifies.
Evidence that would change this conclusion: sustained double-digit APAC volume growth or regulatory mandates requiring certified-organic content in mass-market products, either of which would justify the higher CAGR scenario.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.0% from 2020-2034 |
| Segmentation |
|
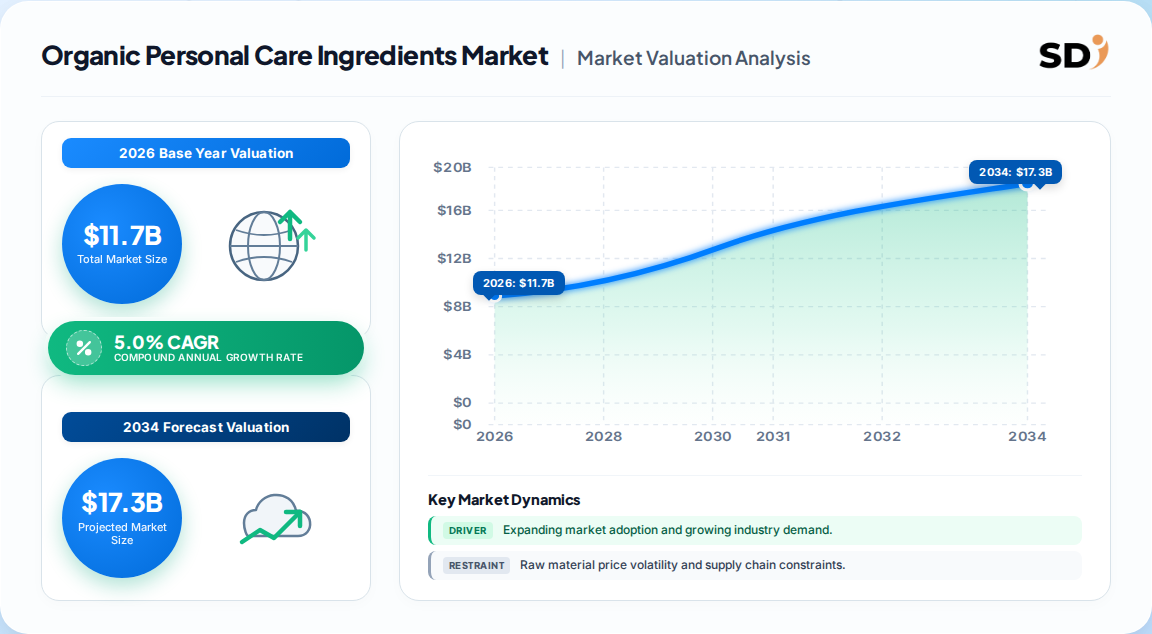
The market was valued at approximately 11.7 Billion in 2026, with published estimates ranging from 11.1 Billion to 12.5 Billion depending on whether natural, non-certified inputs are included in scope.
The most defensible base case is a CAGR of approximately 5.0% to 5.4% through the early 2030s, though some analyses project up to 7.5% using narrower ingredient definitions and aggressive clean-beauty adoption assumptions.
North America leads with roughly 35% revenue share, supported by clean-beauty retail penetration and USDA Organic labeling infrastructure. Europe follows at about 28%, while Asia-Pacific is the fastest-growing region.
Organic-certified inputs represent about 62% of type revenue. Sugar polymers lead product segments, while skin care is the largest application, followed by hair care.
Leading vendors include BASF, Croda International, Evonik, Clariant, Ashland Global, Cargill, and Galaxy Surfactants, alongside specialists such as INOLEX competing on premium plant-based formulations.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employed a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers, specialized organic ingredient producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP-level Sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement Directors | 35% |
| Quality & Regulatory Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Specialty Chemical Producers | 45% |
| Formulators & Blenders | 35% |
| Distributors & Traders | 20% |
Secondary validation drew on UN Comtrade and Eurostat trade flows, US ITC tariff schedules, corporate annual filings (10-K, SEC), patent databases, and recognized non-profit technical standards bodies including COSMOS and NSF/ANSI. No third-party market research publisher data was used as primary validation.
Market sizing triangulated Top-Down macroeconomic and segment allocation modeling against Bottom-Up manufacturer capacity, pricing, and end-use consumption modeling. Divergent published estimates were reconciled through definitional scope mapping.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |