 Asean Cosmetic Chemicals Market
 Outlook 2026
Updated On : Nov 17, 2026|Base Year : 2025|Pages : 193

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Asean Cosmetic Chemicals Market
Amit Mardhekar
Research Analyst

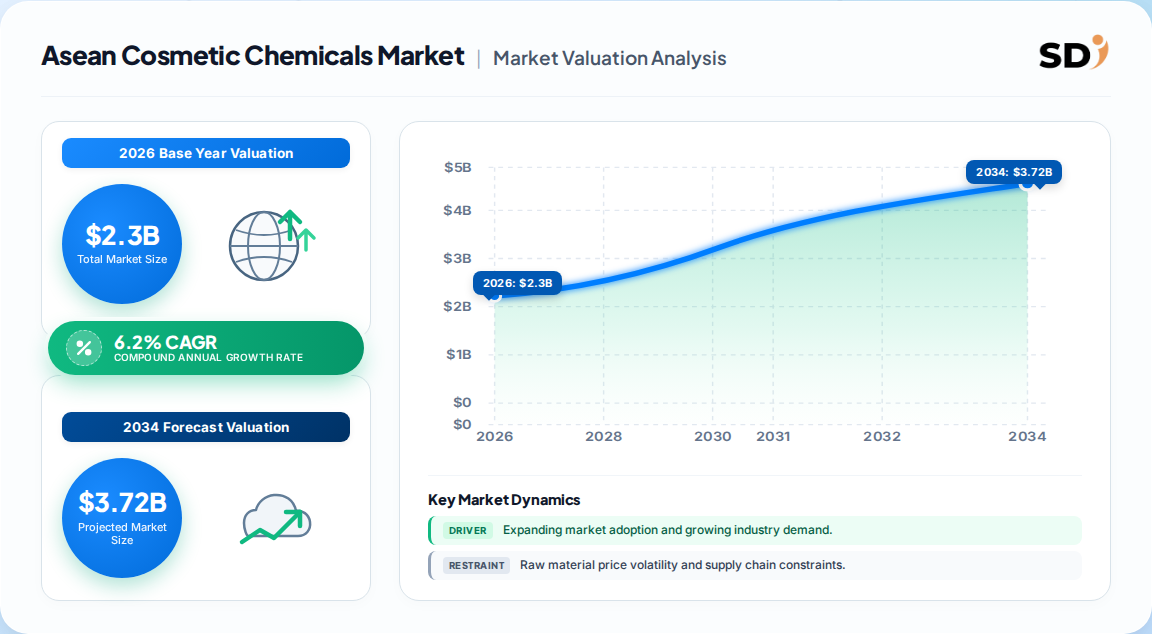
| Year | Market Size |
|---|---|
| 2026 | 2.300 B |
| 2027 | 2.440 B |
| 2028 | 2.590 B |
| 2029 | 2.750 B |
| 2030 | 2.920 B |
| 2031 | 3.100 B |
| 2032 | 3.300 B |

The ASEAN cosmetic chemicals market is the supplier-level trade in functional and active ingredients — surfactants, emollients, polymers, preservatives, thickeners, colorants and actives — sold to cosmetic and personal-care formulators across the ten ASEAN member states, valued at USD 2.3 Billion in 2026.
This report covers cosmetic chemicals consumed in ASEAN-10 formulation and manufacturing: product-type volumes (surfactants, emollients and film formers, polymers, preservatives, thickening agents, additives, colorants), application demand (skin care, hair care, make-up, oral care, fragrances, other personal care) and country-level adoption.
This analysis does not cover finished cosmetic retail revenue, pharmaceutical excipients, household and industrial cleaning chemicals, or packaging materials.
Two credible framings exist: a regional ASEAN-specific estimate of USD 2.3 Billion for 2026 growing at 6.2%, and a broader global cosmetic chemicals estimate of USD 5.3 Billion in 2026 at 8.4%. The gap reflects scope, not disagreement about demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 2.3 Billion | 2026 | 2036 | 6.2% | ASEAN-10 ingredient value at supplier level, all cosmetic applications | One published regional estimate |
| USD 5.3 Billion | 2026 | 2033 | 8.4% | Global cosmetic chemicals, active-ingredient-weighted product taxonomy | A competing analysis |
Our analysis favours the USD 2.3 Billion figure for ASEAN procurement planning. The narrower product taxonomy in the global series concentrates value in premium actives, inflating growth, whereas ASEAN volume is anchored in high-repeat surfactant chemistry.
The market splits into a high-volume functional base and a higher-value, claim-driven active layer. Surfactants and emollients carry throughput; skin-care actives carry margin.
| Parent segment | Children |
|---|---|
| Product type | Surfactants; Emollients and film formers; Polymers; Preservatives; Thickening agents; Additives; Colorants |
| Application | Skin care; Hair care; Make-up; Oral care; Perfumes and fragrances; Other personal care |
| Function | Cleansing and emulsification; Conditioning; Preservation; Rheology control; Sensory modification; Colour |
Surfactants at 34% share reflect formulation load factors, not premium pricing. Skin care at 43% reflects ingredient intensity per SKU, which is why actives and substantiation services grow faster than the underlying volume.
Thailand leads on absolute ingredient consumption, supported by a mature contract-manufacturing base and a formal cosmetic control framework. Indonesia is the largest demand pool by population but converts to chemical volume more slowly due to notification modernisation.
This divergence implies suppliers should treat Thailand and Indonesia as volume anchors and Vietnam as the incremental-capacity bet. Singapore punches above its volume weight in specification influence.
Demand is being pulled by regulatory harmonisation and pushed by regional capacity additions. The binding constraint is documentation and claim-substantiation capacity, not raw material availability.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| ASEAN Cosmetic Directive harmonisation | Driver | High | Reduces technical barriers, raises multi-country launch volume per formulation |
| Regional surfactant capacity (APG, Thailand) | Driver | High | Shorter lead times, lower stockout penalties on launch calendars |
| Science-backed active demand | Driver | High | Higher ingredient value per SKU in skin care |
| In-region claim substantiation (Singapore) | Driver | Medium | Lowers testing friction for premium actives |
| Regulatory documentation intensity | Restraint | High | Raises compliance cost and slows supplier onboarding |
| Raw material price volatility | Restraint | Medium | Compresses formulator margins on commodity surfactants |
The balance favours growth, but the restraint is structural. Our analysis suggests documentation capability is becoming a moat that filters out smaller suppliers faster than price competition does.
The supplier base is concentrated at the top but fragmented below it. Scale players compete on portfolio breadth and regional capacity; specialists compete on actives and substantiation.
| Company | Position | Distinctive strength |
|---|---|---|
| BASF | Leader, ~12% share | Broadest surfactant and care portfolio; Thailand APG capacity |
| Dow | Challenger | Silicone and conditioning chemistry depth |
| Evonik | Challenger | Actives and skin-science substantiation platform |
| Clariant | Challenger | Preservation and surfactant systems |
| Croda International | Specialist | Bio-based and high-performance emollients |
| DSM-Firmenich | Specialist | Vitamins, UV filters and fragrance integration |
| Ashland, Lubrizol, Symrise, SEPPIC | Niche | Rheology, sensory and marine actives |
Differentiation is shifting from molecule novelty to service reliability. BASF's moat is availability plus documentation; Evonik's is biological claim support. Buyers increasingly award contracts on the second axis.
Procurement priority has moved from price per kilogram to total cost of compliant launch. A cheaper surfactant that forces re-documentation across five markets is more expensive than a validated incumbent.
Buyers should verify three things before contracting: ASEAN Cosmetic Directive dossier completeness, regional stock-holding or local plant proximity, and claim-substantiation support for any active-led positioning. Switching costs rise sharply once a formulation is notified in multiple countries.
Operators should also model lead-time risk explicitly. Stockout penalties on retail launch calendars dwarf unit-price savings, which is why regional capacity announcements matter more than headline pricing in supplier selection.
The balance of evidence favours a supply-securing posture over a price-optimising one through 2028. Demand growth of 6.2% is modest, but compliance friction is rising faster than volume, so the effective constraint on formulator output is validated supplier capacity.
The strongest counter-argument is that harmonisation eventually commoditises documentation, eroding the moat and pushing margins back toward price. That is plausible after 2030; before then, notification cycles and in-region testing capability remain scarce.
Our conclusion would change if ASEAN notification timelines compressed materially or if two or more major suppliers added regional surfactant capacity simultaneously — either would shift the advantage back to buyers.
| Region | Market Share (%) |
|---|---|
| Thailand | 0.22% |
| Indonesia | 0.21% |
| Vietnam | 0.18% |
| Philippines | 0.14% |
| Malaysia | 0.13% |
| Singapore | 0.08% |
| Others | 0.04% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.2% from 2020-2034 |
| Segmentation |
|
It is USD 2.3 Billion in 2026, measured at supplier-level ingredient value across the ten ASEAN member states and all cosmetic applications.
The market is projected to grow at 6.2% from 2026 to 2036, reaching USD 4.1 Billion. Growth is anchored in surfactant volume and skin-care actives.
Vietnam leads at 6.7% CAGR, driven by formalised notification, labelling and safety rules that raise compliance-led ingredient demand across formulators.
Surfactants lead with 34% share because cleansing and emulsification systems carry the largest repeat-volume chemical load in skin and hair formats.
BASF leads at approximately 12% share, reinforced by regional surfactant capacity expansion in Thailand and broad formulation portfolio coverage.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material and surfactant producers, specialised active-ingredient manufacturers, contract formulators and blenders, and regional distributors across Thailand, Indonesia, Vietnam and Singapore. Respondents were designated decision-makers: VP-level sourcing and procurement leads, heads of R&D and formulation, technical directors, and commercial operations managers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Formulation Heads | 32% |
| Technical & Regulatory Directors | 20% |
| Commercial Operations Managers | 13% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Surfactant Producers | 42% |
| Specialised Active Ingredient Producers | 28% |
| Contract Formulators & Blenders | 18% |
| Regional Distributors & Traders | 12% |
Findings are cross-checked against UN Comtrade and WTO trade flows, national statistical filings, corporate annual reports and investor presentations, patent activity in cosmetic actives, and technical standards from recognised industry associations. Regulatory benchmarks reference the ASEAN Cosmetic Directive and national notification systems.
Top-down sizing allocates macroeconomic personal-care output to chemical ingredient intensity by application. Bottom-up modeling aggregates manufacturer capacity, product pricing and end-use consumption. The two paths are reconciled to a single base-year estimate with documented variance.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Ingredient value in USD, 2026 | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | 2026 to 2036 compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border trade flow and consumption analysis | High |
| Competitive Landscape | Leading suppliers | Annual reports, capacity mapping and filings | High |