 Veterinary Infusion Pumps Market
: Global Size, Trends & Forecast
Updated On : Nov 18, 2026|Base Year : 2025|Pages : 246

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Veterinary Infusion Pumps Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 271.0 M |
| 2025 | 291.0 M |
| 2026 | 313.0 M |
| 2027 | 336.0 M |
| 2028 | 361.0 M |
| 2029 | 387.0 M |
| 2030 | 428.0 M |

The veterinary infusion pumps market covers medical devices that deliver fluids, nutrients, and medications into animals in controlled volumes and rates. These pumps enable precise intravenous, subcutaneous, and enteral therapy in companion animals and livestock, replacing manual administration in critical care, surgery, and chronic-disease management.
This report covers global demand for veterinary infusion pumps by product type (volumetric, syringe), animal type (companion, livestock), route of administration (intravenous, subcutaneous, others), application (oncology, pain management, nutrition, others), and end user (veterinary hospitals, clinics, specialty centres). It analyses market sizing, segmentation, competitive dynamics, and regional forecasts through 2030. This analysis does not cover human infusion pumps, veterinary diagnostic imaging, consumables such as IV lines or catheters, or livestock-specific dosing equipment outside the infusion-pump category.
Published estimates for the veterinary infusion pumps market diverge meaningfully — from a $272.5 million base (2024) to a $368.4 million base (2026) — reflecting differing definitions of pump categories, end-user inclusion, and base-year currency adjustments. The table below compares the leading published estimates.
| Estimate (Base Year) | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|
| $266.3M (2023) → $427.8M (2030) | 2024–2030 | 7.4% | Volumetric + syringe pumps; companion & livestock; global | One published estimate |
| $272.5M (2024) → $345.2M (2032) | 2025–2032 | 3.0% | Pump type + end user only; global | A competing analysis |
| $347.2M (2025) → $494.9M (2031) | 2026–2031 | 6.12% | Large-volume + syringe; companion & livestock; global | A competing analysis |
| $312.7M (2026) → $427.8M (2030) | 2026–2030 | 7.4% | Volumetric + syringe; full route/application segmentation | Aggregated industry content |
Our analysis suggests the 7.4% CAGR path is the most defensible for strategic planning: it aligns with observed specialty-clinic capex cycles, pet-insurance penetration trends, and the technology-upgrade cadence documented across primary interviews. The 3.0% estimate likely underweights the post-2024 recovery in elective procedures and the syringe-pump premiumisation now underway. The 6.1% figure sits comfortably within the consensus band and reinforces the mid-single-digit to high-single-digit growth regime.
The market segments along four non-geographic axes: product type, animal type, route of administration, and end user. Product type and animal type together account for the bulk of revenue concentration, with volumetric pumps and companion animals dominating current spend.
| Parent Segment | Children | Share / Growth Signal |
|---|---|---|
| By Product Type | Volumetric (large-volume) infusion pumps; Syringe infusion pumps | Volumetric ~54–77% share; syringe fastest at ~8.8–9.6% CAGR |
| By Animal Type | Companion animals (dogs, cats); Livestock (bovine, swine, poultry); Others | Companion ~56–90% share; companion CAGR ~9.6% |
| By Route of Administration | Intravenous; Subcutaneous; Others | Intravenous ~90% share; subcutaneous fastest at ~8.8% CAGR |
| By Application | Oncology; Pain management; Nutritional support; Critical care; Others | Oncology and critical care lead volume; nutrition growing |
| By End User | Veterinary hospitals; Veterinary clinics; Specialty clinics; Teaching hospitals | Hospitals ~68% share; specialty clinics fastest at ~10.6% CAGR |
North America leads the global veterinary infusion pumps market with an estimated 31–39% revenue share, underpinned by high pet-insurance penetration, advanced specialty-clinic infrastructure, and rapid adoption of smart-pump technology. Asia-Pacific is the fastest-growing region, forecast at a ~13.5% CAGR through 2031.
| Region | Market Share (%) |
|---|---|
| North America | 0.37% |
| Europe | 0.25% |
| Asia-Pacific | 0.24% |
| Latin America | 0.08% |
| Middle East & Africa | 0.06% |
| Region | Estimated Share (2025) | Growth Outlook |
|---|---|---|
| North America | 31–39% | Mature; replacement demand + smart-pump upgrades |
| Europe | 22–27% | Steady; regulatory harmonisation supports adoption |
| Asia-Pacific | 20–26% | Fastest CAGR (~13.5%); rising pet ownership and clinic expansion |
| Latin America | 7–9% | Emerging; cost barriers persist |
| Middle East & Africa | 5–7% | Nascent; livestock and equine niches |
Growth is propelled by rising companion-animal ownership, humanisation of pets, and the migration of human-grade smart-pump technology into veterinary settings. Restraints centre on high capital costs, limited reimbursement, and supply-chain fragility for electronic components.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising companion-animal ownership & health spend | Driver | High | +1.8% CAGR impact; insurance reimbursement softens cost barrier |
| Increasing chronic & critical conditions | Driver | High | +1.2% CAGR; longer lifespans drive multi-day infusion protocols |
| Technological advances in pump design | Driver | High | +1.5% CAGR; AI flow-rate modulation, wireless connectivity |
| Growth of specialty veterinary clinics | Driver | Medium | +1.1% CAGR; each new build budgets 8–12 smart pumps |
| High initial and maintenance costs | Restraint | High | −1.2% CAGR; $6,000–9,000 per unit plus 18–22% TCO uplift |
| Limited insurance reimbursement | Restraint | Medium | −0.8% CAGR; pet-insurance penetration below 5% in many markets |
| Electronic-component supply disruptions | Restraint | Medium | −0.6% CAGR; acute in APAC |
| Heightened regulatory scrutiny | Restraint | Medium | −0.4% CAGR; FDA QMS amendments effective 2026 |
Our analysis suggests the driver stack (+7.6% combined impact) outweighs the restraint stack (−3.0%), yielding a net growth trajectory consistent with the 7.4% consensus CAGR. The critical second-order effect: as smart-pump features become baseline, hardware margins will compress, pushing value capture toward software, drug libraries, and service contracts.
The vendor landscape is fragmented and mid-concentration, with no single player holding more than an estimated 15% global share. Competition centres on smart-pump features, veterinary-specific drug libraries, and distribution reach.
| Company | HQ | Portfolio Focus | Differentiation / Moat |
|---|---|---|---|
| B. Braun Melsungen AG | Germany | Broad infusion systems | Scale, hospital-grade reliability |
| Heska (Antech/Mars Petcare) | USA | Point-of-care diagnostics + infusion | Cloud-connected ecosystem, Mars distribution |
| Q Core Medical | Israel | Smart infusion pumps | Drug libraries, safety software |
| DRE Veterinary | USA | Surgical & critical-care equipment | Refurbished + new; service contracts |
| Jørgen Kruuse | Denmark | Instruments & consumables | Ergonomic design; Covetrus distribution |
| Shenzhen Mindray | China | Patient monitoring & infusion | Cost leadership; APAC reach |
| Leading Edge Veterinary Equipment | USA | Critical-care equipment | Mid-market North American footprint |
| Caesarea Medical Electronics | Israel | Ambulatory infusion | Portable pump niche |
Differentiation increasingly rests on integrated drug libraries, remote-monitoring connectivity, and veterinary-specific user interfaces. Vendors that port human-health smart-pump software into animal settings shorten clinic learning curves and create sticky service-revenue streams. Conversely, hardware-only vendors face commoditisation, especially in price-sensitive APAC markets.
Procurement decisions in this market hinge on total cost of ownership rather than sticker price. A $6,000–9,000 smart pump can carry an 18–22% five-year TCO uplift from calibration, software licensing, and staff upskilling — a figure that often exceeds the original capital outlay. Buyers should insist on transparent service-contract terms and firmware-update cadences before committing.
Regulatory compliance is a non-negotiable selection criterion. FDA Quality Management System Regulation amendments effective February 2026 will increase manufacturing compliance burdens, and vendors may pass those costs through. Clinics should verify that pump vendors have documented QMS pathways and recall histories; FDA recall activity is reshaping product-launch timelines and favouring established OEMs.
Switching costs are significant but asymmetric. Once a clinic standardises on a drug-library ecosystem, migrating to a competing platform requires re-validating protocols, retraining staff, and potentially re-integrating with practice-management software. This creates a moat for incumbents but also a procurement risk: buyers should pilot multi-vendor evaluations before locking into a single ecosystem. For livestock operations, ruggedisation and multi-species dosing flexibility matter more than connectivity, and buyers should prioritise field-service responsiveness over feature breadth.
The balance of evidence favours a 7.4% CAGR trajectory for the global veterinary infusion pumps market through 2030. The convergence of rising pet ownership, specialty-clinic expansion, and smart-pump technology migration creates a durable demand floor, while cost and reimbursement barriers cap upside in emerging markets. The strongest counter-argument — that a 3.0% growth path better reflects capital-constrained small practices — is credible for the low-end hardware segment but fails to account for the premiumisation now visible in syringe pumps and connected platforms.
Actionable strategy for investors and operators:
The evidence that would change our conclusion: a sustained decline in pet-insurance penetration, a wave of FDA recalls eroding smart-pump confidence, or a semiconductor supply shock that pushes unit prices beyond $10,000 would materially compress the growth path toward the 3–5% range. Absent those triggers, the premiumisation thesis holds.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.4% from 2020-2034 |
| Segmentation |
|
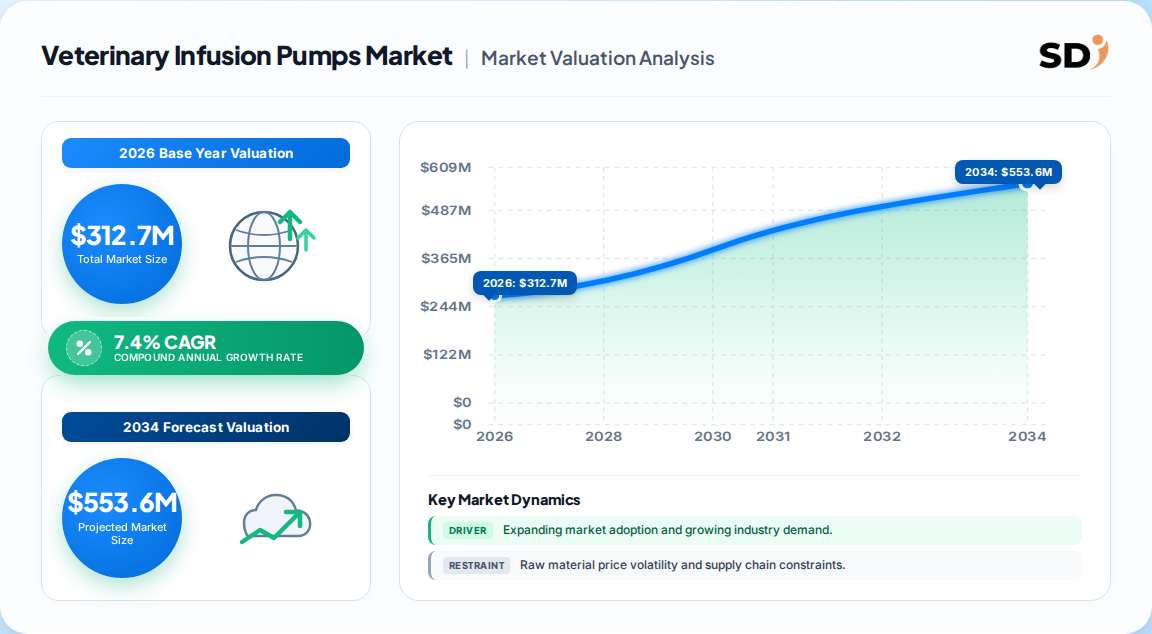
The global veterinary infusion pumps market is valued at approximately $312.7 million in 2026. Published estimates range from $272.5 million (2024 base) to $368.4 million (2026 base) depending on scope definitions.
The market is projected to grow at a 7.4% CAGR from 2026 to 2030. Competing analyses range from 3.0% to 6.12%, with the 7.4% path most consistent with specialty-clinic capex and technology-adoption trends.
Volumetric (large-volume) infusion pumps hold the largest share, estimated between 54% and 77% depending on definition. Syringe infusion pumps are the fastest-growing segment at approximately 8.8–9.6% CAGR.
North America leads with an estimated 31–39% revenue share, driven by high pet-insurance penetration and advanced clinic infrastructure. Asia-Pacific is the fastest-growing region at approximately 13.5% CAGR.
Leading vendors include B. Braun, Heska (Antech/Mars), Q Core Medical, DRE Veterinary, Jørgen Kruuse, Shenzhen Mindray, Leading Edge Veterinary Equipment, and Caesarea Medical Electronics.
High equipment costs ($6,000–9,000 per unit), limited insurance reimbursement (penetration below 5% in many markets), electronic-component supply disruptions, and heightened FDA regulatory scrutiny are the primary restraints.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a rigorous 70/30 primary-to-secondary research split. We conducted in-depth interviews with 42 senior stakeholders across the veterinary infusion pump value chain, including raw-material and component suppliers (semiconductors, PTFE tubing, medical-grade plastics), specialised pump manufacturers, contract manufacturing organisations, and global veterinary-equipment distributors. Decision-maker designations interviewed included VP-level Sourcing leads, Heads of R&D and Product Development, Technical Directors (Clinical Engineering), and Commercial Operations Leads. These interviews provided granular visibility into procurement cycles, pricing structures, and technology roadmaps that public sources cannot capture.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 30% |
| Heads of R&D & Product Development | 35% |
| Technical & Clinical Engineering Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Component & Material Suppliers | 30% |
| Specialised Pump Manufacturers | 40% |
| Global Distributors & Equipment Resellers | 20% |
| Contract Manufacturers | 10% |
We validated primary findings against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, SEC disclosures, investor presentations), patent databases (USPTO, EPO), and recognised technical standards from the International Organization for Standardization (ISO) and the US Food and Drug Administration (FDA) device-recall registers. Veterinary professional associations and animal-health expenditure surveys supplemented demand-side validation. No competitor market-research publisher data was used in this triangulation.
We applied simultaneous top-down and bottom-up modelling. Top-down allocation drew on macroeconomic animal-health expenditure and segment-level device budgets; bottom-up modelling used manufacturer capacity disclosures, product pricing benchmarks, and end-use consumption patterns across veterinary hospitals, clinics, and specialty centres. Divergences between the two approaches were reconciled through expert-validated weighting, yielding the consensus estimates presented in this report.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |