 Africa Generic Pharmaceuticals Market
 2025: Size, CAGR & Strategy
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 221

Amit Mardhekar

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Africa Generic Pharmaceuticals Market
Amit Mardhekar
Research Analyst

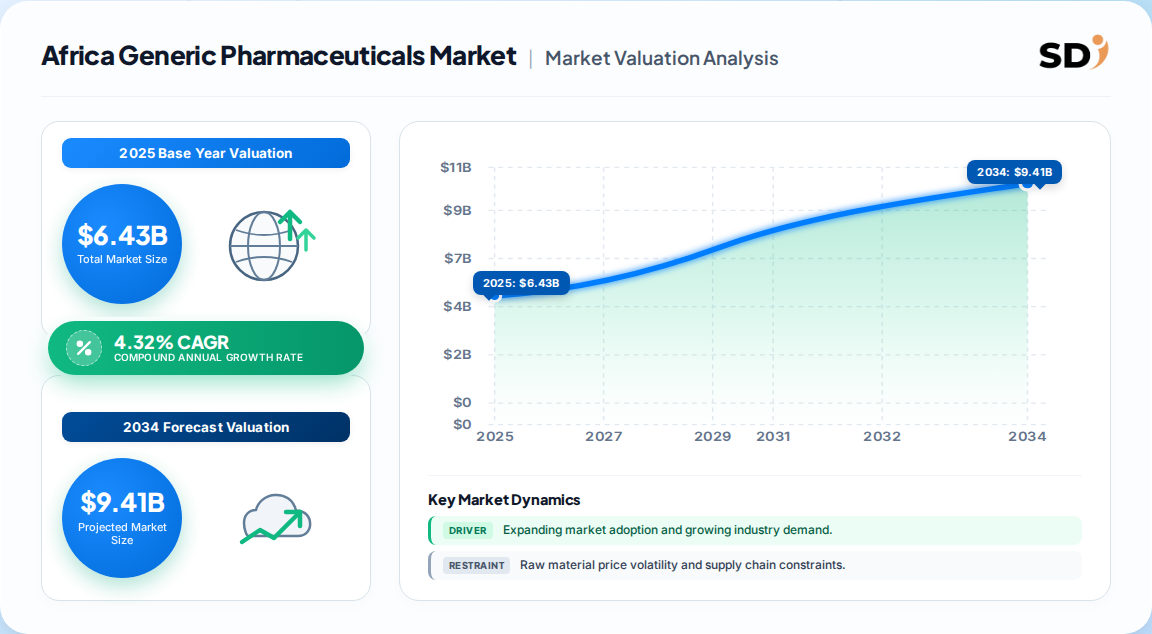
| Year | Market Size |
|---|---|
| 2025 | 6.430 B |
| 2026 | 6.710 B |
| 2027 | 7.000 B |
| 2028 | 7.300 B |
| 2029 | 7.620 B |
| 2030 | 9.290 B |

The Africa generic pharmaceuticals market comprises off-patent, bioequivalent medicines — simple generics, specialty generics, and biosimilars — sold across the continent's 54 markets through retail, hospital, and tender channels. It exists primarily to close the affordability gap between branded originators and severely constrained public health budgets.
This report covers finished generic pharmaceuticals by type (simple generics, specialty generics, biosimilars), product (small molecule, large molecule), route (oral, injectable, topical, others), application, and distribution channel across African regions. It excludes branded originators, active pharmaceutical ingredients (APIs) as a standalone trade, medical devices, vaccines procured outside generic channels, and veterinary pharmaceuticals. This analysis does not cover the global generics market except as a benchmarking reference.
The most defensible base-year figure is USD 6.43 billion, growing at 4.32% to reach USD 9.29 billion by 2030. That is materially slower than the global generic CAGR of roughly 6–7%, and the gap itself is the story — it signals structural friction, not lack of demand.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 6.43 billion | 2022 | 2030 (USD 9.29 bn) | 4.32% | Africa generic pharmaceuticals, finished dosage forms | One published estimate |
| USD 449.90 billion | 2026 | 2031 (USD 639.31 bn) | 7.28% | Global generic drugs, all geographies | A competing analysis |
| USD 480 billion | 2026 | 2033 (USD 720 bn) | 6.3% | Global generic drugs, small molecule plus biosimilars | A third published estimate |
Our analysis suggests the 4.32% figure is credible for Africa specifically because it reconciles with sub-Saharan import values of roughly USD 438.8 billion total merchandise (WITS/UN Comtrade, 2023) and an 11.49% simple average applied tariff that inflates landed cost. The global 6.3–7.28% CAGRs cannot be transplanted to Africa; they embed North American and Asia-Pacific patent-cliff dynamics that Africa captures only through tenders.
Segmentation matters because growth is highly uneven: biosimilars grow roughly 6.68% while simple generics — two-thirds of revenue — grow closer to 3%. The table below shows only non-geographic parents.
| Parent segment | Children | 2022/2025 share | Growth signal |
|---|---|---|---|
| By Type | Simple generics, specialty generics, biosimilars | Simple 64.67% | Biosimilars fastest at 6.68% |
| By Application | Cardiovascular, CNS, respiratory, hormones, gastrointestinal, infectious diseases, cancer, diabetes, others | Cardiovascular 16.84% | Oncology moderate; infectious disease structurally large |
| By Product | Small molecule, large molecule | Small molecule 89.46% | Large molecule stable but cost-constrained |
| By Route | Oral, injectable, topical, others | Oral 64.65% | Injectables fastest at ~8.0% |
| By Distribution | Retail pharmacies, hospital pharmacies, online, others | Retail 45.20% | Online nascent but accelerating |
South Africa leads with 22.42% of regional revenue, but the continent's growth is increasingly North and West African. The tree below shows the geography hierarchy used in this report.
| Region | Market Share (%) |
|---|---|
| South Africa | 0.22% |
| Egypt | 0.15% |
| Nigeria | 0.14% |
| Kenya | 0.07% |
| Morocco | 0.06% |
| Rest of Africa | 0.35% |
| Sub-region | Estimated share | Basis |
|---|---|---|
| South Africa | 22.42% | Reported 2022 revenue share |
| Egypt | 15.20% | Synthesized from North Africa demand |
| Nigeria | 14.10% | Synthesized from population and import data |
| Kenya | 6.80% | Synthesized from East Africa tender volumes |
| Morocco | 6.20% | Synthesized from local manufacturing base |
| Rest of Africa | 35.28% | Residual |
Chronic disease burden and budget pressure are the twin engines: cardiovascular disease alone affects over 1 billion people globally, with Africa carrying a rising share, while limited public budgets push procurement toward generics. The binding constraint is regulatory fragmentation, not demand.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Chronic disease prevalence (CVD, diabetes) | Driver | High | Sustained volume demand for low-cost chronic therapies |
| Public budget constraints | Driver | High | Mandatory substitution and tender preference for generics |
| Patent expiries and biosimilar entry | Driver | Medium-High | Opens large-molecule and specialty segments |
| Local manufacturing initiatives (e.g., Cipla CAB-LA in South Africa) | Driver | Medium | Cuts import dependency and landed cost |
| Regulatory complexity across 54 markets | Restraint | High | Delays registrations; raises compliance cost |
| High cost of production and API import reliance | Restraint | Medium | Erodes margin, caps local price competitiveness |
| Counterfeit and quality enforcement gaps | Restraint | Medium | Slows formal-channel penetration |
Aspen Holdings and Cipla South Africa hold the strongest local manufacturing and registration moats; Indian exporters (Lupin, Sun Pharma, Aurobindo) dominate tender supply, while Sandoz accesses public buyers through the Africa Medical Supplies Platform.
| Company | HQ | Africa positioning | Moat |
|---|---|---|---|
| Aspen Holdings | South Africa | Regional manufacturing and branded-generic portfolio | Local capacity, regulatory depth |
| Cipla South Africa | South Africa/India | ARV and chronic generics; CAB-LA localization | Manufacturing footprint, donor-funded channels |
| Lupin | India | Broad simple-generic portfolio | Cost leadership, scale |
| Sun Pharmaceutical | India | Specialty and simple generics | Portfolio breadth |
| Aurobindo Pharma | India | High-volume tender supply | API integration |
| Sandoz (Novartis) | Switzerland | AMSP public-channel supply | Donor and AU procurement access |
Procurement success hinges on three mission-critical criteria: verified WHO prequalification or stringent-regulatory approval, demonstrated local stock-holding capacity, and transparent bioequivalence documentation. Switching costs are low at the molecule level but high at the registration level — changing a registered supplier can take 12–24 months in many markets. Buyers should treat registration portfolios, not unit price, as the primary negotiating asset. Currency volatility and 11.49% average applied tariffs mean landed-cost modelling must be built into every tender bid, and donor-funded channels (PEPFAR, Global Fund) impose documentation standards that many local formulators cannot yet meet.
The balance of evidence favors a volume-led, localization-first strategy over imported specialty plays. Africa's 4.32% CAGR is not a demand problem — it is a friction problem, and the players who remove friction (local registration, local fill-finish, donor-compliant quality systems) capture disproportionate margin. The strongest counter-argument is that biosimilars at 6.68% CAGR justify premium positioning; we accept the growth rate but note that affordability ceilings cap realizable price, making biosimilars a margin play only for firms with existing tender access.
Evidence that would change this conclusion: a sustained rise in public health budget allocation above GDP growth, or a harmonized African Medicines Agency registration pathway going live, would justify a faster, premium-segment-led entry strategy.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.32% from 2020-2034 |
| Segmentation |
|
The market is estimated at USD 6.43 billion and is projected to reach USD 9.29 billion by 2030, growing at a 4.32% CAGR. Growth is driven by chronic disease burden and constrained public health budgets.
South Africa leads with a 22.42% revenue share, supported by strong generic substitution, local manufacturing, and new product launches. Egypt and Nigeria are the next largest markets by estimated demand.
Biosimilars are the fastest-growing type at roughly 6.68% CAGR, while injectables are the fastest-growing route at about 8.0%. Simple generics remain the largest segment at 64.67% of revenue.
Key players include Aspen Holdings, Cipla South Africa, Lupin, Sun Pharmaceutical, Aurobindo Pharma, and Sandoz. Local manufacturing footprint and registration breadth are the strongest competitive moats.
Regulatory fragmentation across 54 markets, high production and API import costs, currency volatility, and an 11.49% average applied tariff all constrain growth. These frictions explain the market's slower CAGR versus global generics.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain: API and raw material suppliers, specialized generic manufacturers, contract formulators, and regional distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both supply-side capacity and demand-side procurement behaviour are captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Commercial & Procurement Leads | 35% |
| R&D and Technical Directors | 30% |
| Regulatory Affairs Managers | 22% |
| Supply Chain & Operations Heads | 13% |
| Company Type | Representation (%) |
|---|---|
| API & Raw Material Suppliers | 28% |
| Generic Manufacturers & Formulators | 37% |
| Regional Distributors & Wholesalers | 22% |
| Retail & Hospital Pharmacy Operators | 13% |
Estimates are benchmarked against official multilateral databases including UN Comtrade and WITS/World Bank trade statistics, national regulatory filings, corporate annual reports and investor presentations, and patent-expiry databases. Industry association publications and WHO prequalification records provide quality and compliance validation. No third-party market-research publisher data is used as a primary input.
We run simultaneous top-down modelling (macro healthcare expenditure and segment allocation) and bottom-up modelling (manufacturer capacity, product pricing, and end-use consumption). Divergences between the two are resolved through trade-flow reconciliation and expert review, producing a single validated base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |