 Us 3d Medical Imaging Devices Market
US 3D Medical Imaging Devices Market: 2025 Size & Outlook
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 252

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us 3d Medical Imaging Devices Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 4.260 B |
| 2025 | 4.600 B |
| 2026 | 4.960 B |
| 2027 | 5.350 B |
| 2028 | 5.780 B |
| 2029 | 6.230 B |
| 2030 | 6.720 B |

The US 3D medical imaging devices market covers hardware and software that generate three-dimensional anatomical representations for diagnosis, staging, treatment planning, and image-guided intervention. It spans CT, MRI, ultrasound, X-ray, and mammography systems plus reconstruction and visualization software sold to hospitals, imaging centers, and specialty clinics.
This report covers 3D-capable imaging hardware (CT, MRI, ultrasound, X-ray, mammography) and the reconstruction, visualization, and AI software attached to those modalities in the United States. It covers hospital, diagnostic imaging center, and specialty clinic end users.
This analysis does not cover conventional 2D-only radiography as a standalone category, nuclear medicine radiopharmaceuticals, contrast media consumables, picture archiving and communication systems sold independently of imaging hardware, or veterinary and dental-only imaging outside clinical diagnostic settings.
Published estimates for the US 3D medical imaging devices market range from about 4.05 Billion to 4.8 Billion for the 2022–2024 base period, with forecasts converging on 9.8 Billion to 10.1 Billion by the mid-2030s. The spread reflects differing treatment of software attach and mammography scope.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 4.8 Billion | 2022 | 2032 | 5.3% | 3D imaging devices, hardware-led, global report's US line | One published estimate |
| 4.05 Billion | 2024 | 2035 | 8.41% | US 3D devices, hardware and software, hospitals and imaging centers | A competing analysis |
| 5.19 Billion | 2026 | 2034 | 6.61% | Global 3D medical imaging, narrower software inclusion | A third published estimate |
| 9.85 Billion (forecast) | 2035 | — | 8.41% | US 3D devices, end-2035 projection | A competing analysis |
Our analysis suggests the 8.41% path is the most defensible for the US specifically. The faster rate is consistent with rising CT and MRI utilization, hospital capital budgets directed at AI-enabled replacement cycles, and the software attach that lower-CAGR estimates treat conservatively. The 5.3% figure likely understates the US because it is a global blended rate diluted by slower hardware-only markets.
The US 3D medical imaging devices market segments by device type, hardware modality, application, and end user. Hardware is the revenue anchor, but software and application mix determine margin and replacement velocity.
| Parent | Children |
|---|---|
| By Device Type | Hardware, Software |
| By Hardware Modality | X-ray devices, CT devices, MRI equipment, Ultrasound systems, Mammography systems |
| By Application | Oncology, Cardiology, Neurology, Gynecology and obstetrics, Orthopedics, Other applications |
| By End User | Hospitals, Diagnostic imaging centers, Other end users |
Hardware captured roughly 9 Billion globally in 2022, and the US hardware line likely represents about two-thirds of domestic revenue. Software is smaller but grows faster because AI reconstruction, automated segmentation, and cloud reading platforms carry higher recurring revenue and stickier contracts.
The South leads US 3D medical imaging device demand, driven by large hospital systems, rapid population growth, and heavy cancer and cardiac case volumes. The Northeast follows on academic medical centers and research-intensive oncology programs.
| Region | Market Share (%) |
|---|---|
| Northeast | 0.22% |
| South | 0.38% |
| Midwest | 0.21% |
| West | 0.19% |
This regional ordering is an analytical inference from population, cancer burden, and hospital density; the reference material does not publish state-level revenue splits. Vendors should treat the South as the priority territory for new placements and the Northeast as the priority for high-acuity, research-grade configurations.
Chronic disease burden, an aging population, and AI-enabled workflow gains are the primary growth engines, while capital cost, radiologist shortages, and regulatory complexity are the main brakes. The net effect is steady mid-to-high single-digit growth rather than a step change.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Rising chronic disease and aging population | Driver | High | Nearly 129 million Americans lived with a major chronic disease in 2025, sustaining imaging demand |
| AI reconstruction and workflow software | Driver | High | Shortens reading time, improves detection, and supports premium pricing |
| Minimally invasive and image-guided procedures | Driver | Moderate | Requires precise 3D planning and intraoperative guidance |
| Capital cost and maintenance burden | Restraint | High | Limits adoption at smaller and rural facilities |
| Radiologist and technologist shortages | Restraint | High | Caps throughput and delays return on scanner investment |
| Regulatory and reimbursement complexity | Restraint | Moderate | Lengthens procurement cycles and raises compliance overhead |
The US market is moderately consolidated, with Siemens Healthineers, GE HealthCare, and Philips Healthcare holding the broadest installed bases and Canon Medical Systems, Hologic, and Fujifilm competing strongly in specific modalities.
| Vendor | Primary strength | US positioning |
|---|---|---|
| Siemens Healthineers | MRI and CT, AI reconstruction | Broad tertiary-hospital installed base; strong oncology and neurology pull-through |
| GE HealthCare | MRI, CT, ultrasound, AI platform | Deep hospital relationships and service network; SIGNA and Revolution lines |
| Philips Healthcare | CT, ultrasound, informatics | Strong in cardiology and workflow integration |
| Canon Medical Systems | CT and orthopedic 3D X-ray | Niche leadership in orthopedics and dose-reduction |
| Hologic | 3D mammography | Dominant in US breast screening networks |
| Fujifilm | CT, MRI, and imaging IT | Growing through value-tier and enterprise IT bundling |
The moat is no longer the scanner alone. Service contracts, software upgrades, and data integration create switching costs that lock buyers in for seven to ten years.
Buyers should prioritize total cost of ownership over sticker price, because service, software licenses, and upgrade paths typically exceed the initial capital outlay across a seven-year cycle. Scanners with open interoperability standards reduce long-term lock-in and ease integration with enterprise imaging records.
Procurement risk concentrates in three areas: AI claims that lack regulatory clearance for the specific clinical use, service-level agreements that exclude software updates, and configuration choices that limit future modality expansion. Buyers should require written clarity on FDA clearance scope, upgrade pricing, and data export rights before signing.
Regulatory compliance matters most for mammography and CT dose reporting, where facility accreditation and documentation requirements are strict. Operators should also model radiologist reading capacity, since a scanner without reading throughput produces no diagnostic revenue.
The balance of evidence favors the 8.4% growth path for the US, not the 5.3% global blend. The US combines the highest imaging utilization in the OECD, concentrated chronic disease burden, and the fastest AI software attach, all of which push domestic growth above the global average. The strongest counter-argument is capital budget fatigue: if hospital margins compress, replacement cycles lengthen and the higher CAGR will not materialize.
Second-order effects matter here. AI software is the margin pool, but it depends on interoperable data and radiologist adoption; vendors that sell scanners without credible workflow integration will win placements but lose the upgrade cycle. Similarly, the South's growth will reward vendors with strong service coverage, not just product breadth.
What would change this conclusion: a sustained decline in hospital capital spending or reimbursement cuts to advanced imaging would push the market toward the 5.3% path. We would also revise downward if AI software clearances stall.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
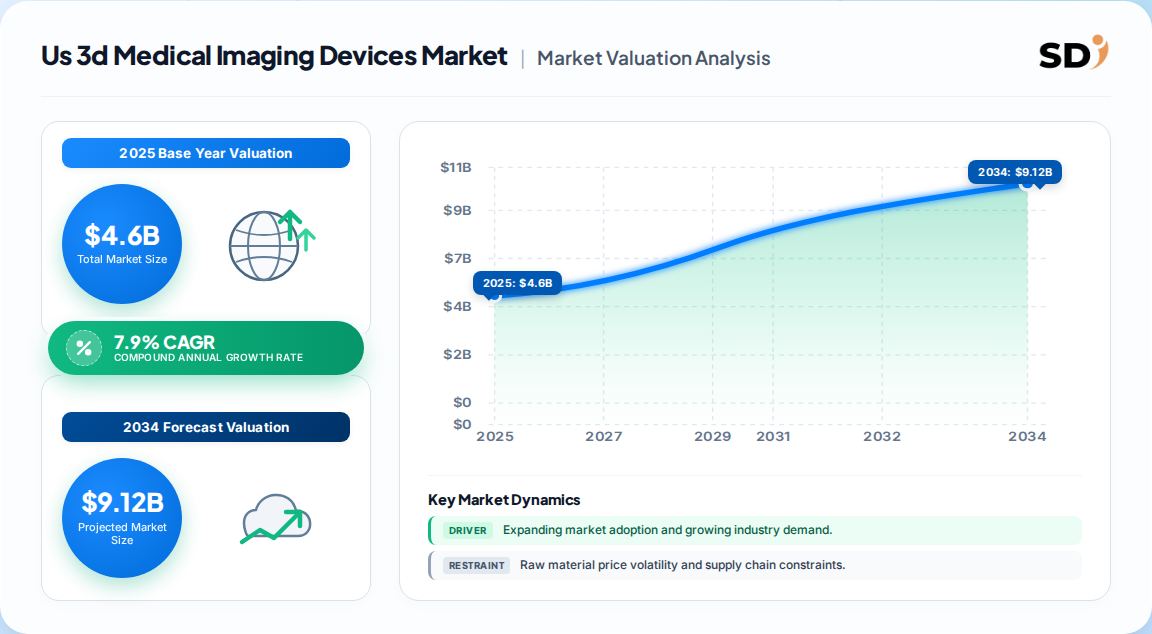
The US market is estimated at roughly 4.6 Billion in 2025. Published estimates range from about 4.05 Billion to 4.8 Billion for the 2022–2024 base period, reflecting differences in software and mammography inclusion.
Forecasts range from 5.3% to 8.41% depending on scope. Our analysis favors the higher end, roughly 7.9%, because US imaging utilization and AI software attach exceed the global average.
Hardware leads with roughly 70% of revenue, anchored by CT and MRI systems. Oncology is the leading clinical application at about 34–38% share, followed by cardiology and neurology.
Siemens Healthineers, GE HealthCare, and Philips Healthcare hold the broadest installed bases. Canon Medical, Hologic, and Fujifilm compete strongly in specific modalities such as orthopedic 3D X-ray and 3D mammography.
The South leads on hospital expansion and population growth, followed by the Northeast on academic medical centers. This ordering is an analytical inference, as state-level revenue splits are not published.
Capital cost, maintenance burden, and radiologist and technologist shortages cap throughput and slow return on investment. Regulatory and reimbursement complexity also lengthens procurement cycles, especially for smaller facilities.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct verification of installed base, pricing, and procurement behavior. We conducted in-depth interviews with stakeholders across the imaging value chain: component and detector suppliers, original equipment manufacturers, imaging software and reconstruction developers, hospital group purchasing organizations, and independent diagnostic imaging center operators. Interviewees included VP-level sourcing and procurement leads, radiology department directors, biomedical engineering heads, and commercial operations executives responsible for capital equipment planning.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| Radiology & Clinical Directors | 30% |
| Biomedical Engineering Heads | 20% |
| Commercial Operations Executives | 15% |
| Company Type | Representation (%) |
|---|---|
| Imaging OEMs & System Integrators | 40% |
| Component & Detector Suppliers | 25% |
| Imaging Software & AI Developers | 20% |
| Hospital GPOs & Imaging Center Operators | 15% |
We triangulate interview findings against official multilateral and regulatory data, including UN Comtrade and WTO trade statistics for imaging equipment flows, US International Trade Commission filings, and Eurostat healthcare resource data for cross-market context. Corporate annual filings (10-K and investor presentations), FDA clearance databases, patent filings, and recognized technical standards from bodies such as NEMA and IEC inform device specifications and regulatory scope. No competitor market research publications are used as validation sources.
We run simultaneous top-down and bottom-up models. The top-down path allocates national healthcare capital expenditure and imaging procedure volumes across modalities and end users. The bottom-up path builds from manufacturer revenue, unit pricing, and installation capacity by modality and region, then reconciles both against trade and regulatory data.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |