Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Pet Supplements Market Size, Growth & 2035 Forecast
Pet Supplements Market
Pet Supplements Market Size, Growth & 2035 Forecast
Pet Supplements Market by Type (Over-the-counter, Prescription), by Pet Type (Dogs, Cats, Other companion animals), by Form (Chewables, Powders, Tablets, Liquids, Soft chews), by Function (Hip & joint, Digestive health, Skin & coat, Calming/behavioral, Immunity, Cognitive), by Distribution Channel (Offline, Online/D2C), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 220
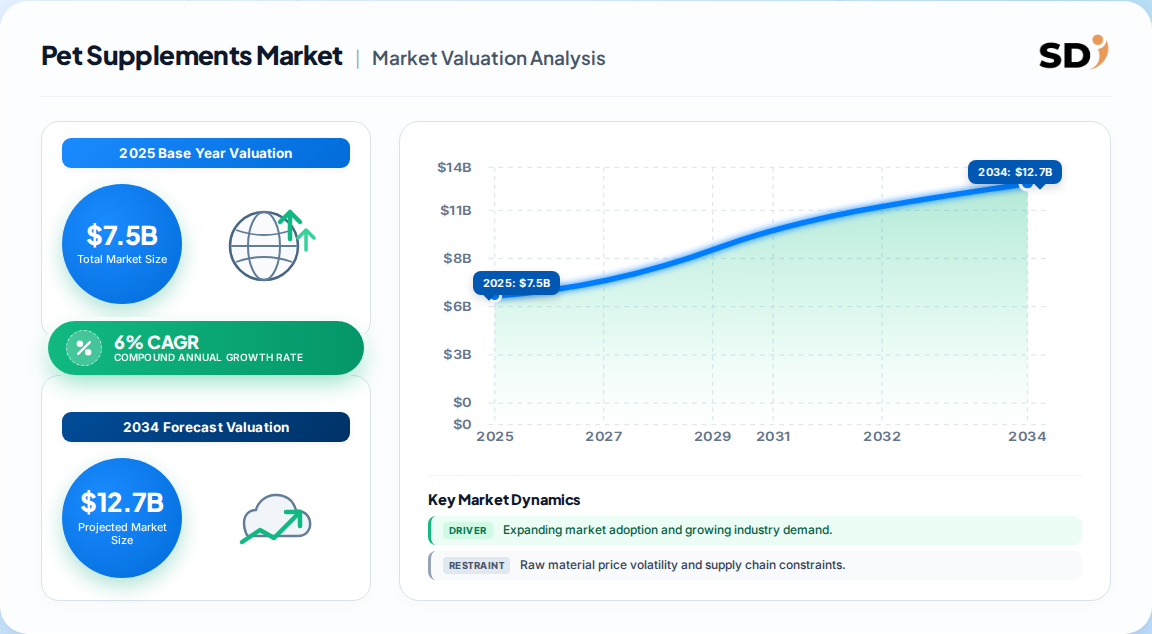
The global pet supplements market was valued at 7.50 Billion in 2025, with a base-case forecast to 13.43 Billion by 2035.
The category expands at a 6% CAGR (2026–2035), with 2026 estimated at 7.95 Billion.
North America dominates with roughly 44% revenue share; Asia Pacific is the fastest-growing region.
Over-the-counter products command 86.5% of type share, chewables 69.8% of form share, and dogs 63.1% of pet-type share in 2025.
Leading vendors include Nestlé Purina PetCare (11.5% share), Mars Petcare, Nutramax Laboratories, Swedencare, and Zesty Paws; the top five hold 32% combined.
Why this matters for decision-makers: Vendors must pivot from generalized wellness SKUs to condition-specific, subscription-backed regimens to avoid margin compression and capture repeat-purchase economics.
Pet Supplements Market Size (In Billion)
15.0B
10.0B
5.0B
0
7.500 B
2025
7.950 B
2026
8.430 B
2027
8.930 B
2028
9.470 B
2029
10.04 B
2030
10.64 B
2031
Pet Supplements Market Size (In Billion)
Year
Market Size
2025
7.500 B
2026
7.950 B
2027
8.430 B
2028
8.930 B
2029
9.470 B
2030
10.04 B
2031
10.64 B
What is the Pet Supplements Market?
The pet supplements market covers orally administered nutritional and functional products—vitamins, minerals, fatty acids, probiotics, joint compounds, and calming botanicals—formulated for companion animals to support preventive health, recovery, and quality of life alongside conventional feed.
Scope: what this report covers and excludes
This analysis covers global demand for canine, feline, and other-companion-animal supplements across OTC and prescription channels, all delivery forms, function categories, and distribution formats. This analysis does not cover veterinary pharmaceuticals, medicated feed additives, pet food as a primary nutrition category, or animal-health biologics and vaccines.
How big is the market for Pet Supplements Market?
Estimates diverge materially because publishers define the category boundary differently—some net out prescription products, medicated blends, or functional treats. The most defensible base case is the higher-coverage 7.50 Billion 2025 figure, corroborated by APPA survey data showing 53% of U.S. dog owners already administer supplements.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
7.50 Billion
2025
2035
6%
Full category incl. OTC, prescription, all forms
One published industry estimate
2.80 Billion
2025
2033
6.9%
Narrower definition, likely netting medicated and treat-blended lines
A competing analysis
Our analysis suggests the ~2.7x gap is a definitional artifact, not a demand contradiction: the lower estimate likely excludes vet-channel scripts and functional treat hybrids. The implied direction—mid-to-high single-digit growth—is consistent across sources, which is what matters for capacity planning.
How is the market segmented?
Segmentation is best read as a stack of four lenses—type, pet species, form, and function—layered over distribution channel. Each lens carries a sharp concentration signal that should guide portfolio and shelf decisions.
North America leads with roughly 44% of global revenue in 2025, anchored by high supplement penetration among U.S. dog owners. Asia Pacific is the fastest-growing region, propelled by rising pet ownership, urbanization, and digital-channel expansion.
Pet Supplements Market Regional Market Share
Loading chart...
Pet Supplements Market Regional Market Share
Region
Market Share (%)
North America
0.44%
Europe
0.24%
Asia Pacific
0.22%
Latin America
0.06%
Middle East & Africa
0.04%
North America (USA, Canada, Mexico)
USA
Canada
Mexico
Europe (Germany, UK, France, Italy, Spain)
Germany
UK
France
Italy
Asia Pacific (China, Japan, India, South Korea, Australia)
China
Japan
India
South Korea
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
Region
2025 Revenue Share
North America
44%
Europe
24%
Asia Pacific
22%
Latin America
6%
Middle East & Africa
4%
The divergence between North America's share dominance and Asia Pacific's growth rate implies a two-speed market: incumbents defend premium pricing in mature markets while challengers build volume in price-sensitive digital-first markets.
What is driving growth — and what is holding it back?
Growth is driven by pet humanization, preventive-care behavior, e-commerce subscription economics, and veterinary-guided personalization. Restraints are awareness gaps (only 32% of U.S. cat owners supplement), mass-retail deceleration, and post-MOU regulatory uncertainty on novel ingredients.
Factor
Direction
Evidence strength
Mechanism
Pet humanization & premiumization
Driver
High (APPA 53% dog-owner adoption)
Raises daily preventive spend and average transaction value
E-commerce & D2C subscription
Driver
High (9.6% CAGR projected)
Widens reach and locks in replenishment revenue
Personalized/AI-guided nutrition
Driver
Medium
Supports premium price realization and vet endorsement
Slows novel-ingredient line extensions early in forecast
The balance favors growth, but the composition matters: demand is converting from occasional remedy purchases to recurring regimens. This shift rewards brands with palatable formats and credible clinical claims, and punishes undifferentiated mass-market SKUs.
Who are the leading vendors?
Nestlé Purina PetCare leads with over 11.5% share, while the top five—including Mars Petcare, Nutramax Laboratories, Swedencare, and Zesty Paws—hold a combined 32%, indicating a fragmented but consolidating field.
Company
Positioning
Approx. Share (2025)
Moat
Nestlé Purina PetCare
Broad portfolio, vet & retail reach
11.5%+
Brand trust, distribution scale
Mars Petcare
Multi-brand, global footprint
Top-5
Channel control, R&D depth
Nutramax Laboratories
Clinical/vet-channel specialist
Top-5
Veterinary endorsement
Swedencare AB
Premium specialty portfolio
Top-5
Acquisition-led brand stack
Zesty Paws
DTC/digital-native
Top-5
Subscription base, agility
Differentiation rests on clinical credibility and repeat-purchase mechanics rather than price. The 68% held by non-top-five players signals room for niche brands, but rising ingredient-review scrutiny will favor those with regulatory-ready formulations.
What do buyers and operators need to know?
Selection should hinge on four criteria: substantiated efficacy claims, ingredient traceability, palatability/format compliance, and channel fit. Procurement risk concentrates in novel ingredients—postbiotics, colostrum derivatives, botanicals—where the FDA-AAFCO transition may lengthen approval pathways.
Switching costs are moderate for consumers but high for brands locked into contract formulators and single-origin supply. Regulatory compliance is non-negotiable: EU imports require approved establishments and health certification under Regulation 2017/625, and U.S. labels must align with evolving AAFCO/FDA guidance. Buyers should pressure-test supplier documentation before committing to multi-year supply.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors the higher 7.50 Billion base case and mid-single-digit growth, but the strategic story is mix shift, not headline size. Condition-specific, subscription-backed regimens are the profit pool; generalized wellness SKUs face commoditization. Our analysis suggests vendors that pair clinical validation with autoship economics will outgrow the category.
The strongest counter-argument is adoption ceiling: with only 32% of U.S. cat owners supplementing and mass retail decelerating, growth could undershoot if conversion stalls. We weight this risk as moderate—digital education and vet recommendation are actively closing the gap.
Investors: Prioritize assets with recurring-revenue mechanics and vet-channel credibility over broad-portfolio generalists.
Operators: Reallocate shelf and marketing spend toward hip & joint, digestive, and calming formats in chewable delivery.
Brands: Build regulatory-ready formulation pipelines now to avoid post-MOU launch delays.
Evidence that would change our conclusion: sustained sub-4% mass-retail growth combined with flat cat-owner adoption through 2027 would signal a lower structural ceiling and warrant a downward revision.
Pet Supplements Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Pet Supplements Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 6% from 2020-2034
Segmentation
By Type
Over-the-counter
Prescription
By Pet Type
Dogs
Cats
Other companion animals
By Form
Chewables
Powders
Tablets
Liquids
Soft chews
By Function
Hip & joint
Digestive health
Skin & coat
Calming/behavioral
Immunity
Cognitive
By Distribution Channel
Offline
Online/D2C
By Geography
North America
USA
Canada
Mexico
Europe
Germany
UK
France
Italy
Spain
Asia Pacific
China
Japan
India
South Korea
Australia
Latin America
Brazil
Mexico
Argentina
Middle East & Africa
Saudi Arabia
UAE
South Africa
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Type
5.1.1. Over-the-counter
5.1.2. Prescription
5.2. Market Analysis, Insights and Forecast - by Pet Type
5.2.1. Dogs
5.2.2. Cats
5.2.3. Other companion animals
5.3. Market Analysis, Insights and Forecast - by Form
5.3.1. Chewables
5.3.2. Powders
5.3.3. Tablets
5.3.4. Liquids
5.3.5. Soft chews
5.4. Market Analysis, Insights and Forecast - by Function
5.4.1. Hip & joint
5.4.2. Digestive health
5.4.3. Skin & coat
5.4.4. Calming/behavioral
5.4.5. Immunity
5.4.6. Cognitive
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Offline
5.5.2. Online/D2C
5.6. Market Analysis, Insights and Forecast - by Region
5.6.1. North America
5.6.2. Europe
5.6.3. Asia Pacific
5.6.4. Latin America
5.6.5. Middle East & Africa
6. North America Market Analysis, Insights and Forecast, 2020-2034
6.1. Market Analysis, Insights and Forecast - by Type
6.1.1. Over-the-counter
6.1.2. Prescription
6.2. Market Analysis, Insights and Forecast - by Pet Type
6.2.1. Dogs
6.2.2. Cats
6.2.3. Other companion animals
6.3. Market Analysis, Insights and Forecast - by Form
6.3.1. Chewables
6.3.2. Powders
6.3.3. Tablets
6.3.4. Liquids
6.3.5. Soft chews
6.4. Market Analysis, Insights and Forecast - by Function
6.4.1. Hip & joint
6.4.2. Digestive health
6.4.3. Skin & coat
6.4.4. Calming/behavioral
6.4.5. Immunity
6.4.6. Cognitive
6.5. Market Analysis, Insights and Forecast - by Distribution Channel
6.5.1. Offline
6.5.2. Online/D2C
7. Europe Market Analysis, Insights and Forecast, 2020-2034
7.1. Market Analysis, Insights and Forecast - by Type
7.1.1. Over-the-counter
7.1.2. Prescription
7.2. Market Analysis, Insights and Forecast - by Pet Type
7.2.1. Dogs
7.2.2. Cats
7.2.3. Other companion animals
7.3. Market Analysis, Insights and Forecast - by Form
7.3.1. Chewables
7.3.2. Powders
7.3.3. Tablets
7.3.4. Liquids
7.3.5. Soft chews
7.4. Market Analysis, Insights and Forecast - by Function
7.4.1. Hip & joint
7.4.2. Digestive health
7.4.3. Skin & coat
7.4.4. Calming/behavioral
7.4.5. Immunity
7.4.6. Cognitive
7.5. Market Analysis, Insights and Forecast - by Distribution Channel
7.5.1. Offline
7.5.2. Online/D2C
8. Asia Pacific Market Analysis, Insights and Forecast, 2020-2034
8.1. Market Analysis, Insights and Forecast - by Type
8.1.1. Over-the-counter
8.1.2. Prescription
8.2. Market Analysis, Insights and Forecast - by Pet Type
8.2.1. Dogs
8.2.2. Cats
8.2.3. Other companion animals
8.3. Market Analysis, Insights and Forecast - by Form
8.3.1. Chewables
8.3.2. Powders
8.3.3. Tablets
8.3.4. Liquids
8.3.5. Soft chews
8.4. Market Analysis, Insights and Forecast - by Function
8.4.1. Hip & joint
8.4.2. Digestive health
8.4.3. Skin & coat
8.4.4. Calming/behavioral
8.4.5. Immunity
8.4.6. Cognitive
8.5. Market Analysis, Insights and Forecast - by Distribution Channel
8.5.1. Offline
8.5.2. Online/D2C
9. Latin America Market Analysis, Insights and Forecast, 2020-2034
9.1. Market Analysis, Insights and Forecast - by Type
9.1.1. Over-the-counter
9.1.2. Prescription
9.2. Market Analysis, Insights and Forecast - by Pet Type
9.2.1. Dogs
9.2.2. Cats
9.2.3. Other companion animals
9.3. Market Analysis, Insights and Forecast - by Form
9.3.1. Chewables
9.3.2. Powders
9.3.3. Tablets
9.3.4. Liquids
9.3.5. Soft chews
9.4. Market Analysis, Insights and Forecast - by Function
9.4.1. Hip & joint
9.4.2. Digestive health
9.4.3. Skin & coat
9.4.4. Calming/behavioral
9.4.5. Immunity
9.4.6. Cognitive
9.5. Market Analysis, Insights and Forecast - by Distribution Channel
9.5.1. Offline
9.5.2. Online/D2C
10. Middle East & Africa Market Analysis, Insights and Forecast, 2020-2034
10.1. Market Analysis, Insights and Forecast - by Type
10.1.1. Over-the-counter
10.1.2. Prescription
10.2. Market Analysis, Insights and Forecast - by Pet Type
10.2.1. Dogs
10.2.2. Cats
10.2.3. Other companion animals
10.3. Market Analysis, Insights and Forecast - by Form
10.3.1. Chewables
10.3.2. Powders
10.3.3. Tablets
10.3.4. Liquids
10.3.5. Soft chews
10.4. Market Analysis, Insights and Forecast - by Function
10.4.1. Hip & joint
10.4.2. Digestive health
10.4.3. Skin & coat
10.4.4. Calming/behavioral
10.4.5. Immunity
10.4.6. Cognitive
10.5. Market Analysis, Insights and Forecast - by Distribution Channel
10.5.1. Offline
10.5.2. Online/D2C
11. Competitive Analysis
11.1. Company Profiles
11.2. Market Entropy
11.2.1. Company's Key Areas Served
11.2.2. Recent Developments
11.3. Company Market Share Analysis, 2026
11.3.1. Top 5 Companies Market Share Analysis
11.3.2. Top 3 Companies Market Share Analysis
11.4. List of Potential Customers
12. Research Methodology
List of Figures
Figure 1: Pet Supplements Market Revenue Breakdown (Billion, %) by Region 2026 & 2034
Figure 2: North America Pet Supplements Market Revenue (Billion), by Type 2026 & 2034
Figure 3: North America Pet Supplements Market Revenue Share (%), by Type 2026 & 2034
Figure 4: North America Pet Supplements Market Revenue (Billion), by Pet Type 2026 & 2034
Figure 5: North America Pet Supplements Market Revenue Share (%), by Pet Type 2026 & 2034
Figure 6: North America Pet Supplements Market Revenue (Billion), by Form 2026 & 2034
Figure 7: North America Pet Supplements Market Revenue Share (%), by Form 2026 & 2034
Figure 8: North America Pet Supplements Market Revenue (Billion), by Function 2026 & 2034
Figure 9: North America Pet Supplements Market Revenue Share (%), by Function 2026 & 2034
Figure 10: North America Pet Supplements Market Revenue (Billion), by Distribution Channel 2026 & 2034
Figure 11: North America Pet Supplements Market Revenue Share (%), by Distribution Channel 2026 & 2034
Figure 12: North America Pet Supplements Market Revenue (Billion), by Country 2026 & 2034
Figure 13: North America Pet Supplements Market Revenue Share (%), by Country 2026 & 2034
Figure 14: Europe Pet Supplements Market Revenue (Billion), by Type 2026 & 2034
Figure 15: Europe Pet Supplements Market Revenue Share (%), by Type 2026 & 2034
Figure 16: Europe Pet Supplements Market Revenue (Billion), by Pet Type 2026 & 2034
Europe Pet Supplements Market Revenue Share (%), by Pet Type 2026 & 2034
List of Tables
Table 1: Pet Supplements Market Revenue Billion Forecast, by Type 2020 & 2034
Table 2: Pet Supplements Market Revenue Billion Forecast, by Pet Type 2020 & 2034
Table 3: Pet Supplements Market Revenue Billion Forecast, by Form 2020 & 2034
Table 4: Pet Supplements Market Revenue Billion Forecast, by Function 2020 & 2034
Table 5: Pet Supplements Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Pet Supplements Market Revenue Billion Forecast, by Region 2020 & 2034
Table 7: North America Pet Supplements Market Revenue Billion Forecast, by Type 2020 & 2034
Table 8: North America Pet Supplements Market Revenue Billion Forecast, by Pet Type 2020 & 2034
Table 9: North America Pet Supplements Market Revenue Billion Forecast, by Form 2020 & 2034
Table 10: North America Pet Supplements Market Revenue Billion Forecast, by Function 2020 & 2034
Table 11: North America Pet Supplements Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 12: North America Pet Supplements Market Revenue Billion Forecast, by Country 2020 & 2034
Table 13: USA Pet Supplements Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 14: Canada Pet Supplements Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 15: Mexico Pet Supplements Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 16: Europe Pet Supplements Market Revenue Billion Forecast, by Type 2020 & 2034
Frequently Asked Questions
1. How big is the pet supplements market in 2025?
The global pet supplements market was valued at approximately 7.50 Billion in 2025, with a base-case projection to reach 13.43 Billion by 2035 at a 6% CAGR.
2. Which region leads the pet supplements market?
North America leads with roughly 44% of global revenue in 2025, while Asia Pacific is the fastest-growing region, supported by rising pet ownership and e-commerce expansion.
3. What are the most popular pet supplement types?
Over-the-counter products dominate with 86.5% share, chewables lead form with 69.8%, and hip & joint is the largest function at 21.6% in 2025.
4. Who are the leading pet supplement companies?
Nestlé Purina PetCare leads with over 11.5% share; Mars Petcare, Nutramax Laboratories, Swedencare, and Zesty Paws complete the top five at 32% combined.
5. What is driving pet supplement market growth?
Pet humanization, preventive-care behavior, e-commerce subscriptions, and veterinary-guided personalization are the primary growth drivers, offset by low cat-owner adoption and regulatory uncertainty.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct stakeholder engagement over desk synthesis. In-depth interviews span the value chain: raw material and ingredient suppliers, specialized supplement producers, contract formulators, and global distributors. Decision-maker designations include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring both supply-side capacity and demand-side pricing signals are captured.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Leads
30%
R&D & Technical Directors
35%
Commercial Operations Leads
20%
Regulatory Affairs Managers
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Ingredient & Raw Material Suppliers
30%
Specialized Supplement Producers
35%
Contract Formulators & Blenders
20%
Global Distributors & Retailers
15%
Secondary Benchmarking & Public Trade Validation
We triangulate primary findings against official multilateral databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and SEC 10-K disclosures, patent databases, and recognized non-profit technical standards and industry associations. No competitor market-research publications are used as validation sources.
Demand Modeling & Market Sizing Triangulation
Sizing runs simultaneously Top-Down (macroeconomic and segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption modeling). Divergences between the two are reconciled through elasticity testing and channel-level checks.
 Pet Supplements Market