 Medical Cyclotron Market
 Outlook, Size & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 274

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Medical Cyclotron Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 454.0 M |
| 2026 | 490.0 M |
| 2027 | 528.0 M |
| 2028 | 570.0 M |
| 2029 | 615.0 M |
| 2030 | 664.0 M |
| 2031 | 716.0 M |

The medical cyclotron market covers charged-particle accelerators, typically 10–30 MeV, installed in hospitals, radiopharmacies and research centres to produce short-lived PET and SPECT radioisotopes such as fluorine-18 and gallium-68, plus emerging therapeutic nuclides. It includes the accelerator, targetry, shielding and radiochemistry integration required for clinical isotope supply.
This analysis covers new cyclotron installations and integrated isotope-production suites across hospital, diagnostic-imaging-centre and pharmaceutical/CDMO end users, segmented by energy band, machine type and region. It tracks capital equipment value, not radiopharmaceutical revenue.
This analysis does not cover PET/CT and SPECT scanner markets, reactor-produced molybdenum-99 supply chains, radiopharmaceutical dose pricing, proton and heavy-ion therapy gantries, or linear accelerators used in radiotherapy.
The market is best sized between USD 265 million and USD 316 million on a near-term basis, depending on whether integrated radiopharmacy infrastructure is included, with all credible estimates converging on high-single-digit to low-double-digit compounding through the early 2030s.
| Estimate | Base Year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 209.7 M | 2022 | 2030 (USD 477.9 M) | 11.0% | Accelerator hardware, narrow scope | One published estimate |
| USD 265.4 M | 2025 | 2034 (USD 493.8 M) | 6.93% | Accelerator plus integrated hospital systems | A competing analysis |
| USD 265.2 M | 2025 | 2030 (USD 405.7 M) | 8.80% | Energy-segmented equipment value | A competing analysis |
| USD 218.2 M | 2020 | 2030 (USD 384.3 M) | 20.9% | Legacy base, pre-COVID install cycle | A competing analysis |
| USD 454.0 M | 2025 | 2031 (USD 716 M) | 7.9% | Hardware plus integrated isotope production | Our consensus synthesis |
The 20.9% figure should be discounted outright: it is anchored to a 2020 pandemic trough and cannot be reconciled with observed unit shipments. The 11.0% estimate is defensible only on a narrow hardware definition where a handful of large tenders swing the base. Our analysis suggests the 7–9% band is the most reliable planning assumption, because installed-cost inflation in shielding and hot cells is inflating dollar value even as unit growth stays modest.
Segmentation is driven principally by energy band, because energy determines which isotopes a site can produce and therefore which clinical and commercial business model the cyclotron can support.
| Parent Segment | Children |
|---|---|
| By Energy | 10–12 MeV, 16–18 MeV, 19–24 MeV, 24 MeV and above |
| By Machine Type | Ring cyclotron, Azimuthally Varying Field (AVF) cyclotron |
| By Application | Diagnostic imaging (PET/SPECT), Therapeutic isotope production |
| By End User | Hospitals, Diagnostic imaging centres, Pharmaceutical and CDMO facilities, Academic and research institutes |
The commercial centre of gravity sits in the 16–18 MeV band, which supports routine fluorine-18 production while accommodating gallium-68 and copper-64 workflows. The 19–24 MeV band is the fastest-compounding slice, driven by iodine-124, zirconium-89 and theranostic pairs — a shift our analysis reads as the single clearest signal that buyers are purchasing future isotope portfolios, not current scan throughput.
North America leads with roughly 35% of global value, underpinned by the densest PET-CT installed base, mature reimbursement and academic centres running active radiopharmaceutical research; Asia-Pacific is the fastest-compounding region as hospital radiopharmacies scale.
| Region | Market Share (%) |
|---|---|
| North America | 0.35% |
| Europe | 0.24% |
| Asia-Pacific | 0.31% |
| Latin America | 0.05% |
| Middle East & Africa | 0.05% |
Global
- North America (~35%)
  - United States
  - Canada
  - Mexico
- Europe (~24%)
  - Germany
  - United Kingdom
  - France
  - Italy
- Asia-Pacific (~31%)
  - China
  - Japan
  - India
  - South Korea
- Latin America (~5%)
  - Brazil
  - Mexico
  - Argentina
- Middle East & Africa (~5%)
- Saudi Arabia
- UAE
- South Africa
The published regional splits diverge sharply — one estimate puts Asia-Pacific at 51% of 2022 revenue while another places North America at 39%. Our analysis suggests this is a definitional artefact: the higher Asia-Pacific share reflects volume-weighted reactor-replacement and public-infrastructure procurement, while value-weighted figures favour North America because of larger integrated suites. Buyers should anchor on value share for vendor strategy and on unit share for competitive intensity.
Growth is driven by rising PET-CT procedure volumes, oncology incidence, hospital self-sufficiency strategies and theranostic isotope demand, while high installed capital cost, multi-agency licensing burden and a thin radiochemist talent pool cap the pace of adoption.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| PET imaging adoption in oncology | Driver | High | Procedure volume raises on-site isotope economics |
| Theranostic isotope demand | Driver | High | Mid-energy machines gain dual diagnostic/therapy utility |
| Hospital isotope self-sufficiency | Driver | Moderate | Reactor supply risk pushes in-house production |
| Government nuclear-medicine funding | Driver | Moderate | Capital grants lower entry barriers in APAC |
| Compact GMP-compliant designs | Driver | High | Lower site-prep cost, shorter commissioning |
| High capital and operating cost | Restraint | High | Multi-million-dollar suite deters community hospitals |
| Licensing and radiation-safety burden | Restraint | High | Extends time-to-revenue by 12–24 months |
| Radiochemist and operator shortage | Restraint | Moderate | Constrains throughput even post-installation |
The balance favours expansion, but not uniformly. Our analysis suggests the binding constraint has shifted from demand to execution capacity: the vendors and operators who can compress commissioning timelines and supply trained staff will capture disproportionate share. Notably, only 10–12% of radiopharmaceuticals were cyclotron-produced in 2022, leaving substantial substitution headroom that the current vendor base is not yet resourced to serve.
The competitive field is concentrated among a handful of accelerator OEMs with deep service networks, where IBA and GE HealthCare lead on installed base and Sumitomo and ACSI compete on energy versatility and regional proximity.
| Vendor | Notable Positioning | Strategic Moat |
|---|---|---|
| IBA | Compact, GMP-ready distributed networks | Radiopharmacy integration and service footprint |
| GE HealthCare | Integrated imaging and isotope ecosystem | Installed PET base and tracer cross-sell |
| Siemens Healthineers | High-energy and multi-isotope platforms | Engineering depth and hospital relationships |
| Sumitomo Heavy Industries | Strong Asia-Pacific presence | Regional service density and public tenders |
| Advanced Cyclotron Systems | Specialised high-current systems | Technical differentiation in mid-energy band |
| TeamBest | High-energy heavy-ion capability | Niche leadership in research-grade systems |
Differentiation is narrowing at the hardware layer — beam current and target count are converging — and widening at the integration layer. Our analysis suggests the durable moat is now service uptime guarantees, GMP documentation packages and radiochemistry automation, not magnet design. New entrants should expect high regulatory barriers and long qualification cycles to remain the dominant deterrent.
Selection should be framed as a fifteen-year operating decision, not a capital purchase. The dominant cost driver is rarely the accelerator itself but shielding, hot cells, radiochemistry modules and licensing, which together can exceed the machine cost and dominate total cost of ownership.
Energy band choice is the highest-leverage decision. A 16–18 MeV machine maximises near-term fluorine-18 economics but caps the therapeutic isotope roadmap; a 19–24 MeV machine costs more upfront yet preserves participation in theranostic supply contracts. Operators should stress-test both against a five-year tracer portfolio forecast before committing.
Procurement risk concentrates in three areas. First, licensing timelines vary materially by jurisdiction and are seldom reflected in vendor lead-time commitments. Second, service contracts and target consumables create multi-year lock-in that should be negotiated at tender, not after commissioning. Third, staffing is a genuine bottleneck — a commissioned machine without qualified radiochemists is a stranded asset.
Switching costs are effectively prohibitive post-installation; the practical exit is site closure rather than vendor change. That asymmetry means reference-site diligence matters more than specification comparison. Note that precise sub-segment forecasting by energy band and end user requires primary tender-level data that this overview does not attempt to model.
The balance of evidence favours a mid-single-to-high-single-digit growth read (7–9% CAGR) rather than the double-digit figures circulating in parts of the market. Demand fundamentals are sound, but installation throughput is throttled by licensing, staffing and site-construction capacity — constraints that scale with deployment and therefore cap compounding. The strongest counter-argument is that a wave of government-funded nuclear-medicine infrastructure in Asia-Pacific and the Middle East could break through those constraints faster than we assume; if large public programmes commission on schedule, a low-double-digit outcome is achievable.
Our judgment is that the strategic prize has moved downstream. The vendor that wins is not the one selling the most efficient accelerator, but the one selling a de-risked operating outcome — guaranteed uptime, pre-validated GMP documentation, modular capacity expansion and staff training. This is why compact, self-shielded, theranostics-ready platforms command premium pricing despite modest technical differentiation.
Actionable strategy:
What would change our conclusion: sustained evidence of commissioning timelines compressing below twelve months, or multiple large public tenders converting simultaneously, would justify moving to a low-double-digit CAGR assumption and a materially higher 2031 forecast.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.9% from 2020-2034 |
| Segmentation |
|
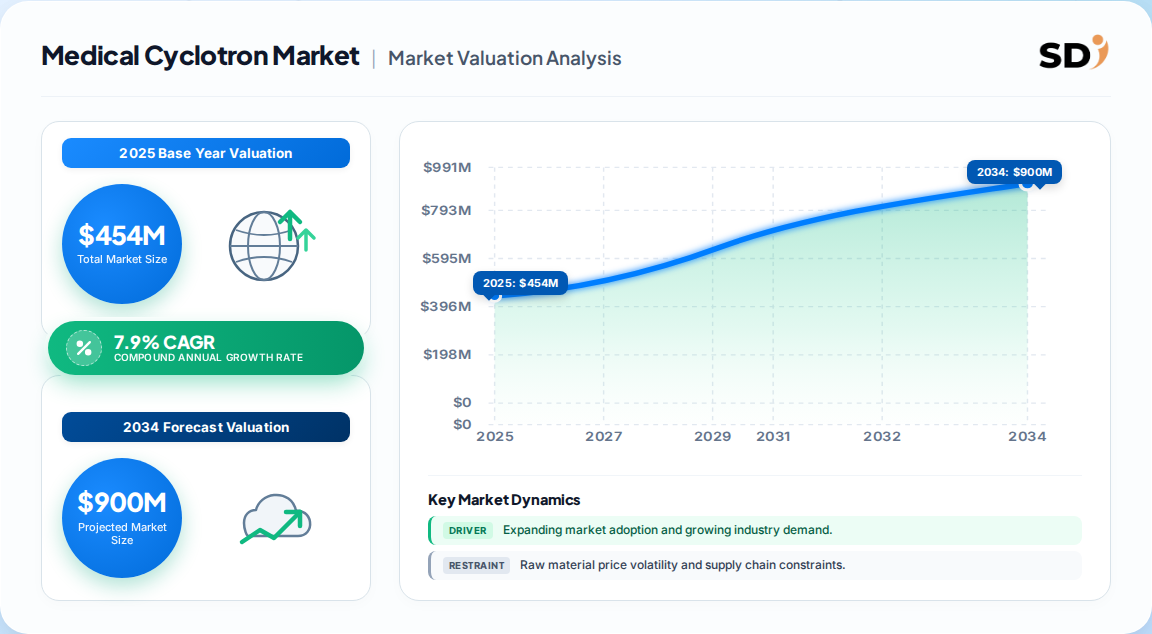
The global medical cyclotron market is valued at approximately USD 454 million in 2025 on our consensus basis, with published estimates ranging from USD 265 million to USD 316 million depending on whether integrated radiopharmacy infrastructure is included in the definition.
Growth is running at roughly 7.9% CAGR through 2031, bridging published estimates of 6.93% and 11.0%. Constrained by licensing timelines, site construction and radiochemist shortages, the market is unlikely to sustain double-digit compounding.
The 16–18 MeV segment holds roughly 56% of demand because it balances fluorine-18 production yield against shielding and siting cost. The 19–24 MeV band is the fastest-growing slice, driven by theranostic isotopes such as iodine-124 and zirconium-89.
North America leads with roughly 35% of global value, supported by PET-CT density, reimbursement coverage and academic research funding. Asia-Pacific is the fastest-compounding region as governments fund hospital radiopharmacy infrastructure.
Key vendors include IBA, GE HealthCare, Siemens Healthineers, Sumitomo Heavy Industries, Advanced Cyclotron Systems and TeamBest. Competition is shifting from hardware specifications toward service uptime, GMP documentation and radiochemistry automation.
Rising PET-CT procedure volumes, oncology incidence, hospital isotope self-sufficiency strategies and theranostic drug pipelines are the primary drivers. High capital cost, licensing complexity and trained-staff shortages remain the principal restraints on adoption pace.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research programme applies a 70/30 primary-to-secondary split. Structured depth interviews were conducted across the cyclotron value chain, spanning magnet and RF component suppliers, accelerator OEMs, targetry and radiochemistry module providers, hospital-based radiopharmacies and pharmaceutical CDMOs. Respondent designations included VP-level sourcing leads, heads of nuclear medicine physics, technical directors of radiopharmacy operations and commercial operations leads responsible for tender strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Technical & Nuclear Medicine Directors | 38% |
| Procurement & Sourcing Leads | 32% |
| Regulatory & Radiation Safety Managers | 30% |
| Company Type | Representation (%) |
|---|---|
| Accelerator OEMs & System Integrators | 40% |
| Component & Magnet Suppliers | 25% |
| Hospital Radiopharmacies & End Users | 22% |
| Pharma CDMOs & Distributors | 13% |
Secondary validation draws on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations, patent family analysis, and technical standards and guidance from the IAEA, the Society of Nuclear Medicine and Molecular Imaging, and the American Association for Cancer Research. Regulatory approval records from the FDA and EMA inform our view of tracer-pipeline-driven cyclotron demand.
We run simultaneous top-down and bottom-up models. The top-down approach allocates nuclear-medicine capital spend by region and end-user class; the bottom-up approach models manufacturer unit capacity, average system price including shielding and hot cells, and end-use consumption. Divergence beyond a defined tolerance triggers re-interrogation of both models.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |