 South East Asia Telehealth Market
 Size & Forecast 2025–2030
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 226

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 South East Asia Telehealth Market
Amit Mardhekar
Research Analyst

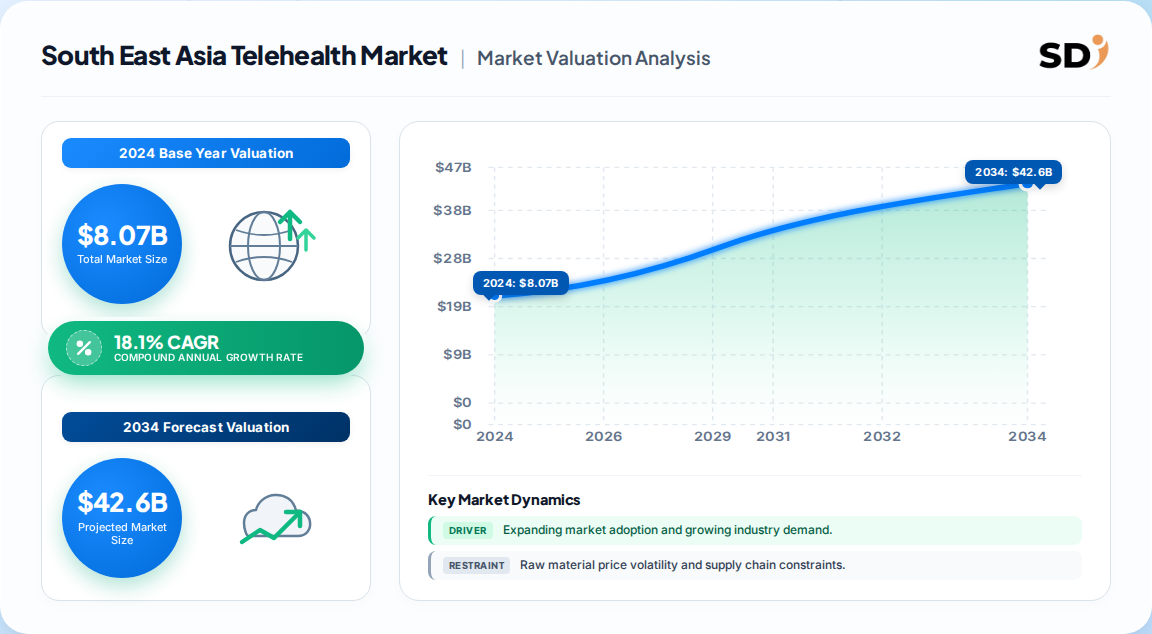
| Year | Market Size |
|---|---|
| 2024 | 8.070 B |
| 2025 | 9.530 B |
| 2026 | 11.26 B |
| 2027 | 13.30 B |
| 2028 | 15.71 B |
| 2029 | 18.55 B |
| 2030 | 21.87 B |

The South East Asia telehealth market comprises technology-enabled remote healthcare delivery—including video consultations, remote patient monitoring, mHealth applications, and store-and-forward services—across Indonesia, Singapore, Philippines, Vietnam, Thailand, Malaysia, and adjacent markets. It serves providers, patients, and payers seeking accessible, cost-effective care beyond traditional clinical settings.
This report covers telehealth services, software, and hardware across six major Southeast Asian countries, segmented by service type, delivery mode, application, end-use, and deployment. It includes market sizing, forecasts to 2030, competitive analysis, and country-level trends. This analysis does not cover traditional in-person healthcare services, pharmaceutical e-commerce, or general wellness applications outside clinical telehealth delivery.
Published estimates diverge materially due to differences in scope, base year, and whether hardware and mHealth are included. The table below compares the most credible benchmarks.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 8.07 Billion | 2024 | 2025–2030 | 18.1% | Services, software, hardware; six countries | One published estimate |
| USD 7.20 Billion | 2024 | 2025–2033 | 18.55% | Component, delivery, application, end-user | A competing analysis |
| USD 1.00 Billion | 2025 | 2026–2034 | 27.26% | Narrower scope, likely services-only | Another published estimate |
The USD 8.07 billion figure is the most defensible for total market sizing because it explicitly includes services, software, and hardware across all major Southeast Asian countries. The lower USD 1.00 billion estimate likely reflects a services-only or narrower geographic scope. Our analysis suggests the true market is between USD 7–8 billion in 2024, with the higher figure more representative of total addressable spend.
The market segments by service type, delivery mode, application, end-use, and deployment model. Real-time interactions lead revenue, while remote patient monitoring is the fastest-growing service type.
| Parent Segment | Children |
|---|---|
| Service Type | Remote Patient Monitoring, Real-time Interactions, Store-and-Forward, mHealth |
| Delivery Mode | Web-based, Cloud-based, On-premises |
| Application | Teleconsultation, Telestroke, Teleradiology, Telepsychiatry, Teledermatology, Tele-ICU, Telecardiology |
| End-use | Providers, Patients, Payers, Others |
| Component | Services, Software, Hardware |
Indonesia leads the South East Asia telehealth market, driven by its large population, uneven healthcare infrastructure, and widespread smartphone adoption. Singapore follows with higher per-capita digital health spending, while the Philippines and Vietnam show rapid adoption growth from a lower base.
Our analysis suggests Indonesia will account for approximately 29% of regional telehealth spend by 2025, with Singapore at 19% and the Philippines at 15%. Precise country-level share data varies by source and definition, and the full report provides granular country forecasts.
Growth is driven by smartphone penetration, chronic disease burden, healthcare worker shortages, and government digital health initiatives. Restraints include rural connectivity gaps, fragmented reimbursement policies, and data privacy concerns.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Smartphone & internet penetration | Driver | High | Expands access to mHealth and video consultations |
| Chronic disease prevalence | Driver | High | Increases demand for remote monitoring and management |
| Healthcare worker shortage | Driver | High | Telehealth bridges gaps in underserved regions |
| Government digital health initiatives | Driver | Medium | Funding and policy support accelerate adoption |
| Rural connectivity gaps | Restraint | High | Limits real-time consultations in remote areas |
| Fragmented reimbursement | Restraint | Medium | Slows provider investment in telehealth infrastructure |
| Data privacy concerns | Restraint | Medium | Increases compliance costs and patient hesitancy |
The balance of evidence favors strong secular growth, with drivers outweighing restraints over the forecast period. However, the digital divide across ASEAN—persistent disparities in broadband infrastructure and adoption—remains a structural constraint that will shape competitive dynamics. Vendors that solve last-mile connectivity and reimbursement integration will capture disproportionate share.
The South East Asia telehealth market is competitive, with local champions and regional players differentiated by country footprint, service breadth, and payer partnerships.
| Company | Headquarters | Key Differentiator |
|---|---|---|
| Halodoc | Indonesia | Largest integrated telehealth and pharmacy platform in Indonesia |
| Alodokter | Indonesia | Strong content and consultation ecosystem with insurer partnerships |
| Doctor Anywhere | Singapore | Regional footprint across six countries; corporate and insurer focus |
| WhiteCoat Holdings | Singapore | Acquiring Good Doctor Indonesia to expand regional reach |
| DOC2US | Malaysia | e-Referral and digital outpatient care leadership in Malaysia |
| Naluri | Malaysia | Digital employee healthcare with enterprise clients |
Competitive moats center on local regulatory relationships, insurer and employer contracts, and integrated pharmacy or diagnostics capabilities. Consolidation through M&A—such as WhiteCoat's acquisition of Good Doctor Indonesia—signals a shift toward scale-based competition. Our analysis suggests vendors without localized compliance and payer integration will struggle to defend margin.
Buyers and operators must prioritize regulatory compliance, interoperability, and reimbursement integration when selecting telehealth platforms. Licensing requirements vary by country, and data privacy regulations—such as Indonesia's PDP Law and Singapore's PDPA—impose significant compliance obligations. Procurement risks include vendor lock-in, unclear service-level agreements, and limited integration with existing electronic health records. Switching costs are high once clinical workflows and payer contracts are embedded, so initial vendor selection should weight long-term scalability and local regulatory expertise. The full report provides detailed procurement criteria and compliance checklists.
The balance of evidence favors strong growth in the South East Asia telehealth market, with an 18.1% CAGR through 2030 driven by structural healthcare access gaps and digital adoption. The strongest counter-argument is that infrastructure and reimbursement fragmentation could suppress growth below consensus, particularly in lower-HDI markets like Cambodia and Laos. However, the scale of Indonesia and Vietnam's adoption momentum likely offsets these drags.
Our analysis suggests investors should focus on platforms with demonstrated payer integration and local regulatory depth, rather than pure-play consumer apps. Operators should prioritize interoperable cloud infrastructure to serve multiple countries without duplicating compliance costs. The WhiteCoat–Good Doctor Indonesia acquisition signals that regional consolidation is the path to scale.
Actionable Strategy:
Evidence that would change our conclusion: a sustained decline in smartphone penetration, major reimbursement reversals in Indonesia or Vietnam, or consolidation that locks up payer relationships could shift the outlook. The full report provides scenario forecasts and country-level detail to monitor these risks.
Our research employs a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the telehealth value chain, including telehealth platform operators, hospital and clinic providers, payer organizations, medical device and wearable suppliers, and regulatory consultants. Decision-maker interviews included Chief Medical Information Officers, Heads of Digital Health, Procurement Directors, and Commercial Operations Leads across Southeast Asia. These interviews validated adoption drivers, procurement cycles, and reimbursement dynamics.
We triangulated findings with official multilateral databases including UN Comtrade, WTO trade statistics, WHO health workforce data, and national digital health roadmaps. Corporate annual filings, investor presentations, and patent databases were reviewed. Regulatory frameworks from Indonesia's Ministry of Health, Singapore's MOH, and Malaysia's MoH informed the compliance landscape assessment.
Our simultaneous Top-Down and Bottom-Up triangulation combines macroeconomic healthcare expenditure allocation with bottom-up platform revenue, consultation volumes, and pricing models. This dual approach ensures market sizing reflects both supply-side capacity and demand-side consumption.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up platform revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection to 2030 | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border adoption analysis, consumption modeling | High |
| Competitive Landscape | Leading market players | Annual reports, funding filings, capacity mapping | High |
| Region | Market Share (%) |
|---|---|
| Indonesia | 0.29% |
| Singapore | 0.19% |
| Philippines | 0.15% |
| Vietnam | 0.14% |
| Thailand | 0.12% |
| Malaysia | 0.09% |
| Rest of Southeast Asia | 0.02% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 18.1% from 2020-2034 |
| Segmentation |
|
The market was estimated at USD 8.07 billion in 2024, with projections reaching approximately USD 21.87 billion by 2030 at an 18.1% CAGR, according to one published estimate.
Indonesia leads in adoption and patient volume, driven by its large population, smartphone penetration, and government eHealth initiatives. Singapore follows with higher per-capita spending.
Remote patient monitoring is the fastest-growing service type, driven by chronic disease management needs and wearable device adoption across the region.
Key players include Halodoc, Alodokter, Doctor Anywhere, WhiteCoat Holdings, DOC2US, and Naluri, with active M&A and funding activity shaping competition.
Rural connectivity gaps, fragmented reimbursement policies, data privacy concerns, and resistance to digital transformation among older populations are the primary challenges.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research employs a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the telehealth value chain, including telehealth platform operators, hospital and clinic providers, payer organizations, medical device and wearable suppliers, and regulatory consultants. Decision-maker interviews included Chief Medical Information Officers, Heads of Digital Health, Procurement Directors, and Commercial Operations Leads across Southeast Asia.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Chief Medical Information Officers | 30% |
| Heads of Digital Health | 30% |
| Procurement Directors | 25% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Telehealth Platform Operators | 40% |
| Hospital & Clinic Providers | 25% |
| Payer Organizations | 20% |
| Device & Wearable Suppliers | 15% |
We triangulated findings with official multilateral databases including UN Comtrade, WTO trade statistics, WHO health workforce data, and national digital health roadmaps. Corporate annual filings, investor presentations, and patent databases were reviewed. Regulatory frameworks from Indonesia's Ministry of Health, Singapore's MOH, and Malaysia's MoH informed the compliance landscape assessment.
Our simultaneous Top-Down and Bottom-Up triangulation combines macroeconomic healthcare expenditure allocation with bottom-up platform revenue, consultation volumes, and pricing models. This dual approach ensures market sizing reflects both supply-side capacity and demand-side consumption.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up platform revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection to 2030 | Historical CAGR, regression analysis, demand elasticity | High |
| Regional Distribution | Country share breakdown | Cross-border adoption analysis, consumption modeling | High |
| Competitive Landscape | Leading market players | Annual reports, funding filings, capacity mapping | High |