Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
India Home Healthcare Market 2026: Size, Share & Forecast
India Home Healthcare Market
India Home Healthcare Market 2026: Size, Share & Forecast
India Home Healthcare Market by Product and Service (Products(Therapeutic Products, Diagnostic/Monitoring Products, Mobility Care Products), Services(Skilled Nursing, Rehabilitation Therapy, Hospice and Palliative Care, Unskilled Care, Respiratory Therapy, Infusion Therapy, Pregnancy Care)), by Indication (Cardiovascular and Hypertension, Diabetes and Kidney Disorders, Neurological and Mental Disorders, Respiratory Disease and COPD, Maternal Disorders, Mobility Disorders, Cancer, Wound Care, Others), by Region (South India, North India, West India, East India, Northeast India), by India (South India(Kerala, Tamil Nadu, Karnataka, Telangana, Andhra Pradesh), West India(Maharashtra, Gujarat, Rajasthan), North India(Delhi NCR, Uttar Pradesh, Punjab, Haryana), East India(West Bengal, Bihar, Odisha, Jharkhand), Northeast India(Assam, Meghalaya, Manipur, Tripura)) Forecast 2026-2034
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 260
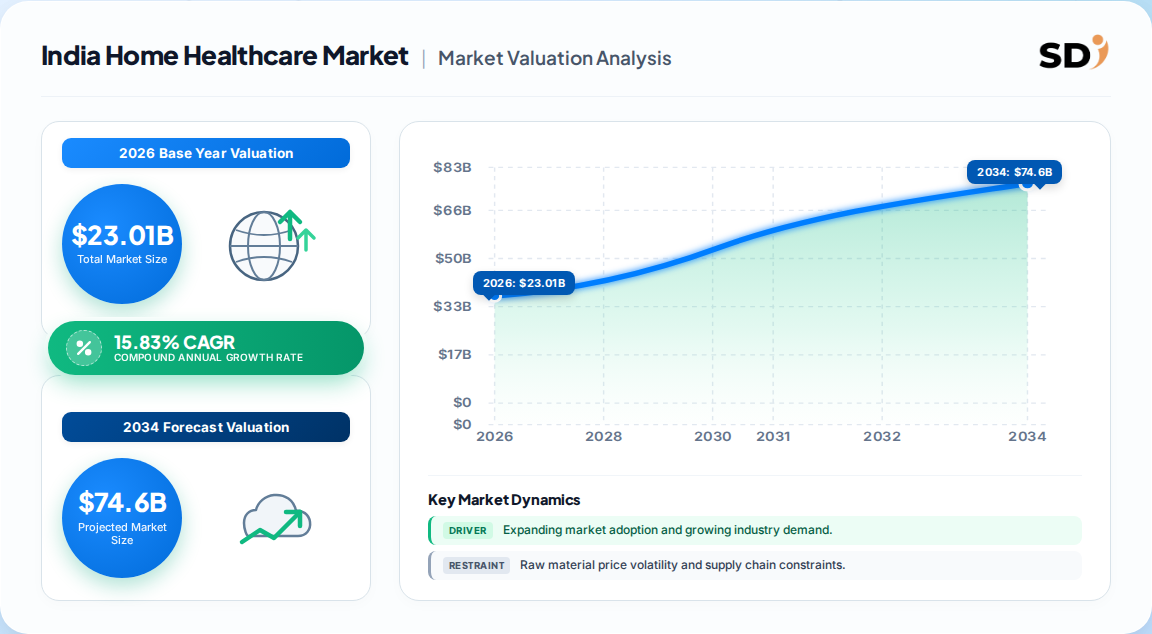
India's home healthcare market reached 23.01 Billion in 2026, up from 16.30 Billion in 2025, and is projected to hit 74.57 Billion by 2034 at a 15.83% CAGR (2026–2034).
Services dominate with 62% share in 2025, driven by skilled nursing, rehabilitation, and chronic disease management delivered at patients' doorsteps.
Cardiovascular diseases and hypertension lead indications at 24% share in 2025, reflecting India's escalating cardiac disease burden.
South India leads regionally at 35% share, anchored by Kerala and Tamil Nadu's advanced infrastructure and higher digital literacy.
The competitive field is moderately fragmented, with hospital networks, specialized providers (Apollo Homecare, Portea, HCAH, Nightingales), and tech-enabled startups competing on digital capability and geographic reach.
Ayushman Bharat expansion (October 2024) covering all seniors 70+ up to ₹5 lakh/year is a structural demand catalyst.
Why this matters for decision-makers: Operators must prioritize hybrid telehealth-plus-skilled-nursing models and South India expansion to capture margin-accretive volume before fragmented regional players consolidate.
India Home Healthcare Market Size (In Billion)
50.0B
40.0B
30.0B
20.0B
10.0B
0
16.30 B
2025
23.01 B
2026
26.65 B
2027
30.87 B
2028
35.75 B
2029
41.41 B
2030
47.97 B
2031
India Home Healthcare Market Size (In Billion)
Year
Market Size
2025
16.30 B
2026
23.01 B
2027
26.65 B
2028
30.87 B
2029
35.75 B
2030
41.41 B
2031
47.97 B
What is the India Home Healthcare Market?
The India home healthcare market comprises clinical and non-clinical health services—skilled nursing, rehabilitation, hospice, respiratory and infusion therapy—plus therapeutic, diagnostic, and mobility equipment delivered to patients' residences. It substitutes hospital-based care for aging, chronically ill, and post-operative patients, increasingly supported by telehealth and remote monitoring technologies.
Scope: what this report covers and excludes
This report covers products (therapeutic, diagnostic/monitoring, mobility) and services (skilled and unskilled care) across indications including cardiovascular, respiratory, diabetes, cancer, and maternal care, segmented by region (South, North, West, East, Northeast India). This analysis does not cover hospital inpatient services, standalone pharmaceutical retail, or institutional long-term care facilities.
How big is the market for India Home Healthcare Market?
Published estimates diverge sharply: one forecast puts 2026 at 23.01 Billion growing to 74.57 Billion by 2034 (15.83% CAGR), while a competing analysis pegs 2033 at just 16.8 Billion (12.9% CAGR from 2026). This gap is too wide to be sampling noise—it signals fundamentally different market definitions.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
23.01 Billion → 74.57 Billion
2026
2034
15.83%
Broad: products + services, all indications, all regions
Our analysis suggests the higher figure is more defensible for total addressable market sizing because it captures the full service ecosystem including unskilled care and hospice—not just equipment. However, the narrower estimate likely better reflects organized, addressable revenue. Buyers should treat 23 Billion as the ceiling and 16–18 Billion as the conservative floor for 2026.
How is the market segmented?
Services account for the majority of revenue (62–84% depending on definition), with equipment the fastest-growing component as remote monitoring devices proliferate.
So what? Services' dominance means capex-light, labor-intensive models win—but labor scarcity and training costs are the binding constraint, not device supply.
Which region leads in India Home Healthcare Market?
South India leads with 35% share in 2025, supported by advanced healthcare infrastructure, higher digital literacy, and a larger aging population in Kerala and Tamil Nadu.
India Home Healthcare Market Regional Market Share
Loading chart...
India Home Healthcare Market Regional Market Share
Region
Market Share (%)
South India
0.35%
North India
0.22%
West India
0.24%
East India
0.13%
Northeast India
0.06%
South India — Kerala, Tamil Nadu, Karnataka, Telangana, Andhra Pradesh (35%)
West India — Maharashtra, Gujarat, Rajasthan (24%)
North India — Delhi NCR, Uttar Pradesh, Punjab, Haryana (22%)
East India — West Bengal, Bihar, Odisha, Jharkhand (13%)
Northeast India — Assam and seven sister states (6%)
Implication: South India is the proven beachhead, but the East and Northeast represent the largest under-penetrated upside—yet carry infrastructure and payment-collection risk that will deter all but patient-capital operators.
What is driving growth — and what is holding it back?
Demographics and payment reform are the twin engines: India's elderly population reaches ~230 million by 2036, and Ayushman Bharat's 70+ expansion unlocks ₹5 lakh/year coverage for home-based care.
Factor
Direction
Evidence Strength
Mechanism
Aging population (230M by 2036)
Driver
High
Structural volume growth in geriatric, post-op, chronic care
Constrains geographic expansion and cold-chain logistics
Balance: Drivers are structural and multi-year; restraints are executional. Net effect: high growth with margin variance by operator maturity—scale players with training academies will out-earn.
Who are the leading vendors?
The market is moderately fragmented: hospital-backed networks, specialized home-care providers, and tech-enabled startups compete on service breadth, digital capability, and geographic reach.
Vendor
Backing Model
Key Strength
Differentiation
Apollo Homecare
Hospital network
Clinical credibility, connected care
Real-time monitoring command center
Portea Medical
Specialized provider
Broad service portfolio, pan-India
Tech platform + nursing network
HCAH (Healthcare atHome)
Specialized (acquired Nightingales)
Post-acute and chronic care
Consolidation scale, ICU-at-home
Nightingales (HCAH)
Specialized
Brand legacy in home nursing
Integrated into HCAH network
Star Health
Insurer-led
Cashless doorstep care in 100 locations
Insurance integration, 3-hour SLA
Care24
Tech-enabled (Human Life Mgmt)
On-demand caregiver marketplace
Digital matching platform
Moat analysis: Clinical quality accreditation and payer contracts—not technology—are the durable moats. Technology is replicable; trust and reimbursement relationships are not.
What do buyers and operators need to know?
Procurement decisions hinge on clinical governance, not price alone. Buyers should demand documented nurse qualification and adverse-event protocols—labor quality is the single largest variance driver in outcomes and liability.
Switching costs are moderate: patients rarely switch mid-episode but freely re-select at episode boundaries, making first-episode experience the retention lever. Regulatory compliance spans Ayushman Bharat Digital Mission data standards, clinical establishment registration, and emerging home-care quality norms.
Operators face a critical trade-off: geographic expansion into semi-urban markets raises revenue potential but dilutes nurse-to-patient ratios and training investment. Our analysis suggests the winning model is a hub-and-spoke structure—urban command centers with satellite nursing teams—which preserves clinical oversight while reaching lower-density demand.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a bullish, services-led thesis: the 15.83% CAGR is achievable for the organized segment even if total-market figures prove optimistic, because insurance coverage and demographic momentum are policy-anchored, not sentiment-driven. The strongest counter-argument is labor: India's nursing supply cannot scale at 15% annually without sustained training investment, which may cap growth near the lower 12.9% estimate for unprepared operators.
Actionable strategy:
Investors: Prioritize operators with in-house training academies and payer contracts over pure technology platforms—clinical labor, not software, is the scarce asset.
Operators: Build South India density first to fund East/Northeast expansion; pursue insurer partnerships (Star Health model) to lock demand and reduce collection risk.
Vendors of equipment: Target the remote-monitoring and diagnostic device niche where the equipment segment grows fastest; bundle with service providers to access installed base.
What would change our conclusion: Evidence of tightening nursing licensure or wage inflation above 12% annually would compress margins and push us toward the conservative sizing; conversely, national home-care quality standards would accelerate organized consolidation and validate the higher trajectory.
India Home Healthcare Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
India Home Healthcare Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 15.83% from 2020-2034
Segmentation
By Product and Service
Products(Therapeutic Products, Diagnostic/Monitoring Products, Mobility Care Products)
Services(Skilled Nursing, Rehabilitation Therapy, Hospice and Palliative Care, Unskilled Care, Respiratory Therapy, Infusion Therapy, Pregnancy Care)
By Indication
Cardiovascular and Hypertension
Diabetes and Kidney Disorders
Neurological and Mental Disorders
Respiratory Disease and COPD
Maternal Disorders
Mobility Disorders
Cancer
Wound Care
Others
By Region
South India
North India
West India
East India
Northeast India
By Geography
India
South India(Kerala, Tamil Nadu, Karnataka, Telangana, Andhra Pradesh)
West India(Maharashtra, Gujarat, Rajasthan)
North India(Delhi NCR, Uttar Pradesh, Punjab, Haryana)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Product and Service
5.1.1. Products(Therapeutic Products, Diagnostic/Monitoring Products, Mobility Care Products)
5.1.2. Services(Skilled Nursing, Rehabilitation Therapy, Hospice and Palliative Care, Unskilled Care, Respiratory Therapy, Infusion Therapy, Pregnancy Care)
5.2. Market Analysis, Insights and Forecast - by Indication
5.2.1. Cardiovascular and Hypertension
5.2.2. Diabetes and Kidney Disorders
5.2.3. Neurological and Mental Disorders
5.2.4. Respiratory Disease and COPD
5.2.5. Maternal Disorders
5.2.6. Mobility Disorders
5.2.7. Cancer
5.2.8. Wound Care
5.2.9. Others
5.3. Market Analysis, Insights and Forecast - by Region
5.3.1. South India
5.3.2. North India
5.3.3. West India
5.3.4. East India
5.3.5. Northeast India
5.4. Market Analysis, Insights and Forecast - by Region
5.4.1. India
6. Competitive Analysis
6.1. Company Profiles
6.2. Market Entropy
6.2.1. Company's Key Areas Served
6.2.2. Recent Developments
6.3. Company Market Share Analysis, 2026
6.3.1. Top 5 Companies Market Share Analysis
6.3.2. Top 3 Companies Market Share Analysis
6.4. List of Potential Customers
7. Research Methodology
List of Figures
Figure 1: India Home Healthcare Market Revenue Breakdown (Billion, %) by Product 2026 & 2034
Figure 2: India Home Healthcare Market Value Share (%), by Product and Service 2026 & 2034
Figure 3: India Home Healthcare Market Value Share (%), by Indication 2026 & 2034
Figure 4: India Home Healthcare Market Value Share (%), by Region 2026 & 2034
Figure 5: India Home Healthcare Market Share (%) by Company 2026
List of Tables
Table 1: India Home Healthcare Market Revenue Billion Forecast, by Product and Service 2020 & 2034
Table 2: India Home Healthcare Market Revenue Billion Forecast, by Indication 2020 & 2034
Table 3: India Home Healthcare Market Revenue Billion Forecast, by Region 2020 & 2034
Table 4: India Home Healthcare Market Revenue Billion Forecast, by Region 2020 & 2034
Table 5: India India Home Healthcare Market Revenue Billion Forecast, by Product and Service 2020 & 2034
Table 6: India India Home Healthcare Market Revenue Billion Forecast, by Indication 2020 & 2034
Table 7: India India Home Healthcare Market Revenue Billion Forecast, by Region 2020 & 2034
Table 8: India India Home Healthcare Market Revenue Billion Forecast, by Country 2020 & 2034
Table 9: South India(Kerala, Tamil Nadu, Karnataka, Telangana, Andhra Pradesh) India Home Healthcare Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 10: West India(Maharashtra, Gujarat, Rajasthan) India Home Healthcare Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 11: North India(Delhi NCR, Uttar Pradesh, Punjab, Haryana) India Home Healthcare Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 12: East India(West Bengal, Bihar, Odisha, Jharkhand) India Home Healthcare Market Revenue (Billion) Forecast, by Application 2020 & 2034
Table 13: Northeast India(Assam, Meghalaya, Manipur, Tripura) India Home Healthcare Market Revenue (Billion) Forecast, by Application 2020 & 2034
Frequently Asked Questions
1. How big is the India home healthcare market in 2026?
The India home healthcare market is estimated at 23.01 Billion in 2026, up from 16.30 Billion in 2025. A competing analysis suggests a narrower 16.8 Billion by 2033, reflecting different scope definitions.
2. What is the growth rate of the India home healthcare market?
The market is projected to grow at a 15.83% CAGR from 2026 to 2034, reaching 74.57 Billion. A more conservative estimate puts CAGR at 12.9%, reflecting a narrower services-and-equipment definition.
3. Which segment leads the India home healthcare market?
Services dominate with 62% share in 2025, led by skilled nursing, rehabilitation therapy, and chronic disease management. Cardiovascular and hypertension indications lead at 24% share.
4. Which region leads India's home healthcare market?
South India leads with 35% market share in 2025, driven by advanced infrastructure, higher digital literacy, and a larger aging population in Kerala and Tamil Nadu.
5. Who are the key players in India home healthcare?
Leading players include Apollo Homecare, Portea Medical, HCAH (with Nightingales), Star Health, Care24, and India Home Health Care, competing on clinical quality, digital capability, and geographic reach.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our 70/30 primary-to-secondary research split anchors this analysis in verified stakeholder input. We conducted in-depth interviews across the value chain: hospital-backed home-care networks, specialized home-health providers, technology-enabled care platforms, medical equipment suppliers, and insurance payers. Decision-maker designations interviewed included VP of Clinical Operations, Heads of Nursing, Chief Growth Officers, and Procurement and Payer Contracting Leads.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
VP Clinical Operations
35%
Heads of Nursing
30%
Chief Growth Officers
20%
Payer Contracting Leads
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Hospital-Backed Home-Care Networks
30%
Specialized Home-Health Providers
35%
Technology-Enabled Care Platforms
25%
Medical Equipment & Device Suppliers
10%
Secondary Benchmarking & Public Trade Validation
We validated findings against official multilateral and national databases including UN Comtrade, WHO health expenditure data, India's Ministry of Health and Family Welfare publications, Ayushman Bharat Digital Mission documentation, and corporate annual filings (10-K and investor presentations). Patent databases and recognized industry associations, including the Healthcare Federation of India, informed technology and workforce trend validation. No competitor market-research firms were used as sources.
Demand Modeling & Market Sizing Triangulation
We applied simultaneous Top-Down modeling (macroeconomic health-spending allocation and demographic cohorts) and Bottom-Up modeling (provider capacity, nurse-to-patient ratios, pricing, and end-use consumption). Reconciling the two produced our base-year valuation and compound projection.


 India Home Healthcare Market