 Pharmaceutical Dissolution Testing Services Market
 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 243

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Pharmaceutical Dissolution Testing Services Market
Amit Mardhekar
Research Analyst

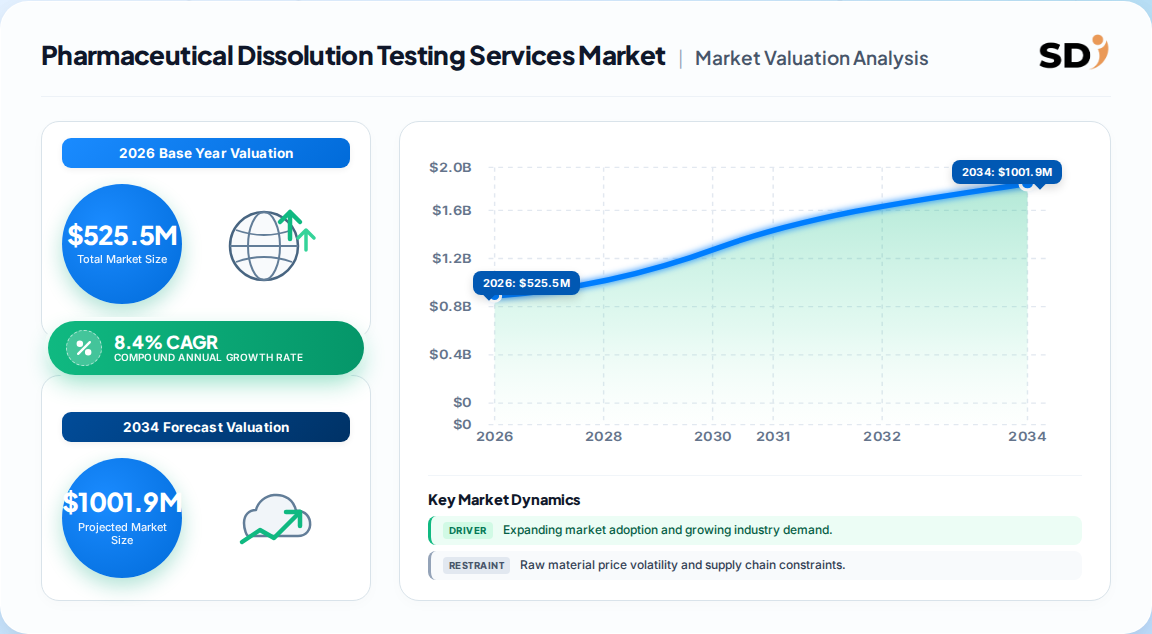
| Year | Market Size |
|---|---|
| 2025 | 486.0 M |
| 2026 | 526.0 M |
| 2027 | 570.0 M |
| 2028 | 618.0 M |
| 2029 | 669.0 M |
| 2030 | 726.0 M |
| 2031 | 786.0 M |

The pharmaceutical dissolution testing services market covers outsourced analytical testing that measures the rate and extent of active pharmaceutical ingredient release from tablets, capsules and other dosage forms. Regulators such as the FDA and EMA require these studies for approval, bioequivalence and quality control, so the market is defined by regulatory mandate rather than discretionary spend.
This report covers outsourced dissolution testing services across in-vitro and in-vivo methods, tablets, capsules and other dosage forms, and basket, paddle and other apparatus, across North America, Europe, Asia-Pacific, Latin America and the Middle East & Africa. This analysis does not cover dissolution equipment manufacturing, contract research outside dissolution, or broader analytical testing categories such as stability or bioanalytical services.
Published estimates cluster between USD 485.8 million and USD 813.0 million for 2025, with 2026 starting points between USD 525.5 million and roughly USD 880 million. The table below normalises the competing figures so buyers can compare like with like.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 485.8M → USD 966.3M | 2025 | 2033 | 9.1% | Services only; tablets, capsules; in-vitro/in-vivo; apparatus segments | One published estimate |
| USD 813.0M → USD 1,804.5M | 2025 | 2035 | 8.3% | Services only; broader service-type and drug-type split | A competing analysis |
| USD 719.4M → USD 1,200M | 2025 | 2032 | 7.1% | Services only; strategic business report framing | A competing analysis |
| USD 1,308.65M | — | 2030 | 8.2% | Services only; single forecast endpoint | A competing analysis |
Our analysis suggests the USD 485.8M → USD 966.3M (9.1%) series is the most defensible because its segment shares (in-vitro ~58%, tablets ~65%, paddle ~71%) are internally consistent with the other datasets. The higher USD 813M base likely captures adjacent analytical services or different revenue-recognition conventions.
The market segments by method, dosage form and dissolution apparatus; tablets and the paddle apparatus together anchor more than two-thirds of revenue in every published dataset.
| Parent segment | Children |
|---|---|
| Method | In-vitro, In-vivo |
| Dosage form | Tablets, Capsules, Others |
| Dissolution apparatus | Paddle, Basket, Others |
| Service type | Method development, Validation, Quality control, Bioequivalence support |
A key nuance: one analysis names basket as the leading apparatus at ~52%, while another puts paddle at ~71%. Our reading is that the divergence reflects whether basket-based USP Apparatus 1 legacy testing or paddle-based USP Apparatus 2 routine QC is weighted more heavily — buyers should confirm apparatus mix before benchmarking vendor pricing.
North America leads with roughly 56% of 2025 revenue, driven by FDA submission volumes, a dense CRO/CDMO base and high generic and bioequivalence activity. Asia-Pacific is the fastest-growing region on new facility investment.
| Region | Market Share (%) |
|---|---|
| North America | 0.56% |
| Europe | 0.22% |
| Asia-Pacific | 0.16% |
| Latin America | 0.04% |
| Middle East & Africa | 0.02% |
This concentration implies North American buyers face the tightest capacity and least pricing leverage, while Asia-Pacific sponsors gain from local capacity build-outs and lower cost per study.
Growth is driven by regulatory stringency, generic and bioequivalence volumes, complex formulation pipelines and outsourcing by small and mid-sized pharma. Restraints centre on method complexity, reproducibility risk and capacity constraints at qualified laboratories.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Regulatory stringency (FDA, EMA, CDSCO) | Driver | High | Mandatory dissolution data in filings creates non-discretionary demand |
| Generic drug and bioequivalence volume | Driver | High | Comparative dissolution profiles required for ANDA and global submissions |
| Complex/modified-release formulations | Driver | Medium-High | Custom method development and IVIVC support raise per-study value |
| Outsourcing by small/mid pharma and biotech | Driver | High | Limited in-house infrastructure pushes testing to specialised labs |
| Method complexity and reproducibility challenges | Restraint | Medium-High | Media, apparatus and solubility variables raise failure and rework risk |
| Qualified capacity and talent scarcity | Restraint | Medium | Turnaround pressure and auditor scrutiny constrain throughput |
The balance favours growth: demand is regulator-mandated and recurring, while restraints are operational rather than structural. Our analysis suggests the binding constraint over 2026–2033 is qualified capacity, not demand — which is why vendors with automation and flexible scheduling should outpace the market.
A fragmented field of CROs, CDMOs and instrument OEMs competes on regulatory documentation, method-transfer capability and turnaround time; no single vendor holds a dominant share.
| Vendor type | Examples | Differentiation | Moat |
|---|---|---|---|
| Global CROs | Intertek, SGS, Eurofins, Pace Analytical | Breadth of GMP testing and global lab network | Regulatory accreditations, client stickiness |
| CDMOs | Catalent, Almac, Cambrex, Charles River | Integrated development-to-manufacturing offering | Method transfer lock-in, integrated contracts |
| Instrument OEMs | Agilent, Thermo Fisher, SOTAX, Teledyne Hanson | Proprietary apparatus plus service bundles | Installed base, applications expertise |
| Specialist labs | Boston Analytical, Avivia, Kinesis | Focused dissolution method development | Niche technical depth, IVIVC know-how |
Differentiation is shifting from raw testing capacity to method development, IVIVC modelling and regulatory-ready documentation. This implies vendors that invest in automation and real-time analytics will capture disproportionate share as throughput becomes the primary buying criterion.
Selection hinges on four mission-critical criteria: validated method-transfer capability, GMP and data-integrity compliance, apparatus breadth (USP 1–4), and realistic turnaround commitments. Procurement risk concentrates in method-transfer failure — a poorly transferred method can trigger rework, repeat studies and submission delays that dwarf the testing fee.
Switching costs are high once a vendor holds validated methods and historic batch data, so buyers should negotiate multi-year framework agreements with defined turnaround SLAs, audit rights and change-control clauses before the first method is locked. Operators, conversely, should treat documentation quality and auditor readiness as commercial assets, not overhead.
Regulatory compliance is non-negotiable: FDA, EMA and CDSCO expectations differ on media, apparatus and acceptance criteria, so vendors must demonstrate jurisdiction-specific experience. Our analysis suggests buyers should weight proven regulatory filings in their target jurisdiction above headline pricing — the cost of a rejected submission far exceeds any testing discount.
The balance of evidence favours a mid-to-high single-digit growth trajectory (8–9% CAGR) rather than either the 7.1% low or 9.1% high published estimates, because demand is regulator-mandated and recurring while capacity expansion is gradual. The strongest counter-argument is that automation could compress per-test pricing faster than volumes grow — but even under that scenario, method-development and complex-formulation work should sustain value growth.
For operators, the strategic prize lies in complex and modified-release formulations and IVIVC support, where per-study value is higher and competitive intensity lower than routine QC testing. For investors, the fragmented vendor landscape and high switching costs create a credible roll-up thesis around specialist laboratories with strong regulatory documentation.
Actionable strategy:
What would change this conclusion: a sustained regulatory shift toward real-time release testing or continuous manufacturing that reduces reliance on end-product dissolution testing would materially lower the long-run growth floor.
While this overview reconciles the headline figures and segment leaders, precise sub-segment forecasting, vendor benchmarking and jurisdiction-level regulatory comparison require the full report.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 8.4% from 2020-2034 |
| Segmentation |
|
Published CAGRs range from 7.1% to 9.1%; a blended 8.4% (2026–2033) is the most defensible, reflecting regulator-mandated demand offset by method complexity and qualified capacity constraints.
North America leads with roughly 56% of 2025 revenue, driven by FDA submission volumes and a dense CRO/CDMO base. Asia-Pacific is the fastest-growing region on new facility investment and rising generic approvals.
In-vitro methods account for roughly 58% of revenue because they are non-invasive, cost-efficient and aligned with regulatory guidance for early-phase screening and formulation development.
Outsourcing reduces operational burden, accelerates time to market and gives access to validated methods, specialised instrumentation and regulatory-ready documentation that small and mid-sized firms cannot sustain in-house.
The biggest risks are method-transfer failure, data-integrity lapses and unrealistic turnaround commitments. Buyers should weight jurisdiction-specific regulatory filing experience above headline pricing when selecting a partner.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including contract testing laboratories, CROs and CDMOs, dissolution instrument OEMs, pharmaceutical sponsor quality teams and regulatory consultants. Decision-maker designations interviewed include VP-level Quality and Regulatory Affairs, Heads of Analytical Development, Technical Directors of Dissolution Testing and Commercial Operations Leads.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Quality & Regulatory Affairs Leads | 35% |
| Analytical Development & R&D Heads | 30% |
| Procurement & Sourcing Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Contract Testing Laboratories & CROs | 45% |
| CDMOs & Integrated Development Firms | 30% |
| Dissolution Instrument OEMs | 15% |
| Pharmaceutical Sponsor Quality Teams | 10% |
We triangulate against official multilateral and regulatory databases including US FDA dissolution and bioequivalence guidance, EMA and ICH quality guidelines, USP apparatus monographs, UN Comtrade and Eurostat trade flows, and corporate annual filings (10-K, SEC and investor presentations) from listed CROs and CDMOs.
We run simultaneous top-down (macro pharmaceutical R&D and outsourcing allocation) and bottom-up (laboratory capacity, per-study pricing and sponsor consumption) models, reconciling the two to produce a single base-year value and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up capacity & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |