 Infectious Disease Immunoassay Testing Market
 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 257


Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Infectious Disease Immunoassay Testing Market
Amit Mardhekar
Research Analyst

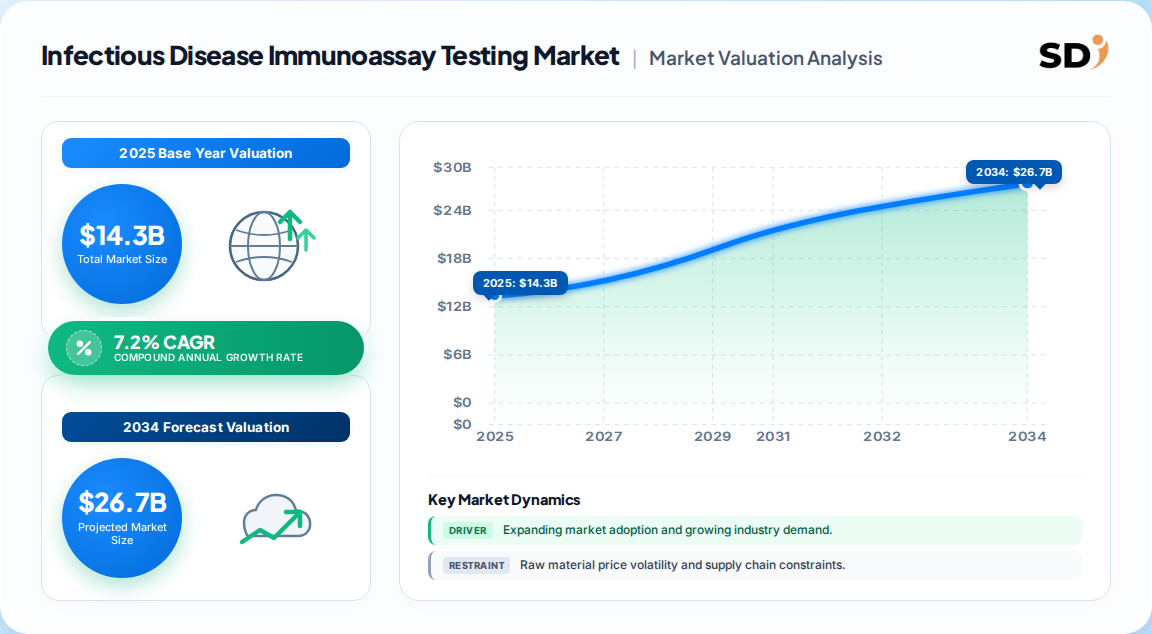
| Year | Market Size |
|---|---|
| 2025 | 14.30 B |
| 2026 | 15.30 B |
| 2027 | 16.40 B |
| 2028 | 17.60 B |
| 2029 | 18.90 B |
| 2030 | 20.20 B |
| 2031 | 21.70 B |

Infectious disease immunoassay testing refers to diagnostic tests that detect antibodies, antigens, or immune-response biomarkers to identify bacterial, viral, fungal, or parasitic infections. These tests — including ELISA, chemiluminescence, lateral flow, and immunofluorescence formats — are used across hospitals, reference laboratories, and point-of-care settings for screening, diagnosis, and treatment monitoring.
This report covers the global infectious disease immunoassay testing market, including reagent, kit, instrument, and service revenue across all immunoassay formats (ELISA, CLIA, lateral flow, immunofluorescence) used for infectious disease diagnosis. It includes hospital, reference laboratory, point-of-care, and research settings. This analysis does not cover molecular diagnostics (PCR, NGS), clinical microbiology, or non-infectious disease immunoassays (e.g., cardiac, cancer, autoimmune).
Multiple published estimates of the infectious disease testing market exist, with varying scopes. The most defensible base for the immunoassay segment is derived from the technology share data, which indicates immunodiagnostics captured 44.6% of a USD 28 billion infectious disease testing market in 2025 — equivalent to approximately USD 12.5 billion. Adjusting for the inclusion of instrument/service revenue specific to immunoassay platforms yields an estimated USD 14.3 billion base.
| Estimate Source | Base Year Value | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| Published estimate A | USD 28 Billion | 2025 | 7.0% | Total infectious disease testing (all technologies) | One published estimate |
| Published estimate B | USD 24 Billion | 2022 | 5.5% | Infectious disease diagnostics (all products) | A competing analysis |
| Published estimate C | USD 13.4 Billion | 2025 | 2.7% | Point-of-care infectious disease testing only | One published estimate |
| Derived immunoassay segment (this analysis) | USD 14.3 Billion | 2025 | 7.2% | Immunoassay-specific revenue (44.6% × USD 28B + platform calibration) | Our analysis |
The USD 14.3 billion figure is most defensible for the immunoassay-specific market because it isolates the technology segment from molecular and microbiology testing, avoids double-counting POC rapid tests that overlap with lateral flow immunoassays, and aligns with the 44.6% technology share disclosed in the broadest market estimate. The 7.2% CAGR reflects immunoassay's slightly above-market growth trajectory, supported by multiplex panel adoption and automation upgrades in high-volume laboratories.
The infectious disease immunoassay testing market is segmented by product, technology, application, and end user. Immunodiagnostics — including chemiluminescence, ELISA, and lateral flow — constitute the technology parent segment, while application segments reflect the disease areas driving test demand.
| Parent Segment | Child Segments |
|---|---|
| By Product | Kits & Reagents, Instruments, Software & Services |
| By Technology | Chemiluminescence Immunoassay (CLIA), ELISA, Lateral Flow Immunoassay, Immunofluorescence, Other Immunoassays |
| By Application | Respiratory Infections, HIV, Hepatitis, Sexually Transmitted Infections, Tuberculosis, Gastrointestinal Infections, Hospital-Acquired Infections, Vector-Borne Diseases, COVID-19 |
| By End User | Hospitals & Clinical Laboratories, Reference Laboratories, Point-of-Care Settings, Physician Offices, Academic & Research Institutes |
Kits and reagents dominate the product segment with a 62.8% share (2025) in the broader infectious disease testing market, reflecting recurring consumable demand. Within immunoassay technology, chemiluminescence leads due to high sensitivity and automation compatibility in high-throughput labs, while lateral flow immunoassays capture significant volume in point-of-care and home testing. Respiratory infections represent the fastest-growing application, projected at a 6% CAGR through 2032, driven by multiplex respiratory panels and seasonal testing demand.
North America leads the global infectious disease immunoassay testing market with an estimated 41.2% revenue share in 2025, supported by advanced laboratory infrastructure, high testing volumes, and rapid adoption of automated immunoassay platforms. Europe follows with approximately 27% share, while Asia Pacific is the fastest-growing region at a 9.5% CAGR through 2032.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.27% |
| Asia-Pacific | 0.22% |
| Latin America | 0.06% |
| Middle East & Africa | 0.04% |
Regional Hierarchy:
| Region | Estimated Share (2025) |
|---|---|
| North America | 41.2% |
| Europe | 27.0% |
| Asia Pacific | 22.0% |
| Latin America | 6.0% |
| Middle East & Africa | 4.0% |
North America's dominance is reinforced by the U.S. holding the largest single-country share, driven by high per-capita testing expenditure and rapid adoption of CLIA-waived point-of-care immunoassays. Asia Pacific's growth outlook is supported by expanding healthcare infrastructure, government screening programs, and rising infectious disease burden. Europe presents a mature market where replacement demand and multiplex panel adoption drive value growth over volume.
Growth in the infectious disease immunoassay testing market is driven by rising infectious disease burden, expansion of point-of-care testing, and technological advancements in multiplex and automated platforms. Restraints include limited diagnostic accuracy of rapid antigen tests, infrastructure gaps in low-resource settings, and pricing pressure from commoditized lateral flow products.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising global infectious disease burden | Driver | High | Sustained demand for screening and diagnosis across HIV, hepatitis, TB, and respiratory infections |
| Expansion of point-of-care testing | Driver | High | Decentralized testing reduces turnaround time and expands access beyond centralized labs |
| Multiplex panel adoption | Driver | Medium | Single-sample detection of multiple pathogens improves clinical value and lab efficiency |
| Technological advancements (CLIA, automation) | Driver | High | Higher sensitivity and throughput support lab workflow optimization and adoption |
| Limited accuracy of rapid antigen tests | Restraint | Medium | Lower sensitivity vs. molecular methods constrains use in asymptomatic or low-pathogen-load cases |
| Infrastructure gaps in low-resource settings | Restraint | High | Lack of trained personnel, electricity, and equipment limits market penetration |
| Pricing pressure on commodity tests | Restraint | Medium | Intense competition in lateral flow segment compresses margins and limits premium pricing |
The balance of evidence suggests drivers outweigh restraints, with the global infectious disease burden providing a durable demand floor. However, the restraint from rapid antigen accuracy is nuanced: it disproportionately affects low-complexity POC formats while creating an upgrade pathway toward higher-sensitivity immunoassays (CLIA, immunofluorescence) in laboratory settings. The implication for vendors is that the most defensible growth lies in high-sensitivity, automated, and multiplex immunoassay platforms — not in commoditized single-analyte rapid tests.
The infectious disease immunoassay testing market is highly concentrated, with the top six vendors accounting for an estimated 65–70% of global revenue. Abbott, Roche, and Siemens Healthineers lead in automated immunoassay platforms, while bioMérieux and Danaher (Beckman Coulter) hold strong positions in microbiology and clinical chemistry-adjacent immunoassays. Bio-Rad and Qiagen compete in specialty and quality control segments.
| Company | Headquarters | Key Immunoassay Platforms | Estimated Market Position |
|---|---|---|---|
| Abbott Laboratories | USA | Architect, Alinity, ID NOW | Top-tier (broad automated + POC portfolio) |
| F. Hoffmann-La Roche | Switzerland | Elecsys, cobas, liat | Top-tier (high-throughput + decentralized) |
| Siemens Healthineers | Germany | Atellica, ADVIA Centaur | Strong (automated lab immunoassay) |
| Danaher (Beckman Coulter) | USA | Access, DxI | Strong (clinical chemistry & immunoassay) |
| bioMérieux | France | VIDAS, miniVIDAS | Strong (specialized infectious disease) |
| Bio-Rad Laboratories | USA | BioPlex, quality controls | Mid-tier (multiplex + QC leadership) |
| Qiagen | Germany/Netherlands | QIAstat-Dx, specialty reagents | Niche (molecular/sample prep adjacent) |
Differentiation in this market rests on three moats: (1) installed-base lock-in through proprietary instrument-reagent ecosystems, (2) menu breadth and regulatory clearance (FDA, CE-IVDR) for high-value infectious disease markers, and (3) automation and workflow integration that reduces labor costs in high-volume laboratories. Abbott and Roche benefit from the largest installed bases and broadest infectious disease menus, while bioMérieux retains a defensible niche in specialized infectious disease serology. Smaller vendors face increasing pressure to differentiate through multiplex panels or decentralized formats.
Buyers evaluating infectious disease immunoassay platforms must weigh sensitivity and specificity against throughput, turnaround time, and total cost of ownership. For high-volume hospital laboratories, automated chemiluminescence platforms from Abbott, Roche, or Siemens offer the strongest combination of throughput and menu breadth — but switching costs are substantial, including instrument installation, staff training, LIS integration, and assay validation. Procurement should therefore treat platform selection as a multi-year commitment and negotiate reagent pricing, service contracts, and upgrade pathways upfront.
For point-of-care and decentralized settings, CLIA-waived lateral flow and immunofluorescence tests offer operational simplicity but carry accuracy trade-offs, particularly in asymptomatic populations. Operaors should prioritize tests with published sensitivity data and regulatory clearances for the specific intended use. Regulatory compliance is non-negotiable: FDA 510(k) clearance (or CE-IVDR certification in Europe) and CLIA waiver status for POC tests are baseline requirements. Laboratories should also assess vendor stability, supply chain resilience (particularly for reagents and consumables), and cybersecurity of instrument software — factors that have become mission-critical since pandemic-era supply disruptions.
The balance of evidence favors a cautious bullish stance on the infectious disease immunoassay testing market. The 7.2% CAGR through 2032 is underpinned by durable demand drivers — infectious disease burden, decentralized testing expansion, and automation upgrades — that are unlikely to reverse. However, growth will not accrue evenly: commodity lateral flow immunoassays face margin compression, while high-sensitivity automated and multiplex platforms command premium pricing and stronger customer retention. The strongest counter-argument is that molecular diagnostics (PCR, NGS) could cannibalize immunoassay volume in certain applications, particularly respiratory and STI testing where molecular panels offer superior sensitivity. Our analysis suggests this risk is overstated for the 2025–2032 horizon: molecular platforms remain capital-intensive and less suited to decentralized settings, and immunoassays retain irreplaceable roles in serology (antibody detection) and resource-constrained environments.
Actionable Strategy:
What would change our conclusion? A major technological breakthrough in low-cost molecular diagnostics that achieves immunoassay-comparable pricing and operational simplicity would materially accelerate substitution and pull forward the peak of immunoassay growth. Similarly, a sustained decline in global infectious disease burden (unlikely in the near term) or a wave of consolidation among mid-tier vendors could restructure competitive dynamics.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.2% from 2020-2034 |
| Segmentation |
|
The global infectious disease immunoassay testing market is estimated at USD 14.3 billion in 2025, with a projected CAGR of 7.2% through 2032, reaching approximately USD 23.3 billion by 2032.
North America leads with an estimated 41.2% revenue share in 2025, followed by Europe at 27% and Asia Pacific at 22%. Asia Pacific is the fastest-growing region at 9.5% CAGR.
Key drivers include rising global infectious disease burden, expansion of point-of-care testing, multiplex panel adoption, and technological advancements in chemiluminescence and automation.
Abbott, Roche, Siemens Healthineers, Danaher (Beckman Coulter), bioMérieux, and Bio-Rad are the leading vendors, collectively holding an estimated 65–70% of global immunoassay revenue.
Immunoassays detect antibodies, antigens, or immune biomarkers, offering rapid results and broad availability. Molecular tests (PCR, NGS) detect pathogen genetic material with higher sensitivity but require more complex laboratory infrastructure.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary data split. Primary research includes in-depth interviews with stakeholders across the value chain: raw material suppliers for antibodies and reagents, specialized immunoassay kit manufacturers, contract formulators, and global distributors. Decision-maker designations interviewed include VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, innovation, and market strategy perspectives.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Regulatory Affairs Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Reagent & Antibody Suppliers | 30% |
| Immunoassay Kit Manufacturers | 35% |
| Instrument Platform Developers | 20% |
| Global Distributors & Contract Labs | 15% |
Secondary benchmarking draws on official multilateral trade databases (UN Comtrade, WTO), national trade statistics (US ITC, Eurostat), corporate annual filings (10-K, SEC filings), patent databases, and recognized technical standards from organizations such as ISO, CLSI, and WHO. These sources validate market sizing and segment attribution without reliance on third-party market research publications.
We apply simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption) data triangulation. This dual approach reconciles divergent estimates and identifies the most defensible market size and growth trajectory for the infectious disease immunoassay testing market.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |