 Poultry Diagnostics Market
: 2026 Global Analysis
Updated On : Nov 20, 2026|Base Year : 2025|Pages : 233

Amit Mardhekar

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Poultry Diagnostics Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2025 | 898.0 M |
| 2026 | 986.0 M |
| 2027 | 1.080 B |
| 2028 | 1.190 B |
| 2029 | 1.310 B |
| 2030 | 1.430 B |
| 2031 | 1.570 B |

The poultry diagnostics market covers laboratory tests, kits, reagents, instruments, and services used to detect and monitor diseases in commercial and backyard poultry. Core modalities include ELISA, PCR and other molecular assays, bacteriology, virology, and clinical chemistry, deployed across reference laboratories, on-farm point-of-care units, and veterinary hospitals to protect flock health and food safety.
This report covers the global poultry diagnostics market across test type (ELISA, PCR, molecular, others), disease type (avian influenza, Newcastle disease, infectious bronchitis, bursal disease, salmonellosis, mycoplasmosis, chicken anemia), service type (bacteriology, virology, parasitology), product (consumables, reagents and kits, instruments, services), and end use (veterinary reference laboratories, on-farm point-of-care, veterinary hospitals, research institutes). It spans 2020–2033 with 2025 as base year. This analysis does not cover livestock diagnostics beyond poultry, companion animal diagnostics, human clinical diagnostics, poultry vaccines and therapeutics, or feed additives and nutrition.
Estimates diverge materially because publishers define the market's perimeter differently: some include only consumables and kits, others bundle reference-lab services, instruments, and software. The table below reconciles the competing published benchmarks against a consistent base-year lens.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 898.1 million (2025); USD 986.1 million (2026) | 2025 | 2026–2033 | 9.8% | Full poultry diagnostics incl. consumables, reagents, kits, instruments, services | One published estimate (secondary benchmark) |
| USD 930 million (2025); USD 1.02 billion (2026) | 2025 | 2026–2031 | 9.74% | Test kits, lab services, molecular and immunoassay; excludes some instruments | A competing analysis |
| USD 575.0 million (2025) | 2025 | 2026–2034 | 8.29% | Narrower kit-and-reagent-centric perimeter | Another published estimate |
Our analysis favors the USD 898–986 million range as the most defensible base. It is the only benchmark that explicitly bundles instruments, consumables, and reference-lab services, which matches how integrated producers and veterinary labs actually procure. The lower USD 575 million figure likely excludes service revenue and automated platform hardware, understating true spend. The 9.7–9.8% CAGR consensus across two independent sources strengthens confidence in the mid-to-high single-digit-plus growth trajectory.
The market segments along five primary axes: test modality, disease target, service line, product form, and end user. ELISA remains the volume workhorse, while PCR and molecular testing capture the fastest growth as labs automate and outbreaks demand subtype-level confirmation.
| Parent segment | Children |
|---|---|
| By Test | ELISA, PCR, Molecular Diagnostic Tests, Others |
| By Disease | Avian Influenza, Newcastle Disease, Infectious Bronchitis, Infectious Bursal Disease, Avian Salmonellosis, Avian Mycoplasmosis, Chicken Anemia, Others |
| By Service | Bacteriology, Virology, Parasitology, Others |
| By Product | Consumables, Reagents & Kits, Instruments, Software & Services |
| By End Use | Veterinary Reference Laboratories, On-Farm Point-of-Care, Veterinary Hospitals, Research Institutes |
North America leads the global poultry diagnostics market with approximately 39% of 2025 revenue, underpinned by the USDA's National Poultry Improvement Plan, high reference-lab density, and rapid adoption of automated molecular platforms. Asia Pacific is the fastest-growing region at an 11.4% CAGR, driven by expanding broiler output and government-backed surveillance.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.26% |
| Asia-Pacific | 0.24% |
| Latin America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | Share of 2025 revenue |
|---|---|
| North America | 39% |
| Europe | 26% |
| Asia Pacific | 24% |
| Latin America | 6% |
| Middle East & Africa | 5% |
The primary growth engine is the escalating frequency of highly pathogenic avian influenza and zoonotic outbreaks, which converts diagnostics from a discretionary cost into an operational necessity. Government surveillance programs, rising poultry protein demand in emerging economies, and lab automation reinforce the upward trajectory.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| HPAI and zoonotic outbreaks | Driver | High | Recurrent culls and sample surges sustain molecular testing demand |
| Government and NGO surveillance programs | Driver | High | USDA NPIP and EU export rules make testing mandatory |
| Rising poultry protein demand in APAC | Driver | Medium | Larger flocks multiply test volume per bird |
| ELISA/PCR automation adoption | Driver | Medium | High-throughput platforms offset technologist shortages |
| High cost of advanced diagnostics | Restraint | Medium | Limits adoption among smallholder farms |
| Limited veterinary infrastructure | Restraint | Medium | Constrains testing access in low-income regions |
| Evolving disease strains | Restraint | Medium | Requires continuous assay revalidation |
Balancing these forces, our analysis suggests demand-side drivers outweigh supply-side restraints through 2033. The key second-order effect: automation lowers per-test cost, which expands the addressable flock base and partially offsets pricing pressure on commoditized ELISA kits. Restraints are real but regionalized, concentrating in smallholder segments rather than commercial integrators who drive the bulk of volume.
The vendor landscape is medium-concentration, with a handful of global animal-health players controlling reference-lab relationships while regional kit specialists compete on price and assay breadth.
| Company | HQ | Strategic position | Notable capability |
|---|---|---|---|
| IDEXX Laboratories | USA | Global reference-lab leader | Automated ELISA and Catalyst platforms; high-throughput flock serology |
| Zoetis | USA | Integrated animal-health major | 32,000 sq ft automated reference lab in Louisville; broad portfolio |
| Thermo Fisher Scientific | USA | Molecular and immunoassay supplier | PCR reagents, assays, and lab instrumentation |
| bioMérieux | France | Molecular pathogen detection | GENE-UP real-time PCR for Salmonella and Campylobacter |
| BioChek | Netherlands | Poultry-specific ELISA specialist | Broad avian ELISA kit menu |
| Megacor Diagnostik | Austria | Niche poultry diagnostics | ELISA and rapid test kits |
Differentiation hinges on three moats: reference-lab workflow integration, assay menu breadth validated for avian matrices, and automation capability that addresses technologist shortages. Our analysis suggests vendors with closed automated ecosystems (instrument plus validated consumables) will capture disproportionate share as labs scale throughput; open-format kit suppliers risk margin compression.
Procurement decisions in poultry diagnostics hinge on four mission-critical criteria: assay sensitivity and specificity for regionally prevalent strains, turnaround time relative to outbreak-response windows, total cost per bird tested, and regulatory acceptance for export certification.
Buyers should scrutinize switching costs carefully. Automated platforms create lock-in through proprietary consumables and validated workflows; migrating between systems requires revalidation that can disrupt surveillance continuity during an outbreak. Reference labs should therefore prioritize open-format or multi-vendor-compatible systems where strain diversity is high.
Regulatory compliance is non-negotiable. In the USA, NPIP participation and USDA avian-influenza protocols govern interstate movement; in the EU, accredited testing is a precondition for export certificates. Operators should verify that any diagnostic adopted carries the accreditation required for their target markets, because non-conformant testing can suspend flock certification. Finally, on-farm point-of-care devices reduce turnaround but trade off sensitivity; they are best deployed as triage tools feeding confirmatory reference-lab PCR.
The balance of evidence favors a constructive outlook: the global poultry diagnostics market is a structurally growing, regulation-anchored sector with a credible 9.8% CAGR to 2033. The strongest counter-argument is that ELISA price erosion could compress revenue growth even as test volumes rise, particularly if Asian kit manufacturers scale aggressively. Our analysis nonetheless judges volume expansion and molecular-mix shift to outweigh deflation, because PCR and point-of-care carry higher per-test value and are growing faster than the legacy ELISA base.
A second-order implication deserves emphasis: automation is not merely a cost lever but a market-access lever. Labs that automate can serve smaller farms profitably, widening the addressable base beyond integrated producers. Vendors that fail to automate will cede the long tail of the market to point-of-care specialists.
What would change our conclusion? A sustained decline in HPAI outbreak frequency, or a breakthrough in multiplexed low-cost on-farm PCR that collapses reference-lab pricing, would materially lower the forecast. Conversely, mandatory genomic surveillance mandates in major exporting nations would accelerate upside beyond our base case.
While this overview frames the strategic landscape, precise sub-segment forecasting, country-level regulatory mapping, and vendor share modeling require the full report's granular datasets.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 9.8% from 2020-2034 |
| Segmentation |
|
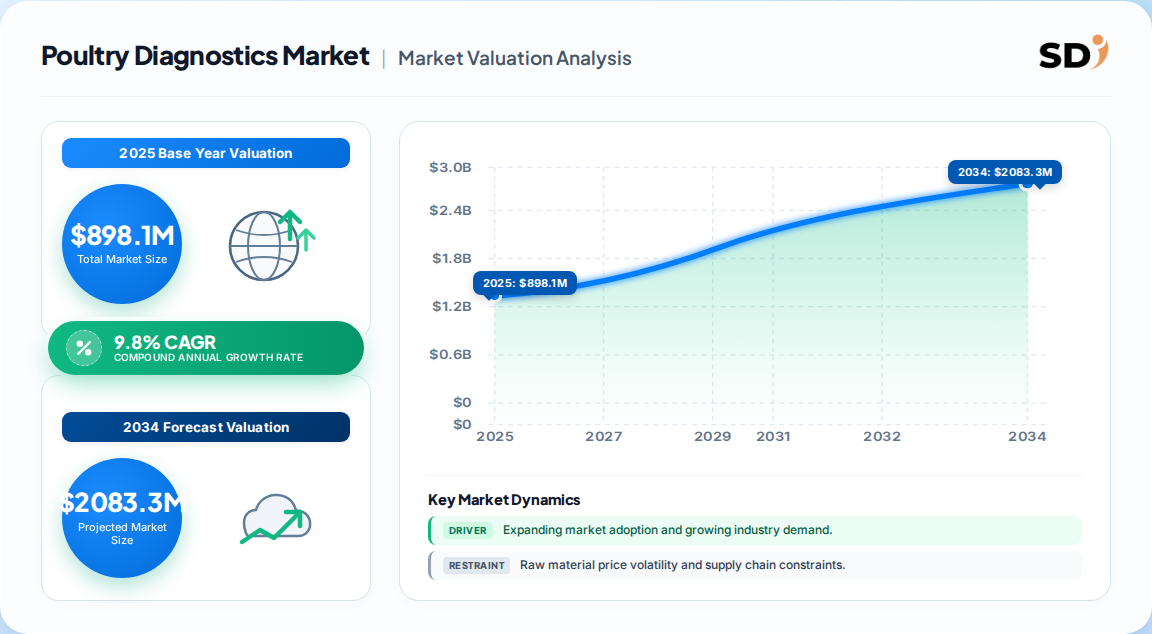
The global poultry diagnostics market is estimated at USD 986.1 million in 2026, up from USD 898.1 million in 2025, according to published benchmarks. It is projected to reach USD 1,899.4 million by 2033 at a 9.8% CAGR.
ELISA dominates with roughly 57% of 2025 revenue, favored for cost-efficient high-throughput flock serology. PCR is the fastest-growing modality at a 10.1% CAGR, driven by outbreak subtyping and export-certification requirements.
Asia Pacific is the fastest-growing region at an 11.4% CAGR, driven by expanding broiler output, government surveillance funding, and export-certification testing. North America remains the largest region at approximately 39% of 2025 revenue.
Leading vendors include IDEXX Laboratories, Zoetis, Thermo Fisher Scientific, bioMérieux, BioChek, and Megacor Diagnostik. Competition centers on automation, assay menu breadth, and reference-lab workflow integration.
Recurring highly pathogenic avian influenza outbreaks, mandatory government surveillance programs such as the USDA NPIP, rising poultry protein demand in emerging economies, and lab automation adoption are the principal growth drivers through 2033.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research program applies a 70/30 primary-to-secondary split, prioritizing direct validation with value-chain participants. We conducted in-depth interviews across reagent and kit manufacturers, automated instrument suppliers, veterinary reference laboratories, on-farm point-of-care device makers, and regional distributors. Decision-maker designations included VP of Sourcing, Heads of R&D and Assay Development, Technical Directors of Reference Laboratories, and Commercial Operations Leads. Structured questionnaires captured procurement criteria, turnaround-time tolerances, and regulatory-acceptance requirements.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Assay Development Heads | 35% |
| Procurement & Sourcing Leads | 30% |
| Technical Lab Directors | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Reagent & Kit Manufacturers | 40% |
| Instrument & Platform Suppliers | 25% |
| Veterinary Reference Laboratories | 20% |
| Distributors & On-Farm Device Makers | 15% |
Secondary validation draws on official multilateral databases including UN Comtrade, WTO trade statistics, US ITC data, and Eurostat agricultural and veterinary trade flows. Corporate annual filings (10-K, SEC submissions, investor presentations) informed capacity and revenue mapping. Patent databases and recognized technical standards from the World Organisation for Animal Health (WOAH) and national poultry improvement programs anchored regulatory and assay-validation benchmarks.
We run simultaneous top-down and bottom-up models. The top-down approach allocates macroeconomic poultry-production value across diagnostic intensity by region and species. The bottom-up approach models manufacturer capacity, product pricing, and end-use consumption at the flock and laboratory level. Divergences are reconciled through iterative triangulation to produce a single defensible base-year value and forecast path.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |