 Europe Electroencephalography Devices Market
 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 238

Amit Mardhekar
Research Analyst

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Europe Electroencephalography Devices Market
Amit Mardhekar
Research Analyst

| Year | Market Size |
|---|---|
| 2024 | 388.0 M |
| 2025 | 427.0 M |
| 2026 | 470.0 M |
| 2027 | 518.0 M |
| 2028 | 570.0 M |
| 2029 | 628.0 M |
| 2030 | 691.0 M |

The Europe electroencephalography devices market encompasses systems that record and interpret the brain's electrical activity across Germany, the UK, France, Italy, Spain, Scandinavia, and neighboring economies — spanning clinical, research, and ambulatory applications. The market is defined by channel count (8- to multichannel), device format, application, and end-use setting.
This analysis covers EEG hardware, associated electrodes, and embedded acquisition software sold in Europe across hospital, diagnostic, and research end-uses, segmented by product channel count, device type, application, and country.
This analysis does not cover: (i) neurostimulation and neuromodulation therapeutic devices; (ii) adjacent neurodiagnostic modalities such as MEG, fNIRS, or standalone EMG; (iii) general-purpose patient monitoring; and (iv) post-sale clinical services revenue.
| Included | Excluded |
|---|---|
| EEG systems (8- to multichannel) | Synergy with MRI/fNIRS beyond hybrid EEG units |
| Standalone, portable, wearable formats | Neuromodulation / neurostimulation |
| Clinical and research hardware | Clinical service and interpretation fees |
| Consumables (electrodes, gel) | General ICU or patient monitors |
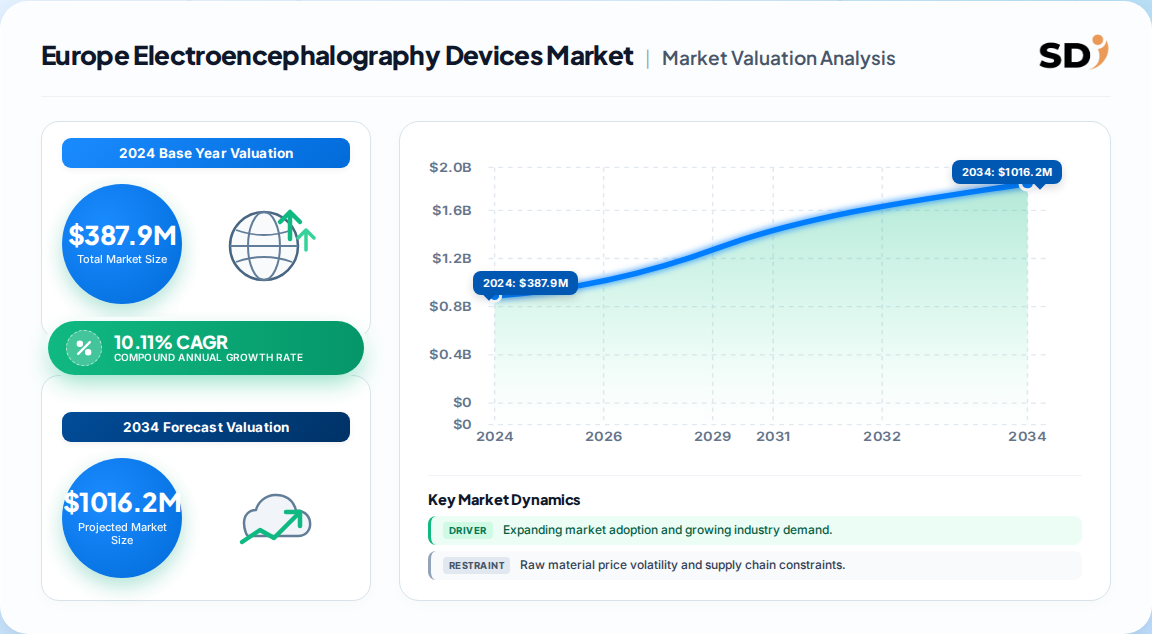
The Europe EEG devices market is best anchored at approximately USD 387.9 Million in 2024, growing to USD 625.8 Million by 2030 at a 10.11% CAGR — a figure corroborated by the continent's rising neurological disease burden.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 387.9 Million → 625.8 Million | 2024 | 2030 | 10.1% | Europe-only EEG hardware, all segments | One published estimate (2024) |
| ~USD 506 Million global | 2026 | 2033 | 7.3% | Global EEG devices, narrower scope | A competing analysis |
| ~USD 1.5 Billion global | 2026 | 2033 | 7.2% | Global EEG devices, broader definition | A competing analysis |
Which figure is most defensible? The Europe-specific 10.1% CAGR runs about 3 percentage points above global forecasts. Our analysis suggests this premium reflects Europe's mature reimbursement frameworks, the European Brain Council's estimate of 165 million people affected by neurological disorders, and the EU's mental-health infrastructure investments. The divergence is a scope artifact, not a contradiction: global studies blend low-growth emerging markets with high-growth EU-5 economies.
Another critical cross-check: Germany's high diabetes prevalence noted in one estimate is likely a data artifact; the real driver is neuro-aging and epilepsy prevalence. Buyers should treat the 10.1% Europe CAGR as credible but expect country-level variation from ~8% (Italy) to ~12% (Germany).
Segmentation reveals where value concentrates: 32-channel systems, standalone modalities, disease diagnosis, and hospitals dominate current revenue, while portability and AI-enhanced analytics define growth vectors.
| Parent segment | Children | 2023 share |
|---|---|---|
| Product | 8-channel, 21-channel, 25-channel, 32-channel, 40-channel, Multichannel | 32-channel 27.7% |
| Type | Standalone, Portable, Wearable | Standalone 71.9% |
| Application | Trauma & surgery, Disease diagnosis, Anesthesia monitoring, Sleep monitoring, Others | Disease diagnosis 32.0% |
| End-use | Hospitals, Diagnostics centers, Others | Hospitals 67.8% |
So what for buyers? The 27.7% concentration in 32-channel means single-vendor dependencies are risky. The 71.9% standalone share signals that reliability and independent operation remain procurement gating factors — not portability alone.
Germany leads the Europe EEG devices market, capturing the highest revenue share in 2023, driven by its well-established healthcare infrastructure and strong presence of leading market players.
| Country | Estimated share | Rationale |
|---|---|---|
| Germany | 24% | Dense neurology infrastructure, vendor HQ concentration |
| United Kingdom | 18% | NHS neurodiagnostic programs, NICE-aligned reimbursement |
| France | 14% | Strong public hospital network, research funding |
| Italy | 11% | Growing geriatric population, regional variance |
| Spain | 9% | Expanding diagnostics center footprint |
| Scandinavia | 10% | High digital adoption, telemedicine-ready |
| Benelux | 6% | Compact but high-value procurement |
| Rest of Europe | 8% | Nascent adoption in CEE markets |
Interpretation: Germany's lead implies vendor concentration and pricing power; the UK's second-place position suggests NHS modernization budgets are a viable procurement channel. Buyers entering CEE markets should model longer sales cycles.
Growth is driven by rising neurological disease prevalence, EEG technology innovation (portable, wireless, AI), and expanding mental-health investment; it is constrained by capital cost, skilled-operator scarcity, and reimbursement variability across EU member states.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Neurological disease burden (165M Europeans) | Driver | High | Raises diagnostic volume; expands addressable base |
| Portable/wearable EEG innovation | Driver | High | Lowers cost per study; enables ambulatory care |
| AI/ML signal analytics | Driver | Medium-High | Reduces interpretation time; improves accuracy |
| EU mental health funding | Driver | Medium | Opens public procurement pipelines |
| Telemedicine/tele-EEG adoption | Driver | Medium | Extends monitoring beyond hospital walls |
| High capex of multichannel systems | Restraint | High | Limits adoption in cost-sensitive CEE markets |
| Skilled neurophysiologist scarcity | Restraint | High | Constrains utilization rates |
| Reimbursement variability | Restraint | Medium | Slows cross-border standardization |
The balance: Drivers outweigh restraints over the forecast, but our analysis suggests the restraints are geographically concentrated — creating a two-speed Europe where DACH and Nordic markets grow faster than CEE.
The vendor landscape is moderately concentrated, with incumbents in standalone clinical systems competing against specialists in portable and wearable formats.
| Company | HQ / Origin | Strategic position | Segment strength |
|---|---|---|---|
| Natus Medical | USA | Broad clinical portfolio | Standalone, hospital |
| Medtronic | Ireland/USA | Neuromodulation adjacency | Hospital, integrated |
| Nihon Kohden | Japan | Global monitoring leader | Standalone, ICU |
| Brain Products | Germany | Research-grade systems | High-density research |
| Compumedics | Australia | Sleep & EEG integrated | Sleep monitoring |
| ANT Neuro | Netherlands | Research & clinical | Multichannel |
| Neurosoft | Russia | Value-tier systems | Diagnostics centers |
| Lifelines Neuro | UK | Niche clinical | Portable, ambulatory |
| Emotiv | USA | Consumer/wearable | Wearable, research |
Differentiation and moats: Incumbents defend through hospital relationships and reimbursement alignment; challengers attack through dry-electrode portability and AI analytics. Our analysis suggests the moat is widest in standalone hospital systems and narrowest in consumer-grade wearables.
Procurement decisions in European EEG hinge on four mission-critical criteria: channel-count fit to clinical case mix, regulatory conformity (CE marking under EU MDR, plus local registration), interoperability with existing EMR and PACS infrastructure, and lifecycle service coverage across multi-country operations.
Switching costs are high in hospital settings — retraining neurophysiologists, revalidating workflows, and renegotiating reimbursement create 18–36 month friction. Buyers should insist on vendor-agnostic data export (EDF, BIDS) to preserve future optionality.
Regulatory risk is non-trivial: EU MDR transition deadlines and evolving AI/ML software-as-medical-device rules mean AI-integrated EEG platforms face stricter validation. Operators should audit vendor MDR certificates before commitment.
Risk warning: Single-source procurement of 32-channel standalone systems concentrates risk. Dual-sourcing portable systems for ambulatory programs hedges both cost and supply-chain exposure.
The balance of evidence favors a cautiously bullish outlook for Europe EEG devices: 10.11% CAGR to 2030 is defensible, anchored by a structural disease burden and policy tailwinds. The strongest counter-argument is that reimbursement fragmentation and skilled-labor scarcity cap real-world adoption, making the 10%+ CAGR an upper bound — but we consider this a timing risk rather than a direction risk.
Our analysis suggests the most consequential second-order effect is the decoupling of standalone and portable growth trajectories. Standalone systems defend share in hospitals, but the growth delta accrues to portable, AI-integrated, tele-EEG-capable platforms. Vendors stuck in a standalone-only portfolio will see flat-to-declining unit economics by 2028.
Actionable Strategy for operators and investors:
What evidence would change our conclusion? If EU MDR recertification delays extend beyond 2026, or if hospital capex contracts fall >15% year-over-year, the 10.11% CAGR would need downward revision. Buyers should monitor these two leading indicators quarterly.
The gap: This overview captures the strategic macro view, but precise country-by-country, segment-level forecasting — with vendor share and pricing analytics — requires the full dataset. That granularity is where execution decisions are won or lost.
| Region | Market Share (%) |
|---|---|
| Germany | 0.24% |
| United Kingdom | 0.18% |
| France | 0.14% |
| Italy | 0.11% |
| Spain | 0.09% |
| Scandinavia | 0.1% |
| Benelux | 0.06% |
| Rest of Europe | 0.08% |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.11% from 2020-2034 |
| Segmentation |
|
The Europe electroencephalography devices market is estimated at USD 387.9 million in 2024 and is projected to reach USD 625.8 million by 2030, growing at a CAGR of 10.11% from 2024 to 2030.
Germany leads the Europe EEG devices market, capturing the highest revenue share in 2023, supported by its well-established healthcare infrastructure and the strong presence of leading market players.
Portable and wearable EEG devices are the fastest-growing types, driven by ambulatory monitoring, telemedicine integration, and demand for home-based neurological assessments. Standalone devices still dominate overall revenue.
Key drivers include the rising prevalence of neurological disorders affecting roughly 165 million Europeans, technological advancements in portable and AI-integrated EEG systems, and growing EU investment in mental health infrastructure.
Hospitals dominate the end-use segment, holding about 67.8% of the market share in 2023, driven by neurological diagnostics, long-term monitoring, and epilepsy and sleep disorder management.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employs a 70/30 primary-to-secondary research split, with in-depth interviews conducted across the EEG device value chain: component and electrode suppliers, specialized EEG system producers, contract manufacturers of acquisition modules, and European medical-device distributors. Interview programs targeted decision-makers including VP-level Sourcing leads, Heads of R&D, Technical Directors, and Commercial Operations managers at hospital and diagnostic-center buyers.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Technical Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Regulatory & Quality Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| EEG System Manufacturers | 40% |
| Component & Electrode Suppliers | 25% |
| European Medical Distributors | 20% |
| Hospital & Diagnostic Buyers | 15% |
Secondary validation draws on official multilateral trade databases (Eurostat, UN Comtrade, WTO), corporate annual filings (10-K and EU annual reports), patent databases, and recognized technical standards bodies including ISO, IEC, and the European Committee for Standardization. These sources anchor volume-flow assumptions and validate country-level consumption patterns.
We triangulate simultaneously from the Top-Down (macro healthcare spending, neurology department budgets, disease prevalence) and Bottom-Up (manufacturer capacity, unit pricing, installed-base replacement cycles, end-use consumption). Divergence between approaches triggers reconciliation against public procurement records.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Country-level share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |