 Us Wine Market
US Wine Market Size, Share & Forecast to 2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 209

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Wine Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2020 | 63.79 B |
| 2025 | 79.84 B |
| 2026 | 83.50 B |
| 2030 | 99.92 B |
| 2034 | 119.6 B |

The US wine market encompasses the production, distribution, and retail of all wine categories — still, sparkling, and dessert — across on-trade and off-trade channels. It serves consumers across the full price spectrum through wholesalers, retailers, restaurants, wineries, and direct-to-consumer platforms.
This report covers still, sparkling, and dessert wine sold through on-trade and off-trade channels in the United States, segmented by color, product type, and distribution. This analysis does not cover craft beer, spirits, cider, or non-alcoholic beverages except where they directly compete for wine occasions.
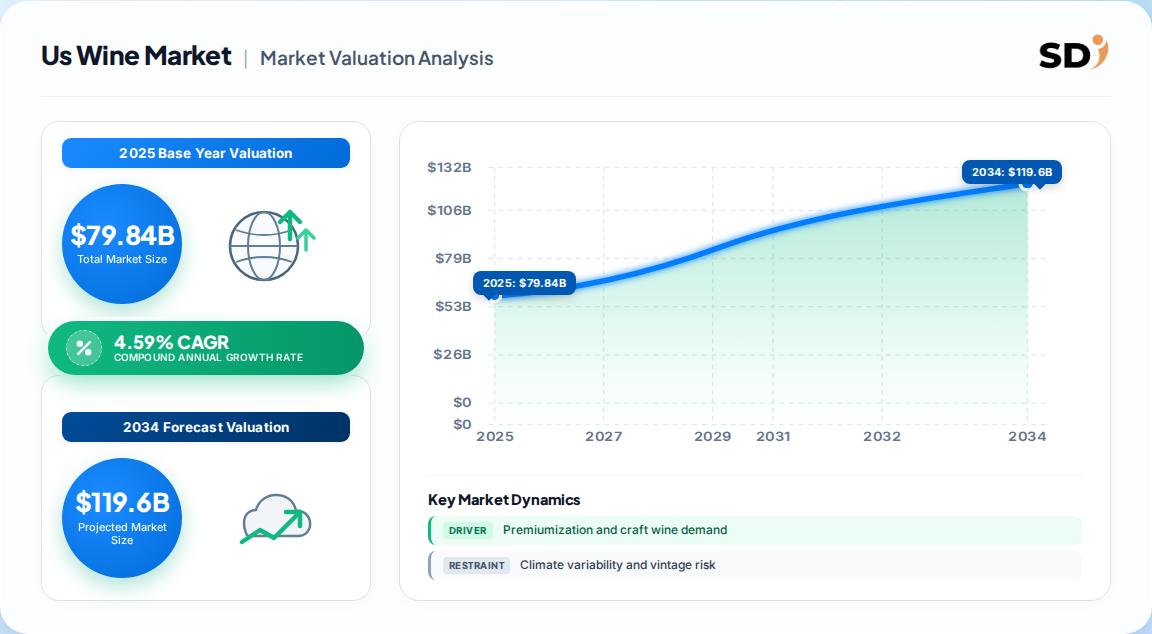
The US wine market was valued at 79.84 Billion in 2025, growing to 83.50 Billion in 2026 and projected to reach 119.56 Billion by 2034. This represents a 4.59% CAGR over the forecast period.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 79.84 Billion | 2025 | 2034 | 4.59% | Total wine market, all channels | One published estimate |
| 75.3 Billion | 2024 | 2033 | 8.8% | Total wine market, all channels | A competing analysis |
| 28.0 Billion | 2026 | — | 0.9% | Winery industry revenue only | IBISWorld |
Our analysis suggests the 4.59% CAGR estimate is the most defensible. It aligns with the long-run premiumization trend while acknowledging that per-capita consumption is declining — 4.5 liters in 2024 versus 4.7 liters in 2023. The 8.8% figure likely overstates growth by conflating value premiumization with volume expansion. IBISWorld's 28.0 Billion reflects winery-gate revenue, not total consumer spend. The divergence implies buyers should model volume stagnation with value growth — a critical distinction for capacity planning.
The market segments by product type (still, sparkling, dessert), color (red, white, rosé), and distribution channel (on-trade, off-trade). Still wine dominates at 71.6%, but sparkling is growing fastest.
| Parent Segment | Children | Share / Insight |
|---|---|---|
| Product Type | Still Wine, Sparkling Wine, Dessert Wine | Still 71.6%; Sparkling 6.2% CAGR |
| Color | Red, White, Rosé | Red 47.8% |
| Distribution Channel | On-Trade, Off-Trade, DTC | Off-trade ~76.6% |
What this implies: The still wine dominance is a volume story, but the growth is in sparkling and premium tiers. Suppliers should allocate shelf space and marketing spend toward sparkling and rosé to capture the fastest-growing demand.
The South leads the US wine market with a 28.6% share in 2025, followed by the West at 26.2%, Midwest at 23.8%, and Northeast at 21.4%. The South's leadership reflects growing wine culture, tourism, and a expanding local winery ecosystem.
| Region | Market Share (%) |
|---|---|
| South | 0.29% |
| West | 0.26% |
| Northeast | 0.21% |
| Midwest | 0.24% |
Our analysis suggests the South's lead is structural, not cyclical. Population growth, favorable regulatory shifts, and wine tourism investment in Texas and Virginia are creating a durable consumption base. The West remains the production powerhouse but faces climate risk and water constraints that could cap long-term supply growth.
Premiumization, DTC channel expansion, and Millennial engagement drive growth. Climate variability, alternative beverage competition, and regulatory complexity restrain it. The net balance favors modest value growth despite volume headwinds.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Premiumization and craft demand | Driver | High | Consumers trading up to premium tiers, raising revenue per unit |
| E-commerce and DTC expansion | Driver | High | State regulatory changes enable broader digital distribution |
| Millennial and Gen Z engagement | Driver | Medium | 72.95M Millennials drive digital discovery and premium gifting |
| Climate variability | Restraint | High | Drought, wildfires affect grape quality and yield |
| Alternative beverage competition | Restraint | High | Craft spirits, RTDs, hard seltzers compete for occasions |
| Multi-state regulatory complexity | Challenge | High | Patchwork of state laws adds operational costs |
| Import competition | Challenge | Medium | Imports pressure margins below 15 per bottle |
The balance: Drivers are structural and premium-focused; restraints are volume-focused. This implies a value-growth, volume-flat market — operators should optimize for margin per unit rather than case volume.
E. & J. Gallo, Constellation Brands, and The Wine Group dominate US wine production, while Duckhorn Portfolio leads luxury. Competitive moats rest on distribution scale, brand portfolio breadth, and vineyard access.
| Company | Segment Focus | Strategic Position |
|---|---|---|
| E. & J. Gallo Winery | Mass and premium | Largest US winery; broad portfolio and distribution scale |
| Constellation Brands | Premium and imported | Brand strength in premium tiers; acquisition-driven growth |
| The Wine Group | Value and mid-tier | Volume leader; cost-efficient production |
| Duckhorn Portfolio | Luxury | Acquired by Butterfly Equity for 1.95 Billion in 2024 |
Differentiation: Scale players compete on distribution and cost; luxury players compete on brand equity and estate provenance. Our analysis suggests the middle tier — 15–25 per bottle — is the most vulnerable, squeezed by premiumization above and value imports below.
Buyers must navigate the three-tier distribution system, state-level DTC shipping restrictions, and rising compliance costs. Procurement risks include vintage variability, import price volatility, and retailer consolidation. Switching costs are high for national distributors but lower for DTC and on-trade buyers.
Regulatory compliance is mission-critical: DTC shipping is permitted in only a subset of states, and alcohol control board regulations vary significantly. Operators should prioritize suppliers with certified sustainable vineyard acreage and transparent provenance — both command premium shelf placement and pricing. Buyers should also model low- and no-alcohol wine as a hedge against health-conscious consumption shifts.
The balance of evidence favors a premium-led, value-growth thesis for the US wine market. The 4.59% CAGR is credible because it reflects premiumization offsetting volume decline. The strongest counter-argument is that per-capita consumption is falling faster than premiumization can compensate — if Gen Z continues to substitute cocktails and non-alcoholic alternatives, the 8.8% bullish estimate becomes unreachable and even 4.59% may prove optimistic.
Actionable Strategy:
What would change our conclusion: A sustained rebound in per-capita consumption among Millennials and Gen Z, or federal DTC regulatory reform, would justify a more bullish stance. Conversely, accelerated volume decline below 4.0 liters per capita would push the market toward the low end of the forecast range.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 4.59% from 2020-2034 |
| Segmentation |
|
The US wine market reached 79.84 Billion in 2025 and is projected to reach 119.56 Billion by 2034, growing at a 4.59% CAGR.
Still wine dominates with a 71.6% share in 2025, while red wine leads color at 47.8%. Sparkling wine is the fastest-growing product type at 6.2% CAGR.
The South leads with a 28.6% share in 2025, driven by wine tourism and a growing winery ecosystem in Texas, Florida, and Virginia.
Key trends include premiumization, DTC channel expansion, rising demand for low-alcohol and non-alcoholic wines, and growth in organic and sustainable wine production.
Leading players include E. & J. Gallo Winery, Constellation Brands, The Wine Group, and Duckhorn Portfolio.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split. We conducted in-depth interviews with key stakeholders across the wine value chain, including grape growers, winery operators, national distributors, specialty retailers, and on-trade buyers. Decision-maker designations interviewed included VP of Sourcing, Heads of Winemaking, Technical Directors, and Commercial Operations Leads. This fieldwork provided granular insights into procurement dynamics, channel margins, and regulatory compliance challenges.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Sourcing & Procurement VPs | 35% |
| Winemaking & Production Heads | 30% |
| Commercial Operations Leads | 20% |
| Regulatory & Compliance Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Grape Growers & Vineyards | 30% |
| Wineries & Producers | 40% |
| Distributors & Wholesalers | 20% |
| Retailers & On-Trade Buyers | 10% |
We validated findings against official multilateral trade databases, including UN Comtrade, WTO, US ITC, and Eurostat, for wine import/export flows. Corporate annual filings (10-K, SEC filings, investor presentations) from major producers informed competitive benchmarking. We also referenced patent databases and industry association standards for sustainability and organic certification.
Our demand modeling triangulates top-down macroeconomic and industry segment allocation with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. This simultaneous approach ensures market sizing accuracy and forecast reliability.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |