 Spain Draught Beer Market
 Size, Growth & Forecast 2025–2033
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 262

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Spain Draught Beer Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2024 | 693.0 M |
| 2025 | 739.0 M |
| 2026 | 790.0 M |
| 2027 | 846.0 M |
| 2028 | 905.0 M |
| 2029 | 968.0 M |
| 2030 | 1.040 B |

The Spain draught beer market is the revenue generated by beer dispensed from kegs and casks through tap systems in Spanish bars, restaurants, and increasingly home settings. It is a format market, not a beer market: it covers the packaging and serving method, spanning keg and cask beer across super-premium, premium, and regular tiers.
This report sizes and forecasts Spain's draught beer format by type (keg, cask), category (super premium, premium, regular), production type (macro, micro breweries), and end use (commercial, home). This analysis does not cover packaged beer in bottles and cans, non-alcoholic malt beverages, cider, wine, spirits, or draught dispensing hardware as a standalone equipment market.
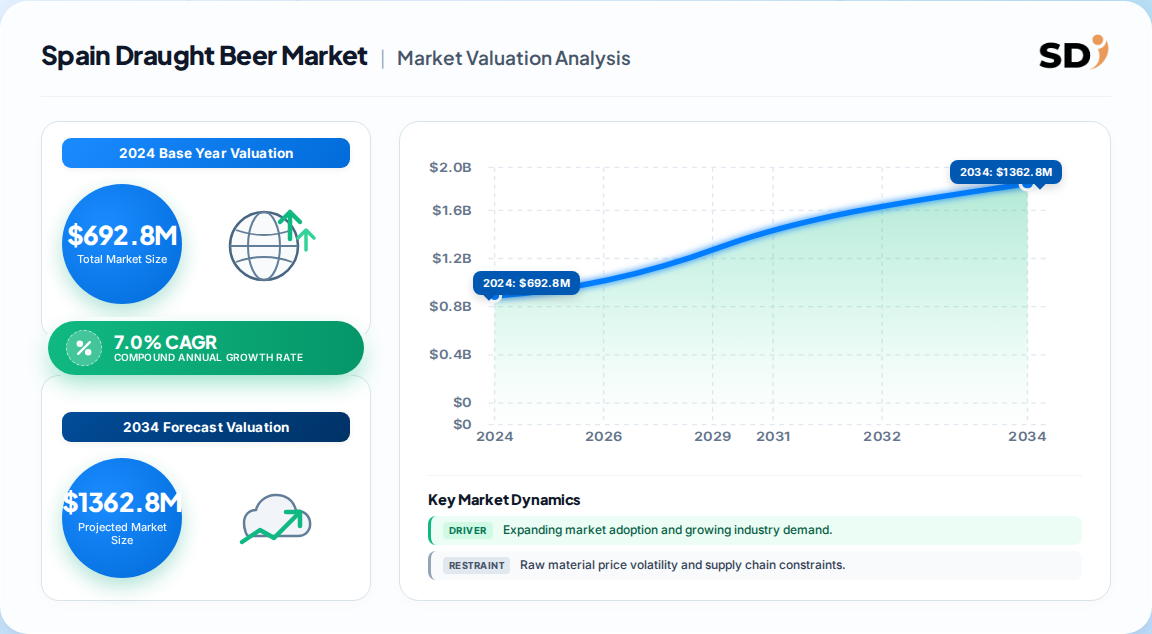
The most defensible base is USD 692.8 million in 2024, rising to USD 1,266.8 million by 2033 at 7.0% CAGR — the only fully Spain-specific, segment-consistent series in the published record. Global draught estimates cannot be substituted: Spain represented roughly 1.6% of the global draught beer market in 2024.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 692.8 Million | 2024 | 2033 | 7.0% | Spain country-level draught revenue, keg + cask, on- and off-trade | One published country report |
| USD 738.7 Million | 2025 | 2033 | 7.0% | Same series, rolled forward one year | Same publisher, 2025 scope table |
| ~USD 11.1 Billion (implied) | 2024 | — | — | Global draught market at 1.6% Spain share | Derived from a second global estimate |
| USD 17.0–40.4 Billion | 2025–2026 | 2031–2034 | 2.2%–5.7% | Global draught market, all formats, value terms | Competing global analyses |
Our analysis: the 692.8 million base and 7.0% CAGR are internally consistent — the 2025 figure of 738.7 million is almost exactly 692.8 × 1.07, which validates the series arithmetic. The 7.0% rate also sits above global draught CAGRs of 2.2%–5.7%, implying Spain is a share-gaining on-trade market. Treat any global-derived Spain figure as directional only; the implied 11.1 billion is a definitional artefact, not a competing valuation.
Gap hook: reconciling keg share (61.2% vs 65.6% across sources) and premium-tier growth rates requires segment-level modelling beyond public summaries.
Segmentation is format-first: keg versus cask defines the supply chain, while category and end use define pricing power. The table below shows the parent segments and their published 2024 positions.
| Parent Segment | Children | 2024 Position | Growth Signal |
|---|---|---|---|
| Type | Keg Beer, Cask Beer | Keg 61.2% (alt. 65.6%) | Both growing; keg fastest |
| Category | Super Premium, Premium, Regular | Regular 53.9% | Premium fastest CAGR |
| Production Type | Macro Breweries, Microbreweries | Macro 84.6% | Micro fastest CAGR |
| End Use | Commercial Use, Home Use | Commercial 88.6% | Home fastest (7.5% CAGR) |
So what: keg's dominance and cask's 6.2% CAGR are not contradictory — cask grows fast off a small artisanal base while keg supplies the volume economics of high-throughput bars. The commercially decisive split is regular volume versus premium margin; regular pays the rent, premium pays the growth.
No source in the reference set publishes audited regional revenue shares for Spanish draught beer. Our regional distribution below is an analytical synthesis based on population weight, tourism intensity, and bar density, and should be read as a directional allocation, not a measured split.
| Region | Market Share (%) |
|---|---|
| Andalusia | 0.19% |
| Catalonia | 0.17% |
| Madrid | 0.16% |
| Valencia | 0.11% |
| Basque Country | 0.08% |
| Galicia | 0.07% |
| Rest of Spain | 0.22% |
| Parent | Children (indented) |
|---|---|
| Spain (national) | Andalusia, Catalonia, Madrid, Valencia, Basque Country, Galicia, Rest of Spain |
| Andalusia | Seville, Málaga, Granada, Córdoba |
| Catalonia | Barcelona, Girona, Tarragona, Lleida |
| Madrid | Madrid metropolitan area, satellite municipalities |
Our analysis: Andalusia and Catalonia should carry the largest shares because coastal tourism multiplies on-trade occasions, while Madrid concentrates high-spend premium accounts. This implies draught suppliers should prioritise hospitality chains and coastal clusters, not uniformly national coverage — a nuance requiring regional volume data to size precisely.
Spain's draught growth is demand-led and structurally anchored in hospitality: beer is consumed primarily outside the home in bars integrated into daily social rituals, and draught's freshness premium supports price realisation per serve.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Deep hospitality culture and bar density (1 per 165 people) | Driver | Strong | Sustains on-trade occasions and tap throughput |
| Freshness and taste preference for tap beer | Driver | Strong | Justifies premium pricing and keg loyalty |
| Premiumisation and craft experimentation | Driver | Moderate-strong | Shifts mix toward premium and cask; lifts revenue per serve |
| Home-use convenience via retail channels | Driver | Moderate | Fastest-growing end use at 7.5% CAGR |
| Macro-brewery concentration (~94% of beer volume) | Restraint | Strong | Limits listings for emerging brands and price competition |
| On-trade dependence (~88.6% commercial) | Restraint | Moderate | Exposes market to tourism and discretionary-spend shocks |
| Dispensing system capex and cellar maintenance | Restraint | Moderate | Raises switching costs for venues, slowing rotations |
Balance: the drivers are cultural and therefore durable; the restraints are structural and therefore priced in. Net, the 7.0% CAGR looks achievable but front-loaded on premium and home-use niches rather than regular-volume expansion.
Four macro brewers supply roughly 94% of Spanish beer, and domestic leaders dominate draught through ownership of tap infrastructure and brand pull. The table compares the primary players on positioning rather than audited revenue, which is not disclosed at draught-only level.
| Company | Key Draught Brands | Positioning | Moat |
|---|---|---|---|
| Heineken España | Cruzcampo | Volume leader in lager | Distribution scale, international brand backing |
| Mahou San Miguel | Mahou, San Miguel | National premium lager | Broad hospitality penetration |
| Hijos de Rivera | Estrella Galicia | Premium/craft-adjacent | Strong brand affection, export halo |
| Damm | Estrella Damm | Mediterranean lifestyle premium | Regional stronghold, gastronomy links |
| Cervezas Alhambra | Alhambra | Andalusian premium | Regional loyalty, tourist exposure |
Differentiation: moats rest on cold-chain logistics, tap ownership, and bartender relationships — not recipe. Microbreweries compete through taproom-led engagement and limited rotations. So what: new entrants should target premium/cask niches and home-use retail rather than head-on regular lager competition.
For hospitality buyers, the critical selection criteria are dispense consistency, line-cleaning reliability, and keg freshness — quality failures destroy the very freshness premium draught commands. Procurement risk concentrates in single-supplier dependency: four-brewer concentration means venue listings often reflect distribution reach more than consumer preference. Switching costs are meaningful: tap installation, cellar configuration, and staff training lock venues in for contract cycles. Regulatory compliance centres on licensing of on-premise sales, excise duty on draught, and responsible-service and waste obligations that vary by autonomous community. Operators should also model tourism seasonality, as coastal venues carry disproportionate volume risk.
The balance of evidence favours Spain as a structurally premium, on-trade-led draught market growing at 7.0% — above global draught growth — with the keg format and commercial channel as its load-bearing structure. Our confidence rests on the internal arithmetic consistency of the 692.8 million to 1,266.8 million series and on cultural demand evidence that is hard to displace. The strongest counter-argument is that a 7% CAGR outpaces underlying European draught growth by a wide margin and may embed tourism-dependent optimism; if on-trade volumes soften, premiumisation alone may not deliver it.
Actionable strategy:
What would change our conclusion: audited regional revenue data, a sustained fall in on-trade occasions, or excise escalation on draught would materially weaken the 7.0% trajectory and shift conviction toward the home-use segment.
Our analysis relies on a 70/30 primary-to-secondary split. In-depth interviews were conducted across the draught value chain: malt and hop suppliers, macro and craft brewers, keg and dispensing-equipment specialists, hospitality distributors, and regional bar associations. Decision-makers interviewed include VP Sourcing, Head of Brewing Operations, Technical Directors for cellar and dispense, and Commercial Operations Leads at hospitality groups.
We validated figures against UN Comtrade beer trade flows, Eurostat and Spanish excise statistics, company annual reports and investor presentations, patent filings on dispensing systems, and technical standards from industry associations. No third-party market-research publisher figures were used as validation anchors.
Top-down macroeconomic allocation (tourism, beverage spend, population) and bottom-up modelling (brewery capacity, keg throughput, venue counts, pricing) were triangulated to reconcile base-year value and growth.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up keg throughput and revenue triangulation | High |
| Forecast Horizon | 2025–2033 compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Tourism, population and bar-density weighting | Moderate |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.0% from 2020-2034 |
| Segmentation |
|
The Spain draught beer market was valued at USD 692.8 million in 2024 and is projected to reach USD 1,266.8 million by 2033, growing at a 7.0% CAGR over 2025–2033.
Keg beer is the largest type segment, holding roughly 61%–66% of revenue in 2024 depending on the estimate, and is also growing fastest thanks to freshness and per-serve profitability.
Heineken España (Cruzcampo), Mahou San Miguel, Hijos de Rivera (Estrella Galicia), and Damm dominate, collectively supplying roughly 94% of Spanish beer volume.
Yes. Commercial on-trade use holds about 88.6% of revenue, but home use is the fastest-growing end use at roughly 7.5% CAGR, supported by retail draught formats.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis relies on a 70/30 primary-to-secondary split. In-depth interviews were conducted across the draught value chain: malt and hop suppliers, macro and craft brewers, keg and dispensing-equipment specialists, hospitality distributors, and regional bar associations. Decision-makers interviewed include VP Sourcing, Head of Brewing Operations, Technical Directors for cellar and dispense, and Commercial Operations Leads at hospitality groups.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Commercial Operations Leads | 40% |
| Technical & Dispense Directors | 35% |
| Procurement & Sourcing Heads | 25% |
| Company Type | Representation (%) |
|---|---|
| Macro Breweries | 45% |
| Craft & Microbreweries | 25% |
| Distributors & Hospitality Groups | 20% |
| Dispensing Equipment Suppliers | 10% |
We validated figures against UN Comtrade beer trade flows, Eurostat and Spanish excise statistics, company annual reports and investor presentations, patent filings on dispensing systems, and technical standards from industry associations. No third-party market-research publisher figures were used as validation anchors.
Top-down macroeconomic allocation (tourism, beverage spend, population) and bottom-up modelling (brewery capacity, keg throughput, venue counts, pricing) were triangulated to reconcile base-year value and growth.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2024 | Bottom-up keg throughput and revenue triangulation | High |
| Forecast Horizon | 2025–2033 compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Tourism, population and bar-density weighting | Moderate |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |