 Us Plant Based Meat Market
: 2025 Size, Trends & 2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 247

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Us Plant Based Meat Market
Sakshi Gurunule
Research Associate

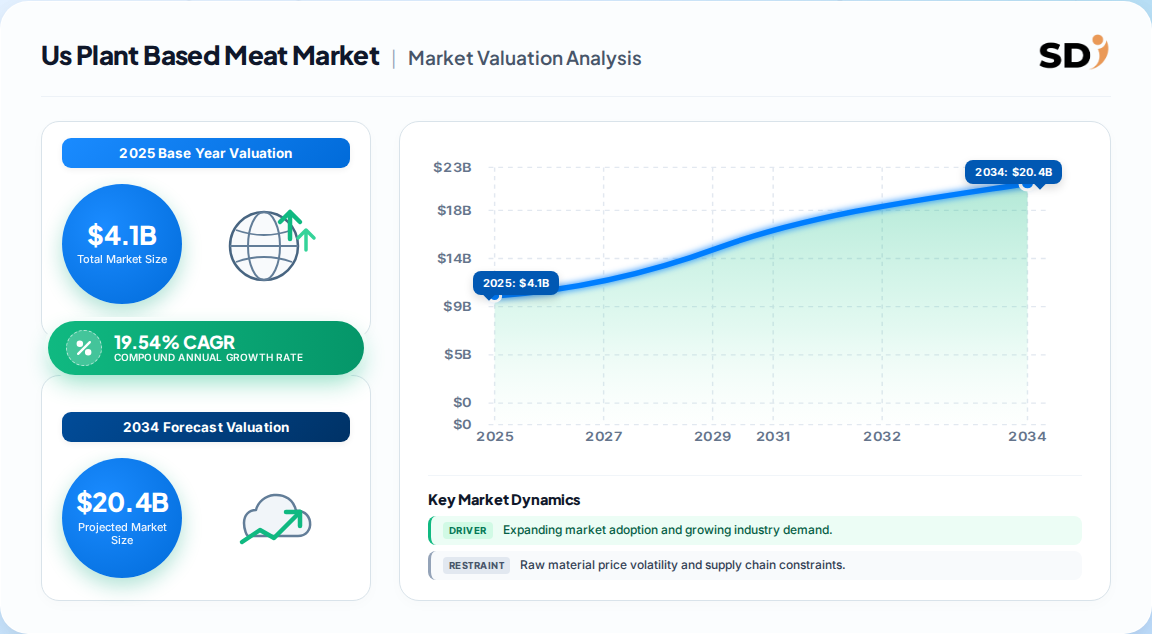
| Year | Market Size |
|---|---|
| 2025 | 4.100 B |
| 2026 | 4.900 B |
| 2027 | 5.860 B |
| 2028 | 7.000 B |
| 2029 | 8.370 B |
| 2030 | 10.01 B |
| 2031 | 11.96 B |

The U.S. plant-based meat market covers plant-protein meat analogues — burgers, sausages, nuggets, grounds and meatballs — made from soy, pea, wheat and mycoprotein and sold through retail and foodservice. It is the most commercially developed analogue category globally, now defined by retention and pricing discipline rather than launch velocity.
This analysis covers the United States market for plant-based meat analogues by product type, protein source, meat type, format, distribution channel and region, with historical data from 2020 and forecasts through 2034. This analysis does not cover plant-based dairy, plant-based seafood as a standalone category, conventional meat, or protein ingredient markets sold outside finished analogue products.
The U.S. plant-based meat market size was estimated at 3.21 Billion in 2024, rising to 4.1 Billion in 2025, with published 2034 forecasts as high as 21.5 Billion. Estimates diverge widely because of scope, channel and pricing treatment, so buyers should reconcile definitions before adopting any single figure.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 4.1 Billion | 2025 | 2034 | 19.54% | Retail + foodservice, all plant-based meat analogues | One published estimate |
| 3.21 Billion | 2024 | 2030 | 18.1% | Retail-led, excl. some foodservice | A competing analysis |
| 2.25 Billion | 2023 | 2029 | 15.17% | Retail-focused analogues | A competing analysis |
| 3.25 Billion | 2025 | 2033 | 10.8% | Broad analogue incl. mycoprotein | A competing analysis |
| 1.239 Billion | 2025 | 2032 | 2.15% | Measured retail pounds, manufacturer net revenue | A competing analysis |
The upper-bound estimates embed aggressive price-parity assumptions and broad category inclusion. Our analysis suggests the 15–19% CAGR band is defensible for a revenue-based category definition, while the 2.15% figure is a measured-pound, manufacturer-revenue view reflecting the 2022–2025 correction. Buyers should adopt the higher band for strategy and the lower band for near-term cash-flow planning.
The category segments across product type, protein source, meat type, storage format, distribution channel and end user. Product and source segmentation matter most commercially, because burger patties and soy protein anchor volume while pea protein and chicken analogues drive incremental growth.
| Parent segment | Children |
|---|---|
| Product type | Burger patties, sausages, nuggets and strips, ground meat, meatballs, others |
| Protein source | Soy, pea, wheat, mycoprotein, blended and emerging proteins |
| Meat type | Chicken, beef, pork, fish, others |
| Storage format | Frozen, refrigerated, shelf-stable |
| Distribution channel | Supermarkets and hypermarkets, convenience and specialty stores, online retail, restaurant and catering |
| End user | Households, restaurants and QSRs, institutional buyers |
Frozen formats hold roughly 69% of measured retail sales, reflecting longer shelf life and retailer assortment economics. Pea protein is outpacing soy on premium positioning, while soy retains cost-driven volume.
The West leads U.S. plant-based meat sales, followed by the South, Northeast and Midwest. Concentration tracks metropolitan consumer density, food innovation clusters and grocery distribution strength rather than population alone.
| Region | Market Share (%) |
|---|---|
| West | 0.29% |
| Northeast | 0.24% |
| South | 0.26% |
| Midwest | 0.21% |
| Parent | Children |
|---|---|
| United States | Northeast, Midwest, South, West |
Regional share (consensus estimate): West 29%, South 26%, Northeast 24%, Midwest 21%. Our analysis suggests the West's lead is narrowing as foodservice launches scale in the South, where QSR partnerships and institutional menus are expanding faster than retail shelf resets.
Health, sustainability and animal-welfare concerns are the primary growth drivers, reinforced by flexitarian adoption and clean-label reformulation. Premium pricing versus conventional meat and ingredient-perception skepticism are the principal restraints, with retail contraction since 2022 amplifying both.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Health and cholesterol awareness | Driver | High | Lower-saturated-fat positioning drives trial |
| Sustainability and carbon footprint | Driver | High | Livestock ~14.5% of global GHG emissions |
| Flexitarian mainstreaming | Driver | Medium | Supplementary protein positioning widens base |
| Clean-label reformulation | Driver | Medium | Simpler ingredient lists rebuild lapsed trust |
| Premium pricing vs. meat | Restraint | High | Price gap limits middle-income penetration |
| Processing and sodium skepticism | Restraint | Medium | IFIC surveys show additive aversion |
| Brand exits and shelf loss | Restraint | Medium | Reduces availability and category visibility |
The balance favors moderate recovery rather than a return to 2020–21 growth. Household retention — not acquisition — is now the binding constraint, and price parity is the single largest lever to close it.
Beyond Meat and Impossible Foods lead branded share, with MorningStar Farms, Gardein and Lightlife Foods anchoring frozen and mainstream retail. Differentiation rests on taste replication, foodservice partnerships and clean-label credentials.
| Company | Positioning | Portfolio focus | Strategic moat |
|---|---|---|---|
| Beyond Meat | Branded pioneer | Burgers, sausages, chicken | QSR partnerships, brand recall |
| Impossible Foods | Premium innovation | Burgers, grounds, chicken | Heme flavor technology, foodservice |
| MorningStar Farms | Mainstream frozen | Burgers, nuggets, veggie protein | Retail scale, household familiarity |
| Gardein | Frozen convenience | Chick'n, meatballs, grounds | Frozen distribution depth |
| Lightlife Foods | Clean-label value | Sausages, grounds, deli | Simpler ingredient positioning |
Private label is the structural threat. Our analysis suggests retailer brands will capture disproportionate share as price-sensitive flexitarians trade down, compressing branded margins unless innovation justifies a premium.
Procurement decisions hinge on four criteria: protein density per dollar, ingredient transparency, cold-chain reliability and menu or shelf velocity. Refrigerated SKUs carry higher waste risk and fell 12.1% in measured retail, making frozen formats the safer base load.
Switching costs are low for retail buyers but high for foodservice operators, where menu engineering, staff training and co-marketing create lock-in. Regulatory exposure centers on labeling and nutrition-claim compliance, with scrutiny intensifying on processed-food perception. Buyers should contract on reformulation timelines and require lifecycle analysis where sustainability claims are made.
The balance of evidence favors a moderate-recovery thesis, not a return to 2020–21 growth. The 15–19% CAGR band reflects revenue-based optimism, but household penetration near 24% and three consecutive years of retail contraction since the 2022 peak imply that volume growth must be earned through retention. The strongest counter-argument is that price-parity breakthroughs and non-commercial foodservice launches could push performance toward the bull case.
Our analysis suggests margin recovery depends on premiumization without reopening the price gap versus animal meat — a narrow corridor that rewards formulation efficiency over marketing spend. The frozen channel's ~69% share gives retailers structural bargaining power, and private-label expansion is the most probable source of downside.
Evidence that would change this conclusion: sustained volume growth above 5% annually, a durable narrowing of the price gap below 15%, or a major national foodservice launch that lifts household frequency. Conversely, further branded exits or renewed refrigerated decline would validate the low-growth case.
This assessment applied a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material suppliers, specialized analogue producers, contract formulators, cold-chain distributors and foodservice operators. Decision-maker designations included VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring formulation and procurement realities were captured alongside demand signals.
Secondary validation drew on UN Comtrade bilateral trade records, OECD-FAO Agricultural Outlook commodity baselines, USDA consumption data, SEC 10-K filings and investor presentations, patent databases, and recognized non-profit technical standards bodies. No third-party market-research publisher data was used as a primary benchmark.
Market sizing combined top-down macroeconomic and segment allocation with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Retail scanner velocity and foodservice pound sales were reconciled to produce a single triangulated base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Trade flow analysis and regional consumption mapping | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 19.54% from 2020-2034 |
| Segmentation |
|
The U.S. plant-based meat market was valued at 4.1 Billion in 2025, with published forecasts reaching 21.5 Billion by 2034. Estimates vary widely by scope and channel treatment.
Consensus forecasts cluster between 15% and 19.5% CAGR through 2034. Measured-pound analyses suggest a slower 2–11% band reflecting the post-2022 retail correction.
Burger patties lead product share, soy protein leads volume and plant-based chicken leads meat type. Frozen formats account for roughly 69% of measured retail sales.
Beyond Meat, Impossible Foods, MorningStar Farms, Gardein and Lightlife Foods lead the category, competing on taste replication, clean-label credentials and foodservice partnerships.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This assessment applied a 70/30 primary-to-secondary research split. In-depth interviews were conducted with raw material suppliers, specialized analogue producers, contract formulators, cold-chain distributors and foodservice operators. Decision-maker designations included VP of Sourcing, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring formulation and procurement realities were captured alongside demand signals.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Formulation Directors | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Protein Suppliers | 40% |
| Specialized Analogue Producers | 30% |
| Distributors & Cold-Chain Operators | 20% |
| Foodservice & Retail Buyers | 10% |
Secondary validation drew on UN Comtrade bilateral trade records, OECD-FAO Agricultural Outlook commodity baselines, USDA consumption data, SEC 10-K filings and investor presentations, patent databases, and recognized non-profit technical standards bodies. No third-party market-research publisher data was used as a primary benchmark.
Market sizing combined top-down macroeconomic and segment allocation with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Retail scanner velocity and foodservice pound sales were reconciled to produce a single triangulated base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production and revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression and demand elasticity | High |
| Regional Distribution | Regional share breakdown | Trade flow analysis and regional consumption mapping | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping and commercial filings | High |