 Protein Supplements Market
 Size, CAGR & Outlook 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 219

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Protein Supplements Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 29.80 B |
| 2026 | 31.90 B |
| 2027 | 35.20 B |
| 2028 | 38.80 B |
| 2029 | 42.80 B |
| 2030 | 47.20 B |
| 2031 | 52.10 B |

The protein supplements market covers concentrated protein products — powders, bars, ready-to-drink shakes, gummies and capsules — sold to consumers for muscle maintenance, recovery, weight management and general wellness. It spans animal-derived inputs (whey, casein, collagen, egg) and plant-based sources (pea, soy, mung bean, hemp), distributed through grocery, specialist retail and online channels. Scope here is finished consumer products, not bulk ingredients.
This analysis covers finished consumer protein supplements across all major formats, sources, applications and distribution channels, worldwide. It includes sports nutrition, functional food and clinical/healthy-aging use cases. It excludes bulk protein ingredients sold to food manufacturers, infant formula, pet nutrition, and pure amino-acid supplements sold outside protein-positioned products. This analysis does not cover the standalone sports nutrition or weight-management markets except where they intersect protein supplements.
Estimates cluster around USD 28–32 billion for 2025–2026, but horizons and definitions diverge sharply — one analysis projects USD 63.2 billion by 2033, another USD 44.0 billion by 2031. The gap is largely a function of scope: narrower reports exclude clinical and functional-food applications, which materially changes the growth rate.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| USD 29.8B → 63.2B | 2025 | 2033 | 10.3% | Broad: supplements + functional food + clinical | One published estimate |
| USD 28.1B → 44.0B | 2025 | 2031 | 7.74% | Form-led; narrower application set | A competing analysis |
| USD 19.0B → 33.4B | 2025 | 2035 | 5.8% | Protein powder only, not full supplements | A third-party forecast |
Our analysis suggests the broad 10.3% CAGR is the most defensible for a full-category view, because clinical and functional-food applications are now the fastest-growing demand pools and a powder-only lens structurally understates them. The 5.8% powder figure is internally consistent but describes a different, more mature product market.
Segmentation splits along four axes — source, product form, application and channel — with each parent defining a distinct competitive battleground and margin profile.
| Parent | Children |
|---|---|
| By Source | Animal-based (whey, casein, collagen, egg), Plant-based (pea, soy, mung bean, hemp, rice) |
| By Product | Protein powders, protein bars, RTD shakes, gummies, capsules |
| By Application | Sports nutrition, functional food, clinical & healthy aging |
| By Distribution | Supermarkets & hypermarkets, online, health & wellness stores, DTC |
Animal-based sources retain the majority of value, but plant-based and collagen are the growth engines. Powders anchor volume; RTDs and gummies capture convenience-led demand. Online is now the largest single channel, which compresses the shelf-space moat that historically protected incumbent brands.
North America leads with roughly 41% of global revenue in 2025, but Asia Pacific is the fastest-growing region and the decisive battleground for volume over the forecast horizon. Europe holds a mature, regulation-heavy second position.
| Region | Market Share (%) |
|---|---|
| North America | 0.41% |
| Europe | 0.23% |
| Asia-Pacific | 0.25% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
| Region | 2025 Share | Growth Profile |
|---|---|---|
| North America | ~41% | Mature, premium-led |
| Europe | ~23% | Regulated, steady |
| Asia Pacific | ~25% | Fastest CAGR |
| Latin America | ~6% | Emerging, price-sensitive |
| Middle East & Africa | ~5% | Early-stage |
This divergence implies that North American value growth will come from premiumisation and clinical positioning, while Asia Pacific rewards volume and affordability engineering. A single global pricing strategy will fail in one of the two.
Growth is driven by fitness participation, clinical and healthy-aging demand, and plant-based adoption; restraint comes from affordability gaps in emerging markets and label-claim regulation.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Fitness & gym culture | Driver | Strong | Widens recurring-consumption base |
| Clinical / sarcopenia nutrition | Driver | Moderate–strong | Shifts product to protocol-driven use |
| Plant-based adoption | Driver | Strong | Expands formulation choice and reach |
| Social media & influencers | Driver | Moderate | Accelerates discovery, especially Gen Z |
| Price premium in emerging markets | Restraint | Moderate | Caps volume in highest-growth regions |
| Label-claim regulation | Restraint | Moderate | Raises compliance cost, slows launches |
The balance favours growth, but the mix is shifting. Sports-driven demand is mature and increasingly commoditised; clinical and convenience demand carries pricing power but demands substantiation, palatability and compliance. The implication for buyers is that the defensible margin pool is migrating toward evidence-backed, format-diverse portfolios.
The category is moderately concentrated: leading players hold meaningful but not dominant share, and no single firm controls the category.
| Company | Positioning | Competitive moat |
|---|---|---|
| Glanbia plc | Sports & ingredient-integrated | Sourcing scale, brand equity |
| Abbott Laboratories | Clinical & adult nutrition | Medical credibility, channel access |
| Herbalife Nutrition | DTC & community selling | Distributor network |
| GNC Holdings | Specialist retail & own brand | Store footprint, category authority |
| Amway Corporation | DTC wellness | Loyalty and repeat purchase |
Our analysis suggests the strongest moats are no longer brand alone but vertical ingredient integration and clinical substantiation. Firms with a common ingredient platform across retail, clinical and food-fortification formats can spread sourcing and quality costs — a structural advantage that narrow specialty-retail brands lack.
Selection criteria have bifurcated. In mass wellness channels, flavour, convenience and price per serving dominate; in clinical and specialist channels, digestibility, protein density, documentation and claim substantiation are decisive. Buyers who apply one scorecard across both will misprice risk. Procurement risk concentrates in raw-material volatility — whey supply and pea-protein capacity are the two swing inputs — and in allergen management for plant blends. Switching costs are low for consumers but high for operators, because reformulation triggers re-testing, relabelling and regulatory re-filing. Compliance is the sharpest constraint: label-claim restrictions in the EU and India, and tightening quality scrutiny in India, mean unsubstantiated premium positioning is a live liability. A practical rule: qualify suppliers on documentation depth first, taste performance second, price third.
The balance of evidence favours the broad, 10.3% CAGR view — but with a critical caveat that most published summaries miss. The growth is not evenly distributed across the category; it is concentrated in clinical/healthy-aging, plant-based and convenience formats, while core sports powders drift toward commoditisation. The strongest counter-argument is that affordability barriers in Asia Pacific and Latin America could cap the volume upside that the high-CAGR case assumes; if emerging-market price sensitivity proves binding, the realistic blended CAGR sits nearer 8%.
We judge that risk as real but secondary, because the premium pools are in developed markets where willingness to pay is documented. The second-order effect that matters most: as clinical positioning grows, the category's competitive axis shifts from marketing to substantiation — which favours ingredient-integrated firms and penalises marketing-only brands. Operators should expect margin divergence, not uniform growth.
Actionable strategy:
What would change our conclusion: sustained whey or pea-protein price shocks, or a major regulatory clampdown on protein claims in the EU or India, would push the blended CAGR toward the 7–8% range and shift value decisively toward vertically integrated players.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.3% from 2020-2034 |
| Segmentation |
|
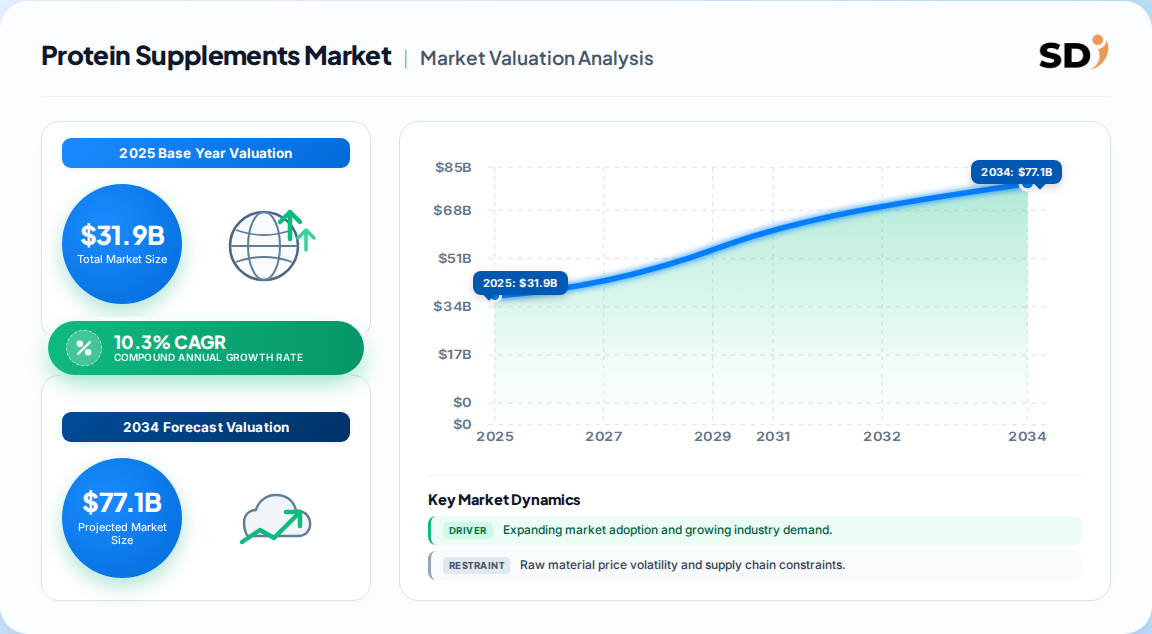
The global protein supplements market is estimated at USD 31.9 billion in 2026, projected to reach USD 63.2 billion by 2033 at a 10.3% CAGR. Broader clinical and functional-food scope supports the higher end of published estimates.
North America leads with roughly 41% of global revenue in 2025, driven by premiumisation and clinical nutrition. Asia Pacific is the fastest-growing region, benefiting from rising fitness participation and expanding middle-class demand.
Plant-based protein is the fastest-growing source segment at around 10% CAGR, while ready-to-drink formats grow fastest by form at roughly 9% CAGR. Clinical and healthy-aging applications carry the highest margin potential.
Leading players include Glanbia plc, Abbott Laboratories, Herbalife Nutrition, GNC Holdings and Amway Corporation. The category is moderately concentrated, with the top five holding roughly 37% of value in protein powder.
Price premiums constrain adoption in emerging markets such as India, Southeast Asia and Latin America, while label-claim restrictions in the EU and India raise compliance costs and slow premium product launches.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research programme applies a 70/30 primary-to-secondary split, prioritising direct industry validation. In-depth interviews were conducted across the value chain, including raw material suppliers, specialised supplement producers, contract formulators and blenders, and global distributors. Decision-makers interviewed included VP-level sourcing leads, Heads of R&D, Technical Directors and Commercial Operations Leads, ensuring both supply-side and demand-side perspectives inform every estimate.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Formulation Heads | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Ingredient Suppliers | 40% |
| Specialised Supplement Producers | 35% |
| Contract Formulators & Blenders | 15% |
| Global Distributors & Retailers | 10% |
Findings are cross-checked against official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations, patent databases, and recognised non-profit technical standards and industry associations. This triangulation anchors our sizing in verifiable trade and corporate disclosure rather than single-source projections.
We run simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing and end-use consumption) models. Divergence between the two is reconciled through weighted averaging, with primary interview data used to resolve material gaps.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |