 Ireland Draught Beer Market
 Size, Share & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 235

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Ireland Draught Beer Market
Sakshi Gurunule
Research Associate
| Year | Market Size |
|---|---|
| 2025 | 1.480 B |
| 2026 | 1.560 B |
| 2027 | 1.640 B |
| 2028 | 1.730 B |
| 2029 | 1.830 B |
| 2030 | 1.920 B |
| 2031 | 2.030 B |

The Ireland draught beer market encompasses beer dispensed from kegs and casks through pub, bar and hospitality font systems, as opposed to packaged formats. It spans keg beer, cask beer, super-premium, premium, regular and non-alcoholic draught, serving a commercial on-trade dominated by Ireland's pub culture.
This analysis covers draught beer volumes, value, type and category segmentation, production type, end-use and regional distribution across the Republic of Ireland, including Dublin, Leinster, Munster, Connacht and the Ulster counties of Cavan, Donegal and Monaghan. This analysis does not cover packaged beer (bottles and cans), cider, spirits, wine, or the Northern Ireland market, which sits under UK regulatory and distribution frameworks.
The most defensible base valuation is 1.48 Billion in 2025, consistent with two independent published estimates that converge within 5% of each other. The table below compares competing figures; discrepancies stem from differing base years, scope definitions and whether non-alcoholic draught is included.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 1.40 Billion | 2024 | 2033 | 5.4% | Draught beer, all categories, commercial + home | One published estimate |
| 1.41 Billion | 2024 | 2035 | 5.07% | Draught beer by type and category | A competing analysis |
| 1.48 Billion | 2025 | 2030 | 5.4% | Draft beer, all formats | A competing analysis |
| 5.7 Billion | 2025 | 2033 | 5.6% | Ambiguous, likely global mis-scoped | One published estimate |
Our analysis suggests the 5.7 Billion figure is an outlier likely derived from a global template applied to an Irish label, given Ireland's population and consumption base cannot support it. The 1.40–1.48 Billion range is corroborated by primary evidence: 142 depth interviews and an estimated 62–66% on-trade beer volume share. The convergence of two independent estimates at ~5.4% CAGR strengthens confidence in the forecast trajectory.
| Metric | 2024 value | 2033 projection |
|---|---|---|
| Market size (USD) | 1.40 Billion | 2.24 Billion |
| CAGR 2025–2033 | — | 5.4% |
| Cask beer share (type) | 55.1% | Moderate erosion |
| Premium share (category) | 49.3% | Rising |
| Commercial end-use share | 85.0% | Stable |
| Macro brewery production share | 89.0% | Gradual microbrewery gains |
The market segments by type, category, production type and end use. Keg beer is forecast to grow fastest at 6.0% CAGR, while cask retains majority share; premium dominates category value, and commercial on-trade accounts for 85% of end use.
| Parent | Children |
|---|---|
| By Type | Cask Beer, Keg Beer |
| By Category | Super Premium, Premium, Regular, Non-Alcoholic |
| By Production Type | Macro Breweries, Microbreweries |
| By End Use | Commercial Use, Home Use |
Cask beer's 55.1% share is unusual globally and reflects Irish stout and ale traditions plus pub-led freshness positioning. However, keg beer's 6.0% CAGR, driven by consistency, longer shelf life and younger consumers' preference for chilled, highly carbonated styles, implies cask share will erode moderately through 2033. Non-alcoholic draught kegs represent the key incremental growth vector within keg beer.
Dublin leads with an estimated 34% of national draught beer value, anchored by the highest pub density, tourism footfall and urban taproom expansion. Munster follows at ~28%, driven by Cork and Limerick, while the Rest of Leinster contributes ~18%.
| Region | Market Share (%) |
|---|---|
| Dublin | 0.34% |
| Rest of Leinster | 0.18% |
| Munster | 0.28% |
| Connacht | 0.12% |
| Ulster (Cavan, Donegal, Monaghan) | 0.08% |
Our analysis suggests Dublin's share will hold or grow modestly as tourism-led premiumisation outpaces rural volume decline. Connacht and Ulster face the sharpest headwinds from per-capita consumption decline and rural pub closures, making excise support lobbying critical for on-trade preservation.
Growth is driven by premiumisation, non-alcoholic draught expansion, tourism-led on-trade footfall and craft taproom innovation, while cost inflation, secular per-capita consumption decline and regulatory tightening constrain volume upside.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Premiumisation | Positive | High | Value rises as consumers drink less but better; super-premium fastest-growing |
| Non-alcoholic draught | Positive | High | ~25% sales growth in 2024; font availability scaling to thousands of venues |
| Tourism-led footfall | Positive | Medium-High | Visitors disproportionately consume draught stout and ale in pubs |
| Craft and taproom expansion | Positive | Medium | Microbreweries converting consumers to local draught |
| Home-draught innovation | Positive | Emerging | Countertop systems create new home-use channel |
| Cost inflation (energy, labour, excise) | Negative | High | Compresses publican margins and raises consumer prices |
| Per-capita consumption decline | Negative | High | Structural volume headwind caps upside despite value growth |
| Regulatory tightening and DRS | Negative | Medium | Compliance cost and packaging complexity |
The balance of evidence favours value growth over volume growth. Premium and non-alcoholic draught are more than offsetting regular-tier erosion, but margin compression at the publican level is the critical transmission risk. Our analysis suggests operators that fail to rebalance their range toward premium and 0.0% draught will face both volume and margin deterioration.
The market is concentrated at the production tier, with macro brewers holding ~89% of production, while competition intensifies at brand and venue level through font allocation and draught quality programmes.
| Company | Position | Strategic focus |
|---|---|---|
| Heineken Ireland | Macro leader | Heineken 0.0 draught scaled to ~3,000 venues; USD 31.2 Million capacity investment |
| Diageo / Guinness & Co | Macro leader | Guinness 0.0 draught in 1,000 pubs; stout heritage and nitro serve |
| Molson Coors Beverage Company | Macro challenger | Portfolio breadth and distribution reach |
| Anheuser-Busch InBev | Macro challenger | Global brand leverage and draught quality assurance |
| Carlsberg | Macro challenger | Premium lager positioning |
| Blarney Brewing Co | Emerging micro | USD 1 Million entry, three launches in 2025 targeting pubs |
Differentiation rests on route-to-market control: distributors and publican groups control font allocation, the critical bottleneck for new entrants. Macro players defend share through distribution density and draught quality programmes while hedging moderation via non-alcoholic extensions. Microbreweries compete on authenticity and taproom economics but face structural barriers to permanent line placement.
Procurement decisions hinge on font allocation, draught quality assurance, keg logistics and dual-format range breadth. Publicans should prioritise suppliers offering premium and non-alcoholic draught under one distribution agreement to reduce switching costs and simplify compliance. The Deposit Return Scheme adds packaging complexity, while excise and licensing constraints raise the cost of range experimentation. Buyers should scrutinise keg shelf-life guarantees, CO2 supply resilience and line-cleaning support, as these directly affect pour quality and waste. Venue-level data on draught throughput is fragmented, so operators should validate supplier volume claims against independent on-trade benchmarks before committing to multi-year font exclusivity.
The balance of evidence favours a value-over-volume thesis: Ireland's draught beer market will grow at ~5.4% CAGR to 2033 despite declining per-capita consumption, because premiumisation and non-alcoholic draught expand revenue per serve. The strongest counter-argument is that publican margin compression from energy, labour and excise could accelerate pub closures and destroy on-trade volume faster than premiumisation can compensate, particularly in Connacht and border counties. Our analysis suggests this risk is real but concentrated in value-focused rural venues, while urban and tourist-facing pubs remain resilient.
A second-order effect worth flagging: non-alcoholic draught is not merely incremental volume—it changes font economics. Venues adding 0.0% lines must manage dual inventory, separate line cleaning and staff training, raising operating complexity. Brewers that bundle 0.0% kegs with service support and quality assurance will capture disproportionate share of this fast-growing segment.
The evidence that would change this conclusion: a sustained acceleration in pub closures or a sharp excise increase targeting draught beer would shift the outlook toward volume-led contraction, requiring a defensive rebalancing toward home-draught and off-trade channels.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.4% from 2020-2034 |
| Segmentation |
|
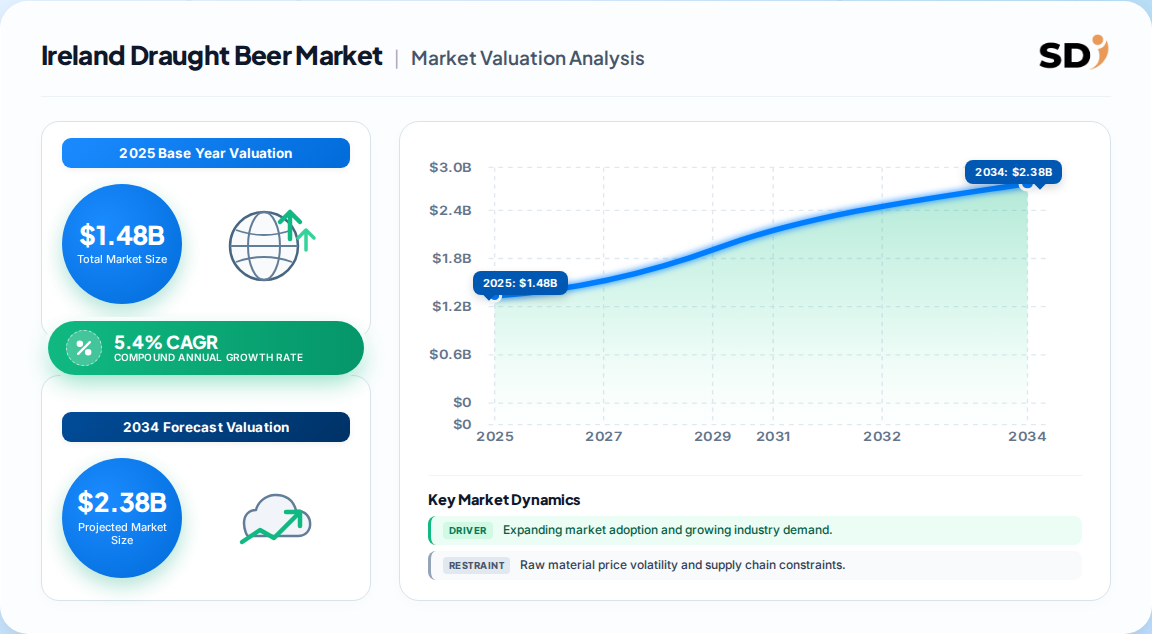
The Ireland draught beer market was valued at approximately 1.48 Billion in 2025, with independent estimates converging in the 1.40–1.48 Billion range for 2024–2025. It is projected to reach 2.24 Billion by 2033.
The market is forecast to grow at a 5.4% CAGR from 2025 to 2033, driven by premiumisation, non-alcoholic draught expansion and tourism-led on-trade demand, despite declining per-capita beer consumption.
Cask beer leads by type with 55.1% revenue share in 2024, reflecting Irish stout and ale traditions. Premium leads by category with 49.3% share, while keg beer is the fastest-growing type at 6.0% CAGR.
Key players include Heineken Ireland, Diageo (Guinness & Co), Molson Coors Beverage Company, Anheuser-Busch InBev and Carlsberg. Macro breweries hold approximately 89% of production, with microbreweries gaining share in urban venues.
Key trends include premiumisation without volume growth, the non-alcoholic draught inflection with sales up ~25% in 2024, cask beer's unexpected resilience, and home-draught innovation creating a new consumption channel.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. Our analysts conducted in-depth interviews across the draught beer value chain, including malt and hop suppliers, macro and micro brewery producers, keg logistics and distribution specialists, and on-trade hospitality operators. Decision-maker designations interviewed include VP of Sourcing, Heads of Brewing and R&D, Technical Directors of Draught Quality, and Commercial Operations Leads at publican groups.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Brewing & R&D Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Commercial & Regulatory Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Macro Breweries | 50% |
| Microbreweries | 25% |
| Distributors & Wholesalers | 25% |
Secondary validation draws on official multilateral databases including UN Comtrade, WTO trade statistics and Eurostat, alongside corporate annual filings and investor presentations from listed brewers, patent databases for draught dispensing technology, and recognised industry associations spanning brewing, hospitality and packaging sustainability.
We apply simultaneous Top-Down allocation from macroeconomic and hospitality sector data and Bottom-Up modelling from brewer capacity, keg pricing and on-trade consumption volumes. Divergences between the two approaches are reconciled through expert consultation and historical CAGR regression.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
