 Taiwan Nutraceuticals Market
 Size, Share & Forecast 2026
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 199

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Taiwan Nutraceuticals Market
Sakshi Gurunule
Research Associate

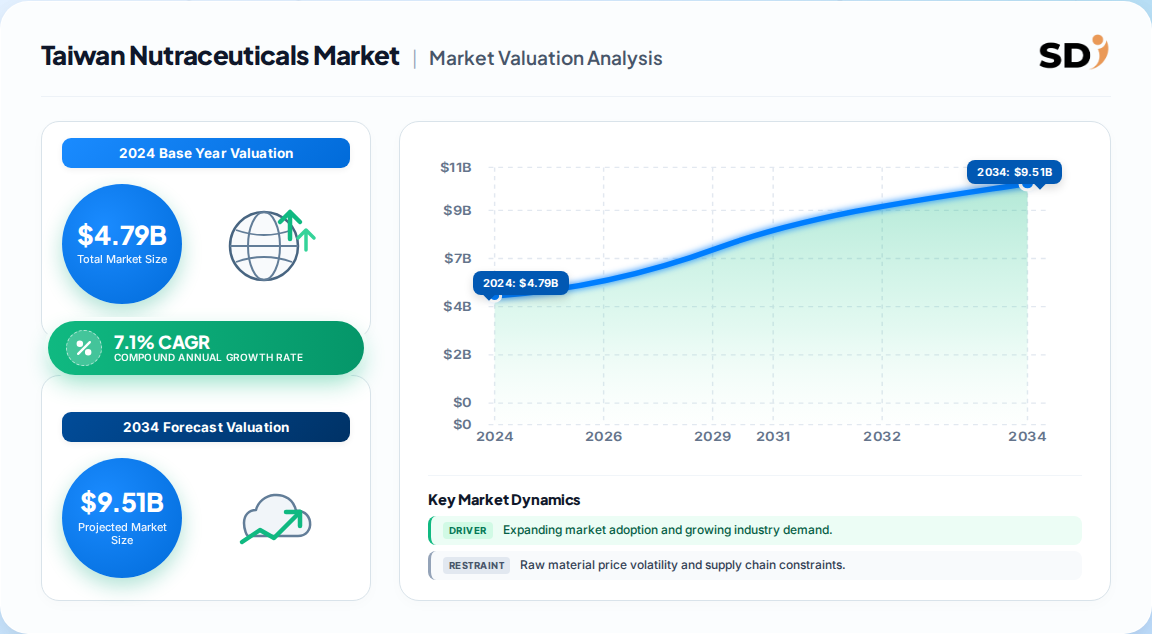
| Year | Market Size |
|---|---|
| 2024 | 4.790 B |
| 2025 | 5.130 B |
| 2026 | 5.490 B |
| 2027 | 5.880 B |
| 2028 | 6.300 B |
| 2029 | 6.750 B |
| 2030 | 7.230 B |

The Taiwan nutraceuticals market comprises products derived from food sources that deliver health benefits beyond basic nutrition—including dietary supplements, functional foods, functional beverages, and infant formula—sold through offline and online channels to a population that increasingly prioritizes preventive healthcare over reactive treatment.
This report covers the Taiwan nutraceuticals market across four product segments—dietary supplements, functional food, functional beverages, and infant formula—analyzed by application and distribution channel. It includes market sizing, segmentation, competitive landscape, and forward forecasts through 2033. This analysis does not cover pharmaceutical drugs, medical foods requiring clinical supervision, conventional unfortified food and beverage categories, or veterinary nutraceuticals.
One published estimate sizes the Taiwan nutraceuticals market at USD 4.79 billion in 2024, projecting USD 8.87 billion by 2033 at a 7.1% CAGR. A competing analysis arrives at a higher base of USD 5.15 billion in 2025 and a 2035 horizon of USD 10.32 billion at 7.2% CAGR. A U.S. trade source reported sector revenue of USD 5.3 billion in 2021, reflecting a broader dietary-supplement definition.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 4.79 Billion | 2024 | 2033 | 7.1% | Nutraceuticals: supplements, functional food, beverages, infant formula | One published estimate |
| USD 5.15 Billion | 2025 | 2035 | 7.2% | Nutraceuticals incl. herbal products; broader application coverage | A competing analysis |
| USD 5.3 Billion | 2021 | — | — | Dietary supplements only; revenue-based | U.S. trade source (ITA) |
Our analysis suggests the USD 4.79 billion (2024) figure is the most defensible because it aligns with a clearly bounded product definition and a bottom-up segmentation that reconciles with Grape King Bio's reported NT$11 billion revenue and 32% probiotic share. The USD 5.15 billion figure likely reflects a broader herbal-products inclusion and a one-year-forward base. The divergence implies buyers should normalize vendor proposals to a common scope before comparing forecasts; a 7–8% differential in base size materially changes five-year revenue projections.
Segmentation follows three axes—product, application, and distribution channel—each revealing distinct growth velocities. Functional beverages dominate and accelerate simultaneously, an unusual combination that signals structural consumer preference for convenient formats over pills.
| Parent Segment | Children | 2024 Position / Insight |
|---|---|---|
| Product | Dietary supplements, Functional food, Functional beverages, Infant formula | Functional beverages 47.9% share; fastest at 7.8% CAGR |
| Application | Weight management & satiety, Men's health, Women's health, Bone & joint health, Cognitive health, Digestive & gut health, Immune system, Heart health, Eye health, Nutricosmetics, Sports nutrition, Healthy ageing, Children's health, Personalised nutrition | Weight management largest; men's health fastest CAGR |
| Distribution Channel | Offline (pharmacies & drug stores, supermarkets & hypermarkets, convenience stores), Online (marketplaces, DTC subscription) | Offline dominant; online fastest-growing |
Northern Taiwan leads the Taiwan nutraceuticals market, concentrating the highest density of pharmacies, convenience stores, urban professional consumers, and corporate headquarters. Central and Southern Taiwan follow as secondary demand clusters, while Eastern Taiwan and the Outlying Islands remain thin, service-constrained markets.
| Region | Market Share (%) |
|---|---|
| Northern Taiwan | 0.46% |
| Central Taiwan | 0.24% |
| Southern Taiwan | 0.22% |
| Eastern Taiwan | 0.05% |
| Outlying Islands | 0.03% |
| Parent | Children |
|---|---|
| Taiwan | Northern Taiwan, Central Taiwan, Southern Taiwan, Eastern Taiwan, Outlying Islands |
Our analysis suggests that regional share should be treated as a proxy for retail infrastructure density rather than population alone; Northern Taiwan's lead is disproportionately driven by convenience-store chilled shelf access, which is the single strongest predictor of functional-beverage penetration.
Growth is anchored by a super-aged society—over 20% of the population was 65+ by 2025—and record-low fertility that reallocates household spend toward adult and senior health. Restraints are structural, not cyclical: infant formula is volume-capped, and import tariffs of 30% on tablet/capsule supplements raise landed costs.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Super-ageing population (20%+ aged 65+) | Driver | High | Demand for bone, joint, cognitive, cardiovascular support |
| Record-low births (134,856 in 2024) | Mixed | High | Caps infant formula; reallocates spend to adult health |
| Obesity burden (~50% of adults) | Driver | High | Weight management & satiety formulations |
| Preventive-health mindset shift | Driver | Medium-High | Proactive daily supplementation, immunity, wellness |
| 30% tariff on tablet/capsule supplements | Restraint | High | Raises landed cost for imported brands |
| Intense imported-brand competition | Restraint | Medium | Margin pressure in online and pharmacy channels |
The balance of evidence favors sustained 7%+ growth, but the composition of that growth is shifting decisively toward beverages and senior-health applications. The 30% tariff is the most under-appreciated restraint: it structurally disadvantages capsule imports relative to locally manufactured or beverage-format products, which our analysis suggests is a key reason functional beverages outgrow supplements.
Grape King Bio is the dominant domestic player, with record 2024 revenue exceeding USD 335 million, a 32% share in probiotics, and 59% in medicinal mushrooms. Standard Foods Group and Chambio anchor domestic food and supplement manufacturing, while Nestlé Health Science, Amway, and GSK plc represent global brands competing in premium and direct-selling channels.
| Company | Type | Notable Position |
|---|---|---|
| Grape King Bio Ltd. | Domestic manufacturer | Probiotics leader (32%), medicinal mushrooms (59%) |
| Standard Foods Group | Domestic food & nutrition | Broad functional food and supplement portfolio |
| Chambio Co., Ltd. | Domestic supplement maker | Established local formulations |
| Nestlé Health Science | Global | Premium clinical and specialized nutrition |
| Amway Products Co., Ltd. | Global direct selling | Relationship-led supplement sales |
| GSK plc | Global | Established OTC and supplement brands |
Differentiation hinges on fermentation and probiotics capability—a genuine domestic moat—and on channel trust. Grape King's share dominance in probiotics is not easily replicated; it reflects decades of strain IP and manufacturing scale. Imported brands compete on quality perception and brand equity but face tariff-driven cost disadvantages in capsule formats.
Selection criteria vary sharply by channel. For functional beverages, refrigerated availability and convenience-store chilled shelf space are mission-critical; without them, RTD formats cannot reach the impulse-frequency levels that drive category growth. For supplements, pharmacist or nutritionist endorsement is the credibility gate, particularly for premium and senior-health SKUs.
Procurement risk is concentrated in tariff exposure (30% on tablet/capsule forms) and in regulatory classification—the line between supplement and pharmaceutical claim is actively enforced, and Mandarin-language educational content is a de facto compliance requirement. Switching costs are moderate for commodity vitamins but high for branded probiotics and proprietary strains, where clinical substantiation and strain IP create lock-in. Buyers should audit supplier fermentation capability, strain documentation, and local registration status before committing to multi-year contracts.
The balance of evidence favors functional beverages and senior-health applications as the highest-conviction growth vectors through 2033. The strongest counter-argument is that beverage dominance reflects convenience rather than efficacy, and that a consumer shift toward clinically substantiated supplements could re-weight demand—but we view this as a second-order risk given Taiwan's entrenched convenience-store culture and pill fatigue.
Our analysis suggests the most defensible strategic position is a dual-track portfolio: beverage-format SKUs for reach and frequency, supplemented by premium, pharmacist-endorsed lines for margin and credibility. Pure-play capsule importers face the worst of both worlds—tariff exposure without the channel trust that domestic incumbents enjoy.
Actionable Strategy:
What would change our conclusion: a sustained reversal in birth rates, a tariff reduction on capsule imports, or regulatory tightening on functional-beverage health claims would each materially alter the growth composition.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 7.1% from 2020-2034 |
| Segmentation |
|
The market was estimated at USD 4.79 billion in 2024 and is projected to reach USD 8.87 billion by 2033, growing at a 7.1% CAGR. A competing analysis places the 2025 base at USD 5.15 billion.
Functional beverages lead with a 47.9% revenue share in 2024 and are also the fastest-growing segment at 7.8% CAGR, driven by convenience, pill fatigue, and ready-to-drink formats such as collagen.
Men's health is forecast to record the fastest CAGR from 2025 to 2033, driven by rising awareness of prostate health, low testosterone, hair and skin concerns, and micronutrient deficiencies.
Grape King Bio leads domestically with a 32% probiotic share and 59% medicinal mushroom share. Standard Foods Group, Chambio, Nestlé Health Science, Amway, and GSK plc are other prominent competitors.
Offline retail dominates, supported by high pharmacy and convenience-store density. Online marketplaces and DTC subscriptions are the fastest-growing channel, especially for personalized nutrition and imported brands.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis rests on a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain, including raw material suppliers, specialized producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of both supply-side capability and demand-side strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 35% |
| Procurement & Sourcing Directors | 30% |
| Regulatory Affairs Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Ingredient Suppliers | 30% |
| Domestic Manufacturers & CDMOs | 35% |
| Global Brand Distributors | 20% |
| Retail & Pharmacy Chains | 15% |
We validated findings against official multilateral trade and standards databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized non-profit technical standards and industry associations. This triangulation anchors our estimates in verifiable public benchmarks rather than single-source projections.
We applied simultaneous Top-Down (macroeconomic and segment allocation) and Bottom-Up (manufacturer capacity, product pricing, and end-use consumption) modeling. Divergences between the two approaches were reconciled through expert interview evidence and historical trend regression, producing a triangulated base-year value and compound forecast through 2033.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |