 Hydrolyzed Wheat Protein Market
: 2026 Global Outlook
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 183

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Hydrolyzed Wheat Protein Market
Sakshi Gurunule
Research Associate

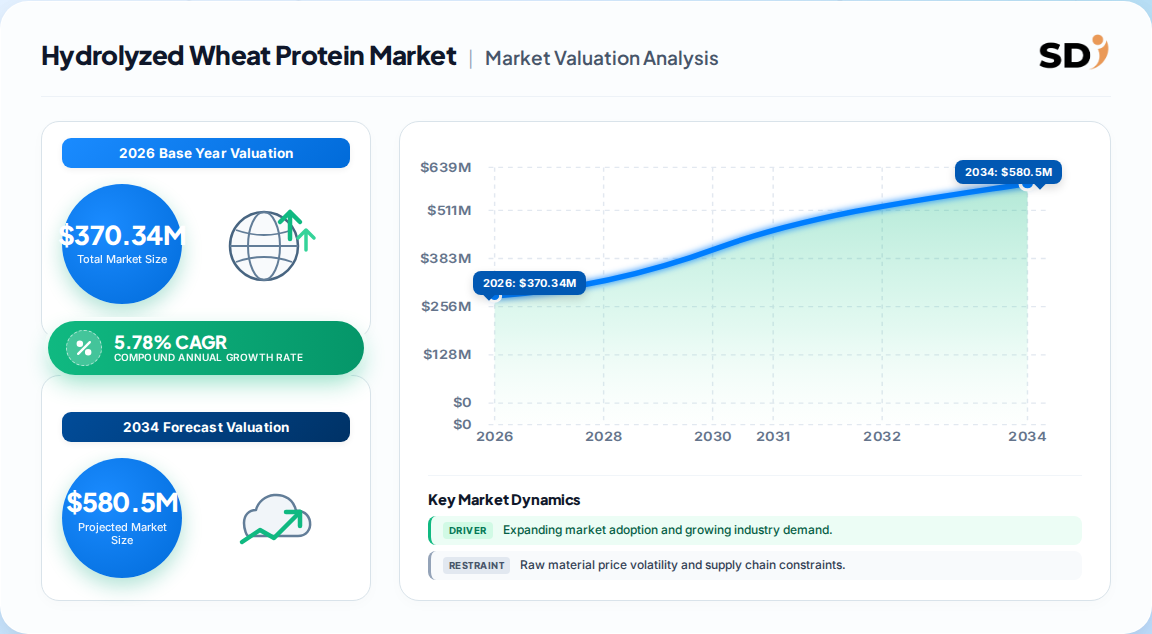
| Year | Market Size |
|---|---|
| 2025 | 350.0 M |
| 2026 | 370.0 M |
| 2027 | 392.0 M |
| 2028 | 414.0 M |
| 2029 | 438.0 M |
| 2030 | 464.0 M |
| 2031 | 490.0 M |

Hydrolyzed wheat protein is a plant-derived protein obtained by acidic, alkaline or enzymatic hydrolysis of wheat germ, yielding amino acids, peptides and proteins used as a conditioning, moisturizing and fortifying agent in cosmetics, and as a functional protein ingredient in food, beverages and pet nutrition.
The EU CosIng inventory classifies it under INCI name HYDROLYZED WHEAT PROTEIN, with functions listed as antistatic, hair conditioning and skin conditioning.
This analysis covers the global hydrolyzed wheat protein market across powder and liquid forms, conventional and organic sourcing, and the food and beverage, cosmetics and personal care, and animal feed and pet food application verticals. It includes value forecasts to 2031 and vendor positioning.
This analysis does not cover wheat gluten, wheat protein isolate or textured wheat protein as standalone categories, nor does it address adjacent plant-protein hydrolysates such as soy or pea protein hydrolysates except where directly comparative.
Reference estimates diverge sharply, and the gap is definitional rather than methodological. One published estimate frames the category at over 150 billion, while a competing analysis places it near 370 million in 2026 — a roughly 400-fold spread that signals scope confusion in the syndicated literature.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| Approximately 370 million | 2026 | 2031 | 5.78% | Hydrolyzed wheat protein only, form and application segmented | One published estimate |
| Approximately 158 billion | 2024 | 2030 | 7.5% | Appears to capture broader plant-protein or protein-ingredient value chain | A competing analysis |
| Approximately 1.22 billion (2022) rising to 1.68 billion | 2022 | 2032 | ~3.4% | Hydrolyzed wheat protein as a product sub-segment within wheat protein | Trade statistics aggregator |
The most defensible figure is the narrow 370 million estimate, because it aligns with the hydrolyzed sub-segment tracked inside broader wheat protein datasets. Our analysis suggests the multi-billion figure conflates downstream finished-product revenue with ingredient-level trade value, which would distort capacity planning if used directly.
Segmentation follows three primary axes — form, source and application — with form and application carrying the most commercial weight for buyers specifying formulations.
| Parent segment | Children |
|---|---|
| By Form | Powder, Liquid |
| By Source | Conventional Wheat, Organic Wheat |
| By Application | Food and Beverage, Animal Feed and Pet Food, Cosmetics and Personal Care |
Powder captured 77% of 2025 share, reflecting its stability, shelf life and ease of blending in bakery and supplements. Liquid hydrolysates are advancing at roughly 6% CAGR because they deliver superior bioavailability in hair and skin formulations. Conventional wheat holds 84% of volume, but organic is expanding at 8.55% CAGR.
Europe leads global consumption at roughly 34% of volume, underpinned by a mature food-processing base and stringent clean-label expectations; Asia-Pacific is the fastest-growing region at close to 6.7% CAGR.
| Region | Market Share (%) |
|---|---|
| North America | 0.31% |
| Europe | 0.34% |
| Asia-Pacific | 0.24% |
| South America | 0.06% |
| Middle East & Africa | 0.05% |
The European lead is structural: ingredient transparency regulation and retailer clean-label mandates have pushed formulators toward documented, traceable hydrolysates. Asia-Pacific growth is demand-led, as domestic brands commercialize wheat-derived proteins across both food and beauty lines. North America retains a strong cosmetics and sports-nutrition base.
Clean-label reformulation is the single largest driver, contributing roughly 1.5 percentage points to CAGR, followed by rising demand in hair and skin care at 1.2 points and hydrolysis process innovation at 0.9 points.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Clean-label protein ingredients in functional foods | Driver | High | Retailer and consumer pressure for short, recognizable ingredient lists |
| Hair and skin care demand | Driver | High | Film-forming and moisture-retention performance vs. synthetic polymers |
| Hydrolysis process innovation | Driver | Medium | Enzymatic and membrane methods improve solubility and peptide targeting |
| Gluten allergen and celiac concerns | Restraint | High | Restricts use in mainstream food and beverage formulations |
| Raw material price volatility | Restraint | Medium | Wheat harvest and energy costs transmit to hydrolysate pricing |
| Regulatory fragmentation | Restraint | Medium | Divergent labeling rules across EU, US and APAC markets |
Our analysis suggests the restraint balance is tilting: advanced hydrolysis can reduce immunoreactive peptide content, potentially opening gluten-sensitive segments previously closed to the category. That is a second-order effect the mainstream literature has not yet priced in.
Archer Daniels Midland, Cargill, Roquette Frères, MGP Ingredients and Kerry Group are the principal players in a medium-concentration field, each leveraging upstream wheat processing or downstream formulation reach.
| Vendor | Position | Differentiation |
|---|---|---|
| Archer Daniels Midland | Global leader | Integrated grain supply and broad protein portfolio |
| Cargill | Global leader | Scale, distribution and food-application formulation support |
| Roquette Frères | Specialist | Plant-protein extraction depth and technical service |
| MGP Ingredients | Specialist | Wheat protein specialization and functional ingredient IP |
| Kerry Group | Global leader | Taste, nutrition and end-to-end formulation integration |
Competitive moats rest on upstream wheat access and hydrolysis process control rather than brand. Our analysis suggests the durable advantage sits with firms that can certify peptide profiles and hydrolysis method per batch, since that documentation is now the procurement gate.
Buyers should prioritize documentation over price. The critical selection criteria are hydrolysis method (enzymatic versus acid or alkaline), peptide molecular weight distribution, declared allergen status and batch-to-batch consistency. Enzymatic hydrolysates command premiums but deliver cleaner labeling.
Procurement risk concentrates in two areas: wheat price volatility and single-source dependency on specialist hydrolysate producers. Qualifying a second supplier typically takes six to twelve months, so dual-sourcing should be initiated well before contract renewal. Switching costs are moderate — reformulation validation in cosmetics is faster than in food, where allergen labeling can force full label revision.
Regulatory compliance is non-trivial. In the EU, the ingredient must meet CosIng and cosmetics regulation requirements, while food applications face allergen labeling obligations. Operators should verify supplier documentation against target-market rules before committing to formulation lock-in.
The balance of evidence favors a moderate-growth, structurally improving category rather than a high-growth one. The 5.78% CAGR is credible, and the disagreement across sources is a scope artifact, not a signal of hidden upside. Our position: the market will outperform the headline CAGR in personal care and underperform in mainstream food, producing a mix shift that rewards specialists.
The strongest counter-argument is that gluten allergenicity caps the category permanently in food, confining growth to cosmetics. We find this partially persuasive but incomplete — hydrolysis innovation is eroding that ceiling faster than consensus assumes.
What would change our conclusion: evidence that gluten-free hydrolysis at scale clears regulatory allergen thresholds, which would materially raise the food and beverage trajectory beyond current forecasts.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers, specialized hydrolysate producers, contract formulators, and global ingredient distributors. Interviewees included VP-level sourcing executives, heads of R&D, technical directors, and commercial operations leads, ensuring both demand-side and supply-side perspectives were captured.
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations, patent databases, and recognized technical standards bodies. Regulatory ingredient inventories and industry association publications were used to corroborate application-level demand assumptions.
Market sizing combined top-down macroeconomic and segment allocation with bottom-up manufacturer capacity, pricing, and end-use consumption modeling. Both approaches were reconciled to produce a consensus base-year value and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.78% from 2020-2034 |
| Segmentation |
|
The global market is valued at approximately 370 million in 2026 and is forecast to reach roughly 490 million by 2031, growing at a 5.78% CAGR over the period.
It is used primarily as a conditioning and moisturizing agent in hair and skin care, and as a functional protein ingredient in bakery, beverages, supplements and premium pet nutrition.
Europe leads global consumption at roughly 34% of volume, supported by a mature food-processing base. Asia-Pacific is the fastest-growing region at close to 6.7% CAGR.
Archer Daniels Midland, Cargill, Roquette Frères, MGP Ingredients and Kerry Group are the principal players, competing on upstream wheat access and hydrolysis process control.
It is derived from wheat and typically carries allergen labeling obligations. Advanced hydrolysis can reduce immunoreactive peptides, but buyers must verify declared allergen status per target market.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers, specialized hydrolysate producers, contract formulators, and global ingredient distributors. Interviewees included VP-level sourcing executives, heads of R&D, technical directors, and commercial operations leads, ensuring both demand-side and supply-side perspectives were captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP Sourcing & Procurement Leads | 35% |
| Heads of R&D & Technical Directors | 30% |
| Quality & Regulatory Affairs Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Wheat Processors | 40% |
| Specialized Hydrolysate Producers | 30% |
| Contract Formulators & Blenders | 18% |
| Global Ingredient Distributors | 12% |
Secondary validation drew on official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings and investor presentations, patent databases, and recognized technical standards bodies. Regulatory ingredient inventories and industry association publications were used to corroborate application-level demand assumptions.
Market sizing combined top-down macroeconomic and segment allocation with bottom-up manufacturer capacity, pricing, and end-use consumption modeling. Both approaches were reconciled to produce a consensus base-year value and compound forecast.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |