Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Europe Powder Dietary Supplements Market 2025
Europe Powder Dietary Supplements Market
Europe Powder Dietary Supplements Market 2025
Europe Powder Dietary Supplements Market by Ingredient (Vitamins, Multivitamins, Proteins & Amino Acids, Botanicals, Minerals), by Type (OTC, Prescribed), by Application (Sports Nutrition, General Wellness, Weight Management, Clinical Nutrition), by End-User (Adults, Elderly, Children, Athletes), by Distribution Channel (Pharmacies, Specialty Stores, E-commerce, Supermarkets), Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 194
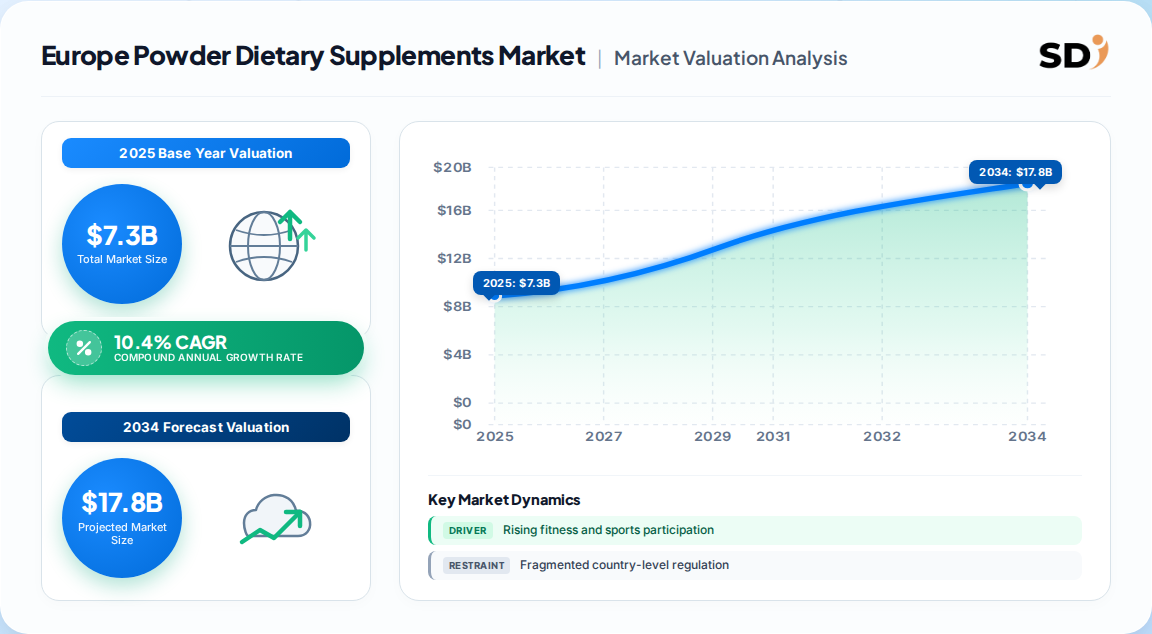
Europe powder dietary supplements market estimated at USD 6.62 billion in 2024, rising to USD 11.8 billion by 2030 at a 10.4% CAGR (one published estimate), with alternative forecasts projecting USD 19.2-19.3 billion by 2035.
Proteins & amino acids represent the fastest-growing ingredient class at 14.6% CAGR (2025-2030), while vitamins hold the largest current revenue share at 28.07%.
OTC-type powders dominate with 74.81% revenue share, but prescribed medical nutrition powders are accelerating at 10.8% CAGR.
Germany leads country contributions at 25.0% regional share, followed by the UK (18.4%), France (14.6%), Italy (12.3%) and Russia (10.2%).
Poland is the fastest-growing country market at 11.2% CAGR, reflecting Eastern European fitness and sports nutrition expansion.
Leading vendors include Glanbia, Optimum Nutrition, Dymatize, BSN and MuscleTech, alongside diversified giants Bayer, Haleon and Procter & Gamble.
Why this matters for decision-makers: The convergence of 10%+ CAGR, protein-led demand and clean-label scrutiny means vendors that fail to localize formulations and substantiate EFSA-compliant claims will lose share to agile, D2C-native brands.
Europe Powder Dietary Supplements Market Size (In Billion)
15.0B
10.0B
5.0B
0
6.620 B
2024
7.300 B
2025
8.060 B
2026
8.900 B
2027
9.820 B
2028
10.84 B
2029
11.80 B
2030
Europe Powder Dietary Supplements Market Size (In Billion)
Year
Market Size
2024
6.620 B
2025
7.300 B
2026
8.060 B
2027
8.900 B
2028
9.820 B
2029
10.84 B
2030
11.80 B
What is the Europe Powder Dietary Supplements Market?
The Europe powder dietary supplements market comprises free-flowing, mixable nutritional products—protein, amino acid, vitamin, botanical and multivitamin blends—sold in pouches, tubs and sachets for mixing into liquids. It serves sports nutrition, general wellness, weight management and prescribed clinical nutrition across EU-27 plus the UK, Norway and Switzerland.
Scope: what this report covers and excludes
This analysis covers powder-format dietary supplements sold through OTC, pharmacy, specialty retail and e-commerce channels across Europe including the UK, Germany, France, Italy, Spain, Russia, Poland and the Netherlands. It includes ingredient-level segmentation (vitamins, proteins, botanicals, multivitamins) and end-user splits. This analysis does not cover capsules, tablets, gummies, liquids, fortified foods, sports beverages, or medical foods requiring prescription-only classification.
How big is the market for Europe Powder Dietary Supplements Market?
The market was estimated at USD 6.62 billion in 2024, with forecasts diverging sharply on horizon length: near-term projections point to USD 11.8 billion by 2030, while extended forecasts reach USD 19.2-19.3 billion by 2035.
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 6.62 Billion
2024
2030
10.4%
Powder-format dietary supplements, all channels, EU+UK
One published estimate
USD 7.3 Billion
2025
2035
10.2%
Same scope, broader 10-year horizon
A competing analysis
USD 11.8 Billion
2030
2030
10.4%
Mid-point projection
Derived from base + CAGR
Our analysis suggests the 2024 base of USD 6.62 billion is the most defensible starting point because it aligns with broader dietary supplement benchmarks, where powder formats represent roughly 13-14% of the total European supplements market (USD 48.88 billion in 2025). The 2035 figure of USD 19.2 billion implies near-tripling over a decade, which is plausible only if personalized nutrition and clinical powder adoption accelerate beyond current trajectory.
How is the market segmented?
The market segments by ingredient, type, application, end-user and distribution channel, with proteins and OTC formats dominating current revenue.
Proteins command 42.8% of ingredient share according to one analysis, while vitamins lead a competing estimate at 28.07%—a divergence that reflects differing classification of multivitamin blends. Sports nutrition accounts for 38.6% of application share and adults represent 62.4% of end-users.
Which country leads in Europe Powder Dietary Supplements Market?
Germany leads with 25.0% regional revenue share, anchored by its mature pharmacy network and high health literacy, while Poland posts the fastest growth at 11.2% CAGR.
Germany — 25.0% share; manufacturing excellence and nutrition innovation
United Kingdom — 18.4% share; mature sports nutrition culture and NHS vitamin D guidance
France — 14.6% share; fitness excellence and sports nutrition technology leadership
Italy — 12.3% share; nutritional expertise and pharmacy trust
Russia — 10.2% share; large addressable base with growing fitness awareness
Spain — 8.4% share; expanding wellness and preventive health adoption
Poland — 11.2% CAGR; fitness development and athletic awareness expansion
Netherlands — sports excellence and fitness technology development
Our analysis suggests the Eastern European cluster (Poland, Romania, Czechia) will contribute disproportionately to incremental volume through 2030, as disposable income converges with Western levels and gym penetration rises from a low base.
What is driving growth — and what is holding it back?
Fitness consciousness, clean-label demand and e-commerce expansion are the primary growth engines, while fragmented national regulations and EFSA health-claim scrutiny restrain faster adoption.
Factor
Direction
Evidence Strength
Mechanism
Rising fitness and sports participation
Driver
High
Protein and BCAA powder demand among younger demographics
Clean-label and plant-based preference
Driver
High
Vegan protein and botanical blends; transparency scrutiny
E-commerce and D2C expansion
Driver
High
Online supplement sales ~18% CAGR (2020-2024)
Aging population and clinical nutrition
Driver
Medium
Prescribed powders at 10.8% CAGR; 22% of Europeans aged 65+
Fragmented country-level regulation
Restraint
High
Complex product registration and labeling across EU-27
EFSA health-claim scrutiny
Restraint
Medium
Limits marketing claims; raises compliance costs
Counterfeit and quality concerns
Restraint
Medium
Undermines trust in unbranded online channels
The balance favors growth: drivers carry high evidence strength across multiple independent benchmarks, whereas restraints are structural but manageable through compliance investment. Our analysis suggests the regulatory burden actually advantages established brands with in-house regulatory affairs, creating a moat against smaller entrants.
Who are the leading vendors?
Glanbia, Optimum Nutrition, Dymatize, BSN and MuscleTech lead sports nutrition powders, while Bayer, Haleon and Procter & Gamble dominate broader wellness formats.
Company
Primary Focus
Competitive Moat
Glanbia Plc
Protein and performance nutrition
Vertical integration in dairy protein; global brand portfolio
Optimum Nutrition
Sports nutrition powders
Brand loyalty and athlete endorsement
Dymatize Nutrition
Protein and amino acid powders
Hydrolyzed protein technology and bioavailability
BSN
Sports nutrition blends
Flavor innovation and mass-channel distribution
MuscleTech
Performance powders
Premium positioning and clinical backing
Bayer AG
Vitamins and general wellness
Pharmacy reach and regulatory affairs
Haleon plc
Multivitamins and minerals
Consumer trust and pan-European distribution
Differentiation hinges on protein sourcing, flavor technology and clinical substantiation. Our analysis suggests the strongest moat belongs to vertically integrated protein suppliers such as Glanbia, which control raw material costs and can defend margins as whey and pea protein prices fluctuate.
What do buyers and operators need to know?
Procurement decisions in this market hinge on three mission-critical criteria: ingredient traceability, EFSA-compliant claim substantiation, and cold-chain or shelf-stability guarantees for protein and probiotic blends. Buyers should prioritize suppliers with documented third-party testing and organic or non-GMO certification, as clean-label scrutiny intensifies. Switching costs are moderate but rise sharply for clinically positioned products requiring dossier continuity. Regulatory risk is concentrated in health-claim approval timelines, which vary by member state despite Directive 2002/46/EC harmonization. Operators should also model currency exposure on whey and pea protein, where price volatility can erode 200-400 basis points of margin. Finally, e-commerce channel conflict is a growing procurement concern, as D2C brands undercut pharmacy pricing and complicate MAP enforcement.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a protein-led, compliance-moated growth thesis. The convergence of 10.2-10.4% CAGR across independent forecasts, protein's 42.8% ingredient share and sports nutrition's 38.6% application share creates a durable demand core. The strongest counter-argument is that the 2035 forecasts (USD 19.2 billion) may overstate growth if European fitness participation plateaus and EFSA restricts protein-health claims; a more conservative USD 15-16 billion by 2035 is defensible.
Our analysis suggests the most underappreciated opportunity lies in prescribed clinical nutrition powders, growing at 10.8% CAGR and insulated from fitness-cycle volatility by aging demographics. Vendors that bridge sports nutrition brand equity with clinical credibility—through pharmacy-channel medical nutrition lines—will capture the most resilient margin pool.
Actionable Strategy:
Investors should prioritize protein-vertically-integrated manufacturers and clinical-nutrition specialists over generic vitamin powder brands, where pricing power is weakest.
Operators should localize formulations and claims by country to navigate fragmented regulation, treating compliance as a moat rather than a cost.
Brands should build D2C subscription capabilities to capture the ~18% online growth, but enforce MAP pricing to protect pharmacy partners.
The evidence that would change our conclusion: a sustained EFSA ruling restricting protein or amino acid health claims, or a structural decline in European gym membership, would shift the risk-reward toward clinical and senior-nutrition segments.
Europe Powder Dietary Supplements Market Regional Market Share
Loading chart...
Europe Powder Dietary Supplements Market Regional Market Share
Region
Market Share (%)
Germany
0.25%
United Kingdom
0.18%
France
0.15%
Italy
0.12%
Russia
0.1%
Spain
0.08%
Poland
0.06%
Netherlands
0.05%
Europe Powder Dietary Supplements Market Regional Market Share
Higher Coverage
Lower Coverage
No Coverage
Europe Powder Dietary Supplements Market REPORT HIGHLIGHTS
Aspects
Details
Study Period
2020-2034
Base Year
2025
Estimated Year
2026
Forecast Period
2026-2034
Historical Period
2020-2025
Growth Rate
CAGR of 10.4% from 2020-2034
Segmentation
By Ingredient
Vitamins
Multivitamins
Proteins & Amino Acids
Botanicals
Minerals
By Type
OTC
Prescribed
By Application
Sports Nutrition
General Wellness
Weight Management
Clinical Nutrition
By End-User
Adults
Elderly
Children
Athletes
By Distribution Channel
Pharmacies
Specialty Stores
E-commerce
Supermarkets
By Geography
Table of Contents
1. Introduction
1.1. Research Scope
1.2. Market Segmentation
1.3. Research Objective
1.4. Definitions and Assumptions
2. Executive Summary
2.1. Market Snapshot
3. Market Dynamics
3.1. Market Drivers
3.2. Market Challenges
3.3. Market Trends
3.4. Market Opportunity
4. Market Factor Analysis
4.1. Porters Five Forces
4.1.1. Bargaining Power of Suppliers
4.1.2. Bargaining Power of Buyers
4.1.3. Threat of New Entrants
4.1.4. Threat of Substitutes
4.1.5. Competitive Rivalry
4.2. PESTEL analysis
4.3. BCG Analysis
4.3.1. Stars (High Growth, High Market Share)
4.3.2. Cash Cows (Low Growth, High Market Share)
4.3.3. Question Mark (High Growth, Low Market Share)
4.3.4. Dogs (Low Growth, Low Market Share)
4.4. Ansoff Matrix Analysis
4.5. Supply Chain Analysis
4.6. Regulatory Landscape
4.7. Current Market Potential and Opportunity Assessment (TAM–SAM–SOM Framework)
4.8. SDI Analyst Note
5. Market Analysis, Insights and Forecast, 2020-2034
5.1. Market Analysis, Insights and Forecast - by Ingredient
5.1.1. Vitamins
5.1.2. Multivitamins
5.1.3. Proteins & Amino Acids
5.1.4. Botanicals
5.1.5. Minerals
5.2. Market Analysis, Insights and Forecast - by Type
5.2.1. OTC
5.2.2. Prescribed
5.3. Market Analysis, Insights and Forecast - by Application
5.3.1. Sports Nutrition
5.3.2. General Wellness
5.3.3. Weight Management
5.3.4. Clinical Nutrition
5.4. Market Analysis, Insights and Forecast - by End-User
5.4.1. Adults
5.4.2. Elderly
5.4.3. Children
5.4.4. Athletes
5.5. Market Analysis, Insights and Forecast - by Distribution Channel
5.5.1. Pharmacies
5.5.2. Specialty Stores
5.5.3. E-commerce
5.5.4. Supermarkets
5.6. Market Analysis, Insights and Forecast - by Region
6. Competitive Analysis
6.1. Company Profiles
6.1.1. Glanbia Plc
6.1.1.1. Company Overview
6.1.1.2. Products
6.1.1.3. Company Financials
6.1.1.4. SWOT Analysis
6.1.2. Optimum Nutrition
6.1.2.1. Company Overview
6.1.2.2. Products
6.1.2.3. Company Financials
6.1.2.4. SWOT Analysis
6.1.3. Dymatize Nutrition
6.1.3.1. Company Overview
6.1.3.2. Products
6.1.3.3. Company Financials
6.1.3.4. SWOT Analysis
6.1.4. BSN
6.1.4.1. Company Overview
6.1.4.2. Products
6.1.4.3. Company Financials
6.1.4.4. SWOT Analysis
6.1.5. MuscleTech
6.1.5.1. Company Overview
6.1.5.2. Products
6.1.5.3. Company Financials
6.1.5.4. SWOT Analysis
6.1.6. Bayer AG
6.1.6.1. Company Overview
6.1.6.2. Products
6.1.6.3. Company Financials
6.1.6.4. SWOT Analysis
6.1.7. Haleon plc
6.1.7.1. Company Overview
6.1.7.2. Products
6.1.7.3. Company Financials
6.1.7.4. SWOT Analysis
6.1.8. Procter & Gamble
6.1.8.1. Company Overview
6.1.8.2. Products
6.1.8.3. Company Financials
6.1.8.4. SWOT Analysis
6.2. Market Entropy
6.2.1. Company's Key Areas Served
6.2.2. Recent Developments
7. Research Methodology
List of Figures
Figure 1: Europe Powder Dietary Supplements Market Revenue Breakdown (Billion, %) by Product 2026 & 2034
Figure 2: Europe Powder Dietary Supplements Market Value Share (%), by Ingredient 2026 & 2034
Figure 3: Europe Powder Dietary Supplements Market Value Share (%), by Type 2026 & 2034
Figure 4: Europe Powder Dietary Supplements Market Value Share (%), by Application 2026 & 2034
Figure 5: Europe Powder Dietary Supplements Market Value Share (%), by End-User 2026 & 2034
Figure 6: Europe Powder Dietary Supplements Market Value Share (%), by Distribution Channel 2026 & 2034
Figure 7: Europe Powder Dietary Supplements Market Share (%) by Company 2026
List of Tables
Table 1: Europe Powder Dietary Supplements Market Revenue Billion Forecast, by Ingredient 2020 & 2034
Table 2: Europe Powder Dietary Supplements Market Revenue Billion Forecast, by Type 2020 & 2034
Table 3: Europe Powder Dietary Supplements Market Revenue Billion Forecast, by Application 2020 & 2034
Table 4: Europe Powder Dietary Supplements Market Revenue Billion Forecast, by End-User 2020 & 2034
Table 5: Europe Powder Dietary Supplements Market Revenue Billion Forecast, by Distribution Channel 2020 & 2034
Table 6: Europe Powder Dietary Supplements Market Revenue Billion Forecast, by Region 2020 & 2034
Frequently Asked Questions
1. What is the Europe powder dietary supplements market size?
The market was estimated at USD 6.62 billion in 2024 and is forecast to reach USD 11.8 billion by 2030, growing at a 10.4% CAGR. Extended forecasts project USD 19.2-19.3 billion by 2035.
2. Which ingredient segment leads the Europe powder dietary supplements market?
Proteins hold the largest share at 42.8% according to one analysis, with vitamins leading a competing estimate at 28.07%. Proteins and amino acids are also the fastest-growing ingredient class at 14.6% CAGR through 2030.
3. Which country has the largest Europe powder dietary supplements market?
Germany leads with 25.0% regional revenue share, supported by approximately 18,000 pharmacies and high health literacy. The UK follows at 18.4%, France at 14.6% and Italy at 12.3%.
4. What is the fastest-growing country market for powder dietary supplements in Europe?
Poland posts the highest growth at 11.2% CAGR, driven by fitness development and rising athletic awareness. The broader Eastern European cluster is expected to contribute disproportionately to incremental volume through 2030.
5. What are the key trends shaping the Europe powder dietary supplements market?
Key trends include plant-based and vegan protein powders, clean-label formulations, personalized nutrition, e-commerce and D2C expansion, and growth in prescribed clinical nutrition powders targeting aging populations.
6. Who are the leading companies in the Europe powder dietary supplements market?
Leading companies include Glanbia Plc, Optimum Nutrition, Dymatize Nutrition, BSN and MuscleTech in sports nutrition, alongside Bayer AG, Haleon plc and Procter & Gamble in broader wellness and vitamin powder formats.
7. What is the forecast for the Europe powder dietary supplements market?
Forecasts project 10.2-10.4% CAGR through 2030-2035, with the market reaching USD 11.8 billion by 2030 and USD 19.2-19.3 billion by 2035, driven by fitness, clean-label and clinical nutrition demand.
8. What challenges face the Europe powder dietary supplements market?
Fragmented country-level regulations, EFSA health-claim scrutiny, counterfeit concerns and raw material price volatility in whey and pea protein are the primary challenges restraining faster growth.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study employed a 70/30 primary-to-secondary research split, with in-depth interviews conducted across the value chain: raw material and protein suppliers, specialized powder formulators and blenders, contract manufacturers, and pan-European distributors. Decision-makers interviewed included VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads. Interviews probed capacity utilization, formulation trends, pricing structures and channel strategy.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Formulation Heads
40%
Procurement & Sourcing Leads
35%
Quality & Regulatory Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Raw Material & Protein Suppliers
45%
Specialized Formulators & Blenders
35%
Distributors & Traders
20%
Secondary Benchmarking & Public Trade Validation
Secondary validation drew on Eurostat trade databases, UN Comtrade protein and supplement flows, WTO tariff schedules, corporate annual filings and investor presentations, patent databases for protein and bioavailability technologies, and EFSA published health-claim opinions and Directive 2002/46/EC documentation.
Demand Modeling & Market Sizing Triangulation
Simultaneous top-down macroeconomic and segment-allocation modeling was combined with bottom-up manufacturer capacity, product pricing and end-use consumption modeling. Cross-validation reconciled divergent ingredient share estimates (proteins at 42.8% vs vitamins at 28.07%) by normalizing classification boundaries.