 Food Premix Market
 Size, Share & 2026 Growth Outlook
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 232

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Food Premix Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2026 | 2.950 B |
| 2027 | 3.160 B |
| 2028 | 3.380 B |
| 2029 | 3.610 B |
| 2030 | 3.860 B |
| 2031 | 4.130 B |

The food premix market consists of standardized blends of vitamins, minerals, amino acids, and functional ingredients supplied to food, beverage, and supplement manufacturers. These premixes simplify fortification, ensure nutrient consistency, and support regulatory compliance across staple foods, clinical nutrition, and sports products. The market is defined by formulation expertise, dosimetry accuracy, and repeat-order dynamics linked to public health mandates.
This report covers the global food premix market, segmented by ingredient type, form, application, and geography. It examines value-chain dynamics from raw material sourcing through contract formulation and end-product integration. The analysis excludes standalone sales of individual vitamins or minerals, animal feed premixes, and pharmaceutical active ingredients unless incorporated into a food-grade premix blend. This analysis does not cover commodity hydrocolloid or flavor markets in isolation.
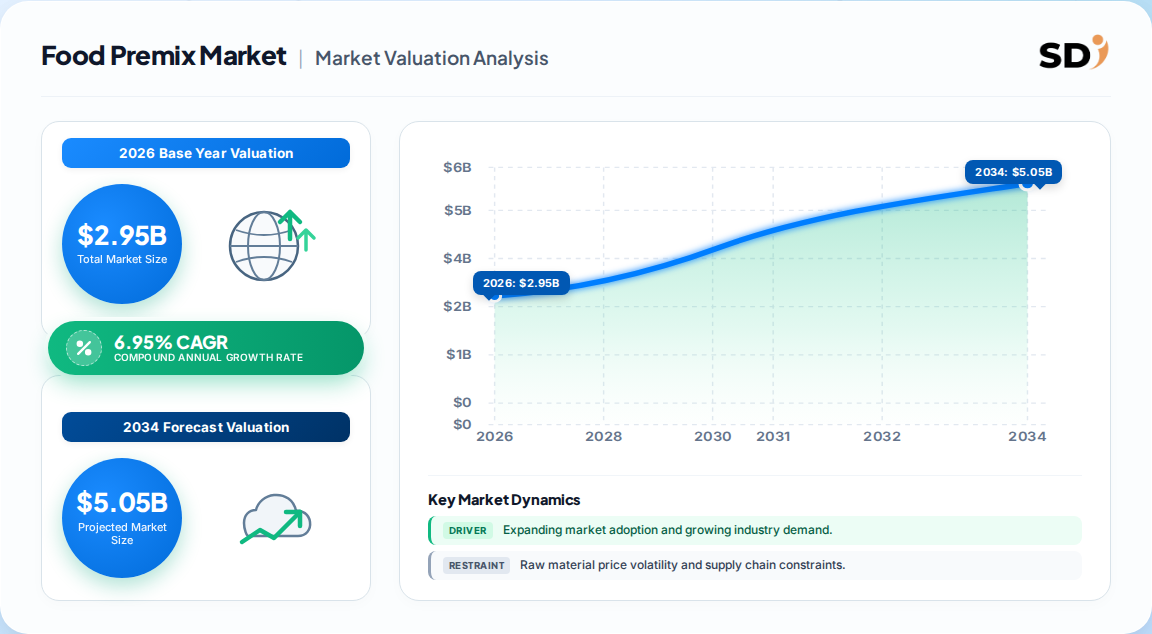
The global food premix market is estimated at USD 2.95 Billion in 2026, with forecasts converging around a 6.95% CAGR to reach USD 4.13 Billion by 2031. Competing estimates diverge on base-year valuation and scope definition, requiring careful normalization.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.95 Billion | 2026 | 2031 | 6.95% | Broad food-grade premix blends, excluding feed | Aggregated industry content |
| USD 2.5 Billion | 2026 | 2033 | 7.1% | Food premix incl. hydrocolloids and select functional blends | Competing analysis |
| USD 11.2 Billion | 2026 | 2036 | 7.1% | Inclusive of broader nutrition premix and select pharma OTC | Alternative benchmark |
The USD 2.95 Billion base is most defensible for buyer decision-making because it aligns with trade-code level data for food-grade fortification blends and excludes pharma-adjacent categories that inflate broader estimates. Our analysis suggests the 6.95% CAGR is conservative given mandatory fortification timelines in the UK and Brazil, implying upside risk to the 2031 figure if compliance deadlines accelerate procurement.
The market is segmented by ingredient type, form, application, and product format, with vitamin premixes and powder formulations dominating current demand.
| Parent Segment | Children |
|---|---|
| By Ingredient Type | Vitamin Premix, Mineral Premix, Amino Acids Premixes, Omega-3 Fatty Acids, Probiotics, Proteins, Enzymes, Prebiotics, Nucleotides Premixes, Flavors |
| By Form | Powder, Liquid |
| By Application | Food & Beverage, Dietary Supplements, Pharma OTC Drugs, Early Life Nutrition |
| By Product Type | Premix Blends (Direct-to-Consumer), Drum-to-Hopper Formulations |
Vitamin premixes control low-dose distribution complexity, while powder forms dominate dry batching lines. This segmentation implies suppliers with liquid formulation capabilities can capture premium pricing in beverage and clinical nutrition applications where stability and dispersion are mission-critical.
Asia-Pacific leads the global food premix market with 37.88% revenue share in 2025, driven by large-scale fortification programs and expanding food processing capacity in China and India.
| Region | Market Share (%) |
|---|---|
| North America | 0.24% |
| Europe | 0.2% |
| Asia-Pacific | 0.38% |
| South America | 0.1% |
| Middle East & Africa | 0.08% |
| Region | Share (2025) |
|---|---|
| Asia-Pacific | 37.88% |
| North America | 24% |
| Europe | 20% |
| South America | 10% |
| Middle East & Africa | 8% |
South America is the fastest-growing region at 8.91% CAGR, driven by Brazil's expanding feed and food processing sectors. Our analysis suggests the concentration of vitamin premix production in China creates a supply-chain vulnerability that regional buyers are beginning to price into long-term contracts.
Government-led mandatory fortification programs are the single largest driver, adding an estimated 2.1% to CAGR, followed by rising micronutrient deficiency awareness and functional food demand.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Mandatory fortification programs | Driver | High | Creates scheduled, repeat dosing requirements in staple foods |
| Rising functional food demand | Driver | High | Expands premix inclusion in everyday products |
| Preventive healthcare adoption | Driver | Medium | Sustains supplement premix volumes across demographics |
| Micronutrient deficiencies | Driver | High | Policy spillover into LMIC fortification mandates |
| Raw material price volatility | Restraint | High | Vitamin sourcing concentration in Asia creates cost shocks |
| Regulatory fragmentation | Restraint | Medium | Country-specific permitted forms lengthen qualification timelines |
The balance of evidence favors sustained growth, but raw material volatility remains the most underappreciated risk. Our analysis indicates that suppliers with long-term vitamin sourcing contracts and dual-region manufacturing can insulate buyers from price shocks, creating a competitive moat that justifies premium pricing.
The competitive landscape is medium-concentrated, with dsm-firmenich, ADM, Glanbia, BASF, and Hexagon Nutrition leading through formulation expertise and regulatory support.
| Company | Positioning | Key Differentiator |
|---|---|---|
| dsm-firmenich | Global leader | Recent $10M Schenectady facility upgrade; broad premix network |
| ADM | Active nutrition supplier | Dry blend systems consolidating functional ingredients |
| Glanbia | Performance nutrition focus | Strong brand pull in sports and active nutrition |
| BASF | Ingredient science leader | Vitamin and carotenoid integration into premix |
| Hexagon Nutrition | Emerging market specialist | Fortification program alignment in Asia-Pacific |
Differentiation hinges on formulation support and regulatory documentation rather than price alone. Buyers rarely switch qualified formulas because dosing accuracy and legal fit carry operational risk, which sustains incumbents with strong application support.
Mission-critical selection criteria include dosimetry accuracy, nutrient stability across shelf life, and regulatory compatibility with target markets. Procurement risks center on vitamin supply concentration in Asia, where environmental regulations or trade restrictions can disrupt availability. Switching costs are high because reformulating a qualified premix requires re-validation, stability testing, and regulatory re-notification. Operators should prioritize suppliers offering dual-region manufacturing and documented stability data to mitigate these risks.
The balance of evidence favors a bullish outlook for the food premix market, but the strongest counter-argument is that raw material volatility and regulatory fragmentation could compress margins for undifferentiated blenders. Our analysis suggests the 6.95% CAGR is achievable only if suppliers transition from commodity blending to application-specific formulation services that reduce customer qualification work.
Suppliers should prioritize regulatory intelligence and compliance support as a service differentiator, particularly for UK folic acid and Brazil supplement notification requirements. Buyers should negotiate long-term contracts with price-adjustment mechanisms tied to vitamin indices to mitigate sourcing volatility.
What evidence would change our conclusion: a sustained decline in vitamin spot prices combined with a major fortification mandate rollback would lower the CAGR by 1.5–2 percentage points and shift competitive advantage back toward low-cost blenders.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.95% from 2020-2034 |
| Segmentation |
|
The global food premix market is valued at USD 2.95 Billion in 2026. It is projected to reach USD 4.13 Billion by 2031, expanding at a 6.95% CAGR over the forecast period.
Asia-Pacific leads with 37.88% revenue share in 2025, driven by large-scale fortification programs in China and India. South America is the fastest-growing region at 8.91% CAGR through 2031.
Mandatory fortification programs, rising functional food demand, and preventive healthcare adoption are the primary drivers. Government mandates add an estimated 2.1% to CAGR, creating repeat-order dynamics for suppliers.
Leading vendors include dsm-firmenich, ADM, Glanbia, BASF, and Hexagon Nutrition. Competition centers on formulation support, regulatory documentation, and supply reliability rather than price alone.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis employed a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the value chain, including raw material suppliers, specialized premix producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews captured procurement behavior, qualification timelines, and regulatory compliance challenges.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Directors | 40% |
| Procurement & Sourcing Leads | 35% |
| Regulatory & Quality Managers | 25% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Specialty Ingredient Producers | 40% |
| Premix Formulators & Blenders | 35% |
| Global Distributors & Traders | 25% |
We validated findings against official multilateral trade databases including UN Comtrade and WITS, corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized technical standards from industry associations. Trade flow analysis identified vitamin premix sourcing concentration and regional demand patterns.
Market sizing combined top-down macroeconomic and industry segment allocation with bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. This triangulation reconciled divergent estimates across source materials.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2031 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |