Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
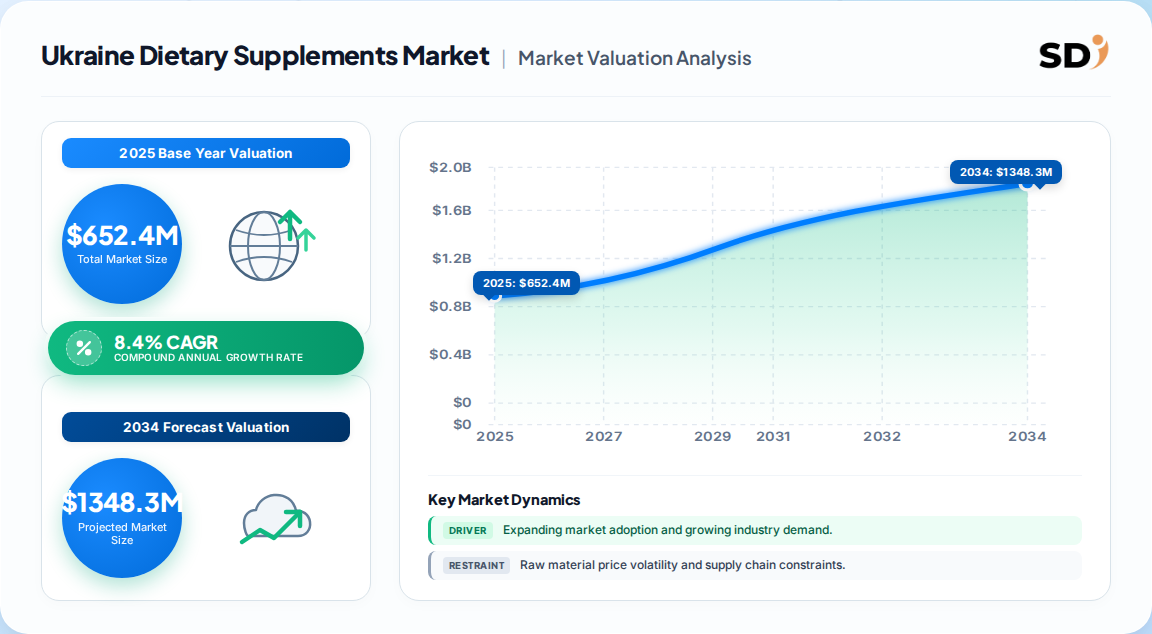
652.4 Million USD was the 2025 retail value of the Ukraine dietary supplements market, with 120 million packs sold at roughly 5.43 USD per pack.
Forecast expansion runs to 1.06 Billion USD by 2031 at an 8.4% CAGR, materially slower than the 17% historical rebound pace of 2020–2025.
Vitamins and minerals remain the anchor category, with vitamins alone at 28.7% of value; tablets hold 29.8% of form share and OTC products 77.9% of type share.
Kyiv and Central Ukraine concentrates roughly 35% of national value, followed by Western Ukraine at 27% on relocation and EU-adjacent logistics.
E-commerce holds about 26% of value and is projected to approach 40% by 2031, reshaping price transparency and national reach.
A fragmented field of roughly 350 players spans Darnitsa, Farmak, Arterium, Biopharma, Omega Pharma, Solgar and Herbalife Ukraine.
Why this matters for decision-makers: with volume growth near 3.4% but value growth above 20%, future margin accrues to brands that win on mix and formulation rather than distribution breadth.
Ukraine Dietary Supplements Market Size (In Million)
750.0M
600.0M
450.0M
300.0M
150.0M
0
297.0 M
2020
423.0 M
2021
323.0 M
2022
467.0 M
2023
543.0 M
2024
652.0 M
2025
721.0 M
2026
Ukraine Dietary Supplements Market Size (In Million)
Year
Market Size
2020
297.0 M
2021
423.0 M
2022
323.0 M
2023
467.0 M
2024
543.0 M
2025
652.0 M
2026
721.0 M
What is the Ukraine Dietary Supplements Market?
The Ukraine dietary supplements market covers over-the-counter and prescribed vitamins, minerals, botanicals, probiotics, omega-3, protein and specialty formulations sold to consumers through pharmacies, e-commerce and retail. It is measured as retail value and pack volume, excluding prescription medicines, hospital sales and clinical nutrition.
Scope: what this report covers and excludes
This analysis covers finished-pack dietary supplements sold to Ukrainian consumers across pharmacy chains, independent pharmacies, digital platforms and grocery retail. It spans ingredient, form, type, application, end-use and distribution dimensions.
This analysis does not cover prescription pharmaceuticals, homeopathic remedies, fortified foods, sports nutrition positioned as muscle-building preparations, or B2B ingredient trading volumes.
How big is the market for Ukraine Dietary Supplements Market?
Published estimates converge on roughly 652 million USD for 2025, but diverge sharply on growth rate: one analysis models 13.8% through 2033, another 8.4% through 2031, and a third 12.2% against a global figure that plainly misapplies country scope.
Estimate
Base year
Horizon
CAGR
Definition / scope
Attribution
582.6M to 1,614.9M
2025
2033
13.8%
Finished supplements, all channels, retail value
One published estimate
652M to 1,057M
2025
2031
8.4%
Nutritional and dietary supplements, pharmacy and digital
The most defensible reading is the 652 million USD base with an 8.4% path, because it reconciles value with reported pack volume, average selling price and channel shares. The 1.2 billion figure and the 4.9 billion series appear to use different scope or geography, and should not anchor procurement decisions.
Our analysis suggests the higher 13.8% forecast implicitly assumes faster purchasing-power recovery and premium-mix acceleration; it is achievable only in an upside scenario where affordability pressure eases materially by 2028.
How is the market segmented?
Segmentation is led by ingredient and product type, with vitamins and minerals dominating value and OTC positioning dominating transaction type. Form and application splits reveal where premiumization is actually occurring.
General health, Immunity, Energy and weight management, Digestive health, Bone and joint, Skin, hair and nails, Cardiovascular, Women's health
End-use
Adults, Elderly, Children, Athletes, Pregnant and lactating women
Distribution
Pharmacy chains, Independent pharmacies, E-commerce, Grocery and specialty retail
Which sub-region leads in Ukraine Dietary Supplements Market?
Kyiv and Central Ukraine leads with an estimated 35% of 2025 value, supported by dense chain-pharmacy coverage, national distributor warehousing and the country's largest online fulfilment networks. Western Ukraine follows at 27%, lifted by population relocation and EU supply proximity.
This concentration implies that national key-account access and resilient westbound logistics are the two structural determinants of scale economics. Operators without Kyiv chain listings face materially higher cost-to-serve.
What is driving growth — and what is holding it back?
Preventive health behaviour and channel digitization are the dominant growth engines, while household affordability and conflict-related disruption cap the pace. Price and mix, not physical penetration, explain most recent value growth.
Factor
Direction
Evidence strength
Mechanism
Preventive healthcare awareness
Driver
Strong
Consumers add vitamins and probiotics to daily routines
Aging population
Driver
Strong
Bone, joint, cardiovascular and cognitive demand
E-commerce expansion
Driver
Strong
26% of value, approaching 40% by 2031
Product innovation
Driver
Moderate
Gummies, sachets and combination formats lift ASP
Economic uncertainty
Restraint
Strong
70% of consumers cite price as primary purchase factor
Conflict disruption
Restraint
Strong
2022 volume trough of 31.9%; logistics and migration risk
Regulatory composition rules
Restraint
Moderate
Product delisting risk under new notification requirements
The balance favours growth, but the mechanism is narrow. Volume rose only 3.4% in 2025 while value rose 20.1%, so demand is being monetized through price and premium mix rather than broader consumption. This divergence implies affordability is the binding constraint on unit growth.
Who are the leading vendors?
No single vendor holds dominant share in a field of roughly 350 participants; domestic pharmaceutical manufacturers lead on pharmacy access and trust, while international brands lead on premium positioning and science-backed claims.
Vendor
Positioning
Core strength
Darnitsa
Domestic pharma leader
Pharmacy coverage and brand trust
Farmak
Domestic manufacturer
Manufacturing scale and portfolio breadth
Arterium
Domestic manufacturer
Hospital and pharmacy relationships
Biopharma
Domestic biologics and supplements
Distribution depth
Omega Pharma
Regional consumer health
Branded OTC supplements
Solgar
International premium
Science-backed premium formulations
Herbalife Ukraine
Direct and digital retail
Loyal consumption base
Differentiation rests on three moats: pharmacy shelf access, regulatory notification readiness, and pack-price architecture tuned to a low average income. Domestic players defend on affordability and availability; importers defend on formulation credibility.
What do buyers and operators need to know?
Selection criteria should weight regulatory notification status, batch-level quality documentation and pack-price fit before formulation novelty. Ukraine's composition and labelling rules have tightened since 2023, and non-compliant SKUs risk delisting mid-cycle.
Procurement risk concentrates in three areas: currency exposure on imported actives, logistics disruption affecting westbound routes, and supplier concentration among a small set of domestic manufacturers. Buyers should contract with dual-sourcing clauses and index-linked pricing.
Switching costs are moderate. Private-label substitution is viable in vitamins and minerals but far harder in clinically positioned probiotics and specialty women's health, where brand trust and evidence claims carry real pricing power.
Strategic Recommendations & Analyst Perspective
The balance of evidence favours the 8.4% trajectory over the 13.8% forecast. Value growth of 20% against 3.4% volume growth cannot persist indefinitely; it depends on premiumization and price, both of which are constrained by a 70% price-sensitive consumer base.
The strongest counter-argument is that e-commerce expansion to 40% of value could unlock faster premium adoption and accelerate mix shift beyond our base case. That is credible, but it requires payment infrastructure and delivery resilience that remain uneven outside Kyiv and Western Ukraine.
Operators: Prioritize probiotics, women's health and age-specific formulations, where ASP growth outpaces category averages and private-label substitution is weakest.
Investors: Underwrite pharmacy key-account access and westbound logistics before portfolio breadth; distribution resilience, not SKU count, drives cash conversion.
Brands: Build a two-tier pack architecture that defends economy share while capturing premium margin through gummies and sachets.
Our conclusion would change if two conditions emerged: sustained volume growth above 6% annually, or a durable stabilization in household purchasing power that reopens discretionary premium spend. Precise sub-segment forecasting, SKU-level pricing and regional channel economics require the full report.
Research Methodology
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split. In-depth interviews were conducted across raw material suppliers, specialized supplement producers, contract formulators, pharmacy chain buyers and import distributors operating in Ukraine.
Secondary Benchmarking & Public Trade Validation
Benchmarking draws on UN Comtrade and Eurostat trade flows, national statistical office retail data, corporate annual filings and investor presentations, patent databases, and technical standards published by recognized industry associations.
Demand Modeling & Market Sizing Triangulation
Top-down macroeconomic allocation and bottom-up manufacturer capacity, pricing and consumption modeling run simultaneously, with divergence flagged and reconciled before finalization.
Data Triangulation & Validation Matrix
Dimension
Analytical Scope
Methodology Applied
Validation Level
Base-Year Market Size
Value in USD for base year
Bottom-up production and revenue triangulation
High
Forecast Horizon
Multi-year compound projection
Historical CAGR, regression and demand elasticity
High
Regional Distribution
Regional share breakdown
Trade flow analysis and regional consumption
High
Competitive Landscape
Leading market players
Annual reports, capacity mapping and filings
High
Sources Referenced
UN Comtrade and Eurostat bilateral trade statistics
State Service of Ukraine on Food Safety and Consumer Protection notification registers
European Botanical and Nutraceutical Industry Association technical guidance
Figure 2: Ukraine Dietary Supplements Market Value Share (%), by Ingredient 2026 & 2034
Figure 3: Ukraine Dietary Supplements Market Value Share (%), by Form 2026 & 2034
Figure 4: Ukraine Dietary Supplements Market Value Share (%), by Type 2026 & 2034
Figure 5: Ukraine Dietary Supplements Market Value Share (%), by Application 2026 & 2034
Figure 6: Ukraine Dietary Supplements Market Value Share (%), by End-use 2026 & 2034
Figure 7: Ukraine Dietary Supplements Market Value Share (%), by Distribution Channel 2026 & 2034
Figure 8: Ukraine Dietary Supplements Market Share (%) by Company 2026
List of Tables
Table 1: Ukraine Dietary Supplements Market Revenue Million Forecast, by Ingredient 2020 & 2034
Table 2: Ukraine Dietary Supplements Market Volume Million Packs Forecast, by Ingredient 2020 & 2034
Table 3: Ukraine Dietary Supplements Market Revenue Million Forecast, by Form 2020 & 2034
Table 4: Ukraine Dietary Supplements Market Volume Million Packs Forecast, by Form 2020 & 2034
Table 5: Ukraine Dietary Supplements Market Revenue Million Forecast, by Type 2020 & 2034
Table 6: Ukraine Dietary Supplements Market Volume Million Packs Forecast, by Type 2020 & 2034
Table 7: Ukraine Dietary Supplements Market Revenue Million Forecast, by Application 2020 & 2034
Table 8: Ukraine Dietary Supplements Market Volume Million Packs Forecast, by Application 2020 & 2034
Table 9: Ukraine Dietary Supplements Market Revenue Million Forecast, by End-use 2020 & 2034
Table 10: Ukraine Dietary Supplements Market Volume Million Packs Forecast, by End-use 2020 & 2034
Table 11: Ukraine Dietary Supplements Market Revenue Million Forecast, by Distribution Channel 2020 & 2034
Table 12: Ukraine Dietary Supplements Market Volume Million Packs Forecast, by Distribution Channel 2020 & 2034
Table 13: Ukraine Dietary Supplements Market Revenue Million Forecast, by Region 2020 & 2034
Table 14: Ukraine Dietary Supplements Market Volume Million Packs Forecast, by Region 2020 & 2034
Table 15: Kyiv & Central Ukraine Ukraine Dietary Supplements Market Revenue Million Forecast, by Ingredient 2020 & 2034
Kyiv & Central Ukraine Ukraine Dietary Supplements Market Volume Million Packs Forecast, by Ingredient 2020 & 2034
Frequently Asked Questions
1. How big is the Ukraine dietary supplements market?
The Ukraine dietary supplements market was valued at approximately 652.4 million USD in 2025, with retail volume near 120 million packs. Forecasts project growth to roughly 1.06 billion USD by 2031.
2. What is the growth rate of the Ukraine dietary supplements market?
Consensus forecast growth is about 8.4% CAGR through 2031, moderating from a 17% historical 2020-2025 average. Some estimates model 13.8% through 2033, but these assume faster purchasing-power recovery.
3. Which segment leads the Ukraine dietary supplements market?
Vitamins and minerals dominate, with vitamins at 28.7% of 2025 value. Tablets hold 29.8% of form share, OTC products represent 77.9% of type share, and general health is the largest application at 21.9%.
4. Which region leads the Ukraine dietary supplements market?
Kyiv and Central Ukraine leads with roughly 35% of 2025 value, supported by chain-pharmacy density and national distribution. Western Ukraine follows at 27%, buoyed by population relocation and EU supply routes.
5. Who are the leading vendors in the Ukraine dietary supplements market?
The market includes roughly 350 players. Key domestic names include Darnitsa, Farmak, Arterium, Biopharma and Omega Pharma, alongside international brands such as Solgar and Herbalife Ukraine.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
This study applies a 70/30 primary-to-secondary research split, prioritizing direct validation with commercial decision-makers. In-depth interviews were conducted with raw material and active-ingredient suppliers, specialized supplement producers, contract formulators and blenders, national pharmacy distributors, and import and e-commerce channel operators. Interviewees were drawn from designated roles including VP of Sourcing, Heads of R&D and Formulation, Technical and Quality Directors, Regulatory Affairs Managers, and Commercial Operations Leads. Structured questionnaires were paired with semi-structured deep interviews to capture both quantitative volume data and qualitative channel economics.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
Sourcing & Procurement Directors
35%
R&D & Formulation Heads
30%
Regulatory & Quality Leads
20%
Commercial & Channel Operations
15%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
Supplement Producers & Brand Owners
40%
Raw Material & Active Ingredient Suppliers
25%
Pharmacy Distributors & Channel Operators
20%
Contract Formulators & Blenders
15%
Secondary Benchmarking & Public Trade Validation
Secondary validation draws on official multilateral trade databases (UN Comtrade, Eurostat, WTO tariff records), national statistical office retail and demographic data, corporate annual filings and SEC-equivalent disclosures, patent and trademark databases, and recognized non-profit technical standards and industry association publications. No third-party market research publishers were used as primary validation sources.
Demand Modeling & Market Sizing Triangulation
Market sizing combines simultaneous top-down allocation from macroeconomic and consumer health expenditure indicators with bottom-up modeling of manufacturer capacity, pack pricing and end-use consumption. Divergences between the two models are reconciled at segment level before the base-year figure is finalized.


 Ukraine Dietary Supplements Market