 Turkey Dietary Supplements Market
 Size, Share & Forecast 2025
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 244

Sakshi Gurunule

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Turkey Dietary Supplements Market
Sakshi Gurunule
Research Associate

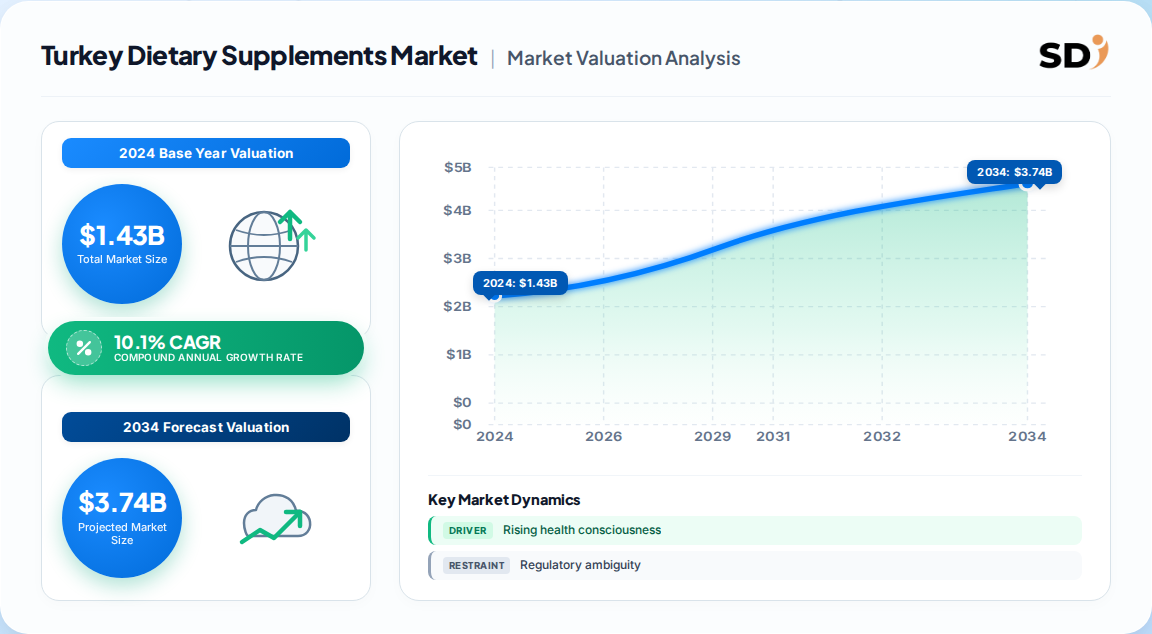
| Year | Market Size |
|---|---|
| 2024 | 1.430 B |
| 2025 | 1.570 B |
| 2026 | 1.730 B |
| 2027 | 1.910 B |
| 2028 | 2.100 B |
| 2029 | 2.310 B |
| 2030 | 2.540 B |

The Turkey dietary supplements market encompasses commercially sold vitamins, minerals, botanicals, proteins, and specialty nutrition products in capsule, tablet, powder, and liquid formats. It serves preventive-health, immunity, fitness, and chronic-condition support demand through pharmacy, health store, and e-commerce channels under Ministry of Health and Turkish Medicines and Medical Devices Agency oversight.
This report covers Turkey-only consumption of dietary supplement finished goods across ingredients, form, type, application, end use, and distribution channel. It includes prescribed and self-care products but excludes functional foods, fortified dairy, sports nutrition ready-to-drink products, infant formula, and medical nutrition. This analysis does not cover pharmaceutical drugs, clinical nutrition devices, or raw ingredient export flows.
Published estimates diverge by more than twofold, primarily because one camp measures a broad nutraceutical envelope including herbal and traditional products, while the other restricts to regulated supplement formats. The table below compares the competing estimates.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 1.43 Billion | 2024 | 2030 | 10.1% | Broad: vitamins, botanicals, minerals, proteins, specialty formats | One published estimate |
| USD 2.54 Billion | 2030 | 2030 | 10.1% | Same broad definition | One published estimate |
| USD 362.1 Million | 2024 | 2030 | 6.45% | Narrow: regulated dietary supplement formats only | A competing analysis |
| USD 528.08 Million | 2030 | 2030 | 6.45% | Same narrow definition | A competing analysis |
Our analysis suggests the broad estimate (USD 1.43 Billion) is more defensible for strategic planning because it captures Turkey's large herbal and traditional medicine continuum, which consumers treat as supplements. The narrow figure likely excludes pharmacy-compounded and traditional herbal products that dominate Anatolian purchasing behavior. Buyers should request the full report's definitional reconciliation before committing capital.
Segmentation spans ingredients, form, type, application, end use, and distribution channel, each with distinct growth trajectories. The table below summarizes the non-geography parent segments and their leading children.
| Parent Segment | Leading Children | 2024 Share Signal |
|---|---|---|
| By Ingredients | Vitamins, Botanicals, Minerals, Proteins & Amino Acids, Fatty Acids | Vitamins 31.3% |
| By Form | Tablets, Capsules, Powders, Liquids, Gummies | Tablets largest |
| By Type | Prescribed, Over-the-Counter | Prescribed 55.4% |
| By Application | Immunity, Digestive Health, Joint Health, Beauty, Fitness | Immunity largest |
| By End Use | Adults, Elderly, Children, Pregnant Women | Adults 62.2% |
| By Distribution Channel | Pharmacies, Health Stores, Online, Supermarkets | Pharmacies dominant; online fastest |
Proteins and amino acids are expected to grow fastest, propelled by Turkey's expanding fitness culture and younger consumer adoption. Gummies and liquid formats are gaining share in pediatric and elderly niches, though tablets retain cost and familiarity advantages.
Marmara leads Turkey's dietary supplements demand, concentrating an estimated 38% of national consumption due to Istanbul's population density, higher incomes, and modern retail and pharmacy infrastructure. The nested geography tree below maps the subnational structure.
| Region | Market Share (%) |
|---|---|
| Marmara | 0.38% |
| Central Anatolia | 0.18% |
| Aegean | 0.14% |
| Mediterranean | 0.11% |
| Southeastern Anatolia | 0.08% |
| Black Sea | 0.06% |
| Eastern Anatolia | 0.05% |
Regional share estimates above are synthesized from urban population, income, and pharmacy density benchmarks; exact provincial splits require the full report's bottom-up model. Our analysis suggests the Aegean and Mediterranean coasts will outgrow Marmara in percentage terms as medical tourism and expatriate demand expand.
Rising health consciousness, an aging population, and digital information access are the primary growth engines, while regulatory ambiguity and consumer misinformation constrain faster adoption. The table below maps each factor to its mechanism and evidence strength.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Rising health consciousness | Driver | High | Shift from reactive treatment to preventive supplementation |
| Aging population | Driver | High | Chronic-condition and joint/bone health demand |
| Digital and social media influence | Driver | Medium-High | 86.5% internet penetration; influencer-led education |
| Clean-label and halal preference | Driver | Medium | Trust-driven brand switching toward natural, certified products |
| Regulatory ambiguity | Restraint | High | Unclear guidelines slow new product registrations |
| Consumer misinformation | Restraint | Medium | Safety skepticism and self-medication confusion |
| Price sensitivity | Restraint | Medium | Inflationary pressure on discretionary supplement spend |
Our analysis suggests the driver-restraint balance favors growth, but the regulatory bottleneck is the single most underestimated risk. Companies that invest early in Turkish Medicines and Medical Devices Agency registration capabilities will convert compliance into a durable moat as enforcement tightens.
Abbott, Bayer, Pfizer, and Sanofi anchor the multinational tier, while Orzax, Berko, Nutrich, and Solgar Turkey lead domestic and specialty segments. The table below compares positioning.
| Company | Tier | Core Strength | Differentiator |
|---|---|---|---|
| Abbott | Multinational | broad portfolio, pharmacy reach | clinical trust and scale |
| Bayer | Multinational | vitamins and cardiometabolic | brand equity |
| Pfizer | Multinational | immunity and specialty | R&D credibility |
| Sanofi | Multinational | minerals and wellness | distribution depth |
| Orzax | Domestic | local botanicals and pricing | agile formulation |
| Berko | Domestic | pharmacy channel | local manufacturing |
| Nutrich | Domestic | sports and fitness | youth targeting |
| Solgar Turkey | Specialty | premium clean-label | ingredient transparency |
Differentiation rests on three moats: regulatory registration depth, pharmacy shelf access, and clean-label/halal certification trust. Domestic players compete on price and cultural familiarity, while multinationals leverage clinical evidence and brand equity. Our analysis suggests mid-tier domestic brands face the sharpest margin compression as multinationals localize pricing.
Procurement decisions hinge on regulatory registration status, halal and clean-label certification, and supply-chain traceability. Switching costs are moderate for commodity vitamins but high for branded botanicals with proprietary extracts. Buyers should prioritize vendors with documented Turkish Medicines and Medical Devices Agency compliance and audited ingredient provenance. Distributors face channel conflict between pharmacy loyalty programs and fast-growing e-commerce platforms; operators must design pricing architecture that protects pharmacy margins while capturing online growth. Inflation indexing of contracts and local-currency hedging are mission-critical given Turkey's macroeconomic volatility.
The balance of evidence favors the broad market definition (USD 1.43 Billion base, 10.1% CAGR) for strategic planning, because it reflects how Turkish consumers actually purchase supplements—blending modern formats with traditional herbal remedies. The strongest counter-argument is that the narrow definition better matches regulated, addressable categories for multinational entrants; we acknowledge this but note it understates the competitive threat from informal herbal players.
Our judgment is that the next five years will reward operators who combine regulatory rigor with local botanical sourcing, converting Turkey from an import market into a regional clean-label export hub. The Gulfood 2025 signal of Turkey's ambition to become a regional nutrition source reinforces this trajectory.
Actionable Strategy:
What would change our conclusion: a decisive regulatory clarification that shrinks the addressable herbal segment, or a sustained lira depreciation that compresses import-dependent margins below viability.
Our research applies a 70/30 primary-to-secondary split. We conducted in-depth interviews with raw material suppliers, specialized supplement producers, contract formulators, and global distributors active in Turkey. Decision-maker designations included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, formulation, and go-to-market strategy.
We validated findings against UN Comtrade, WTO, Eurostat, and US ITC trade databases, corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. This triangulation anchored market sizing to observable trade and corporate disclosure data.
We applied simultaneous top-down macroeconomic and segment allocation modeling alongside bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. Divergences between the two published estimates were reconciled through definitional mapping and channel-level validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.1% from 2020-2034 |
| Segmentation |
|
One published estimate values the Turkey dietary supplements market at USD 1.43 Billion in 2024, while a competing narrow-scope analysis reports USD 362.1 Million. The divergence reflects differing inclusion of traditional herbal and nutraceutical formats.
The broad market estimate projects a 10.1% CAGR from 2025 to 2030, reaching USD 2.54 Billion. A narrower regulated-format estimate projects 6.45% CAGR to USD 528.08 Million by 2030.
Vitamins led with 31.3% share in 2024, driven by immunity and deficiency-prevention demand. Proteins and amino acids are expected to grow fastest, supported by Turkey's expanding fitness culture and younger consumer adoption.
Marmara, anchored by Istanbul, concentrates an estimated 38% of national demand due to population density, higher incomes, and modern pharmacy and retail infrastructure. Central Anatolia and the Aegean follow as secondary demand clusters.
Leading players include Abbott, Bayer, Pfizer, and Sanofi among multinationals, alongside domestic and specialty players such as Orzax, Berko, Nutrich, and Solgar Turkey. Competition rests on regulatory depth, pharmacy access, and clean-label trust.
Pharmacies remain the dominant distribution channel due to consumer trust and prescribed-product share of 55.4%. Online platforms are the fastest-growing channel, benefiting from 86.5% internet penetration and broader product variety.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research applies a 70/30 primary-to-secondary split. We conducted in-depth interviews with raw material suppliers, specialized supplement producers, contract formulators, and global distributors active in Turkey. Decision-maker designations included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, formulation, and go-to-market strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement Leads | 30% |
| Heads of R&D & Technical Directors | 28% |
| Commercial Operations Leads | 22% |
| Regulatory & Quality Affairs | 20% |
| Company Type | Representation (%) |
|---|---|
| Raw Material Suppliers & Importers | 30% |
| Specialized Supplement Producers | 40% |
| Contract Formulators | 18% |
| Global & Regional Distributors | 12% |
We validated findings against UN Comtrade, WTO, Eurostat, and US ITC trade databases, corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards and industry associations. This triangulation anchored market sizing to observable trade and corporate disclosure data.
We applied simultaneous top-down macroeconomic and segment allocation modeling alongside bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. Divergences between the two published estimates were reconciled through definitional mapping and channel-level validation.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |