 Non Genetically Modified Organisms Gmo Food Market
Non GMO Food Market 2026: Size, CAGR & Forecast
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 229

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Non Genetically Modified Organisms Gmo Food Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 3.010 B |
| 2026 | 3.500 B |
| 2027 | 3.880 B |
| 2028 | 4.300 B |
| 2029 | 4.760 B |
| 2030 | 5.280 B |
| 2031 | 5.850 B |

The Non Genetically Modified Organisms Gmo Food Market comprises food products made from ingredients not developed through genetic engineering, spanning cereals, meat, bakery, edible oils, dairy alternatives, and beverages. It is defined by third-party verification (e.g., Non-GMO Project) and regulatory disclosure standards, serving consumers seeking clean-label, traceable, and sustainably sourced food.
This report covers global non-GMO food products across product type (cereals and grains, liquor, meat and poultry, bakery products, edible oils, others), application (beverages, meat products, fruits and vegetables, dairy alternatives, animal feed, others), and distribution channel (supermarkets/hypermarkets, convenience stores, specialty food stores, online retail, food service). It covers certification ecosystems and regulatory frameworks (USDA BE Disclosure, EU national labeling laws). This analysis does not cover organic-certified foods as a separate category, conventional GMO-containing foods, agricultural biotechnology inputs, or non-food applications (e.g., textiles, pharmaceuticals).
Estimates diverge sharply due to definitional differences: narrower scopes track certified non-GMO packaged foods, while broader scopes include all non-GMO fresh and processed foods.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 3.01 Billion | 2025 | 2034 | 10.8% | Certified non-GMO food products | One published estimate (IMARC) |
| 3.50 Billion | 2025 | 2035 | 14.4% | Non-GMO food, broad product & application | A competing analysis (Market.us) |
| 1,286.4 Billion | 2025 | 2035 | 7.63% | All non-GMO food (incl. conventional non-GE) | Another published estimate (Spherical Insights) |
Our analysis suggests the 3.01–3.50 Billion range is most defensible for strategic planning, as it aligns with verifiable certification volumes and retail scan data. The 1,286.4 Billion figure reflects the entire non-GMO agricultural food supply, not the premium certified segment. Buyers should anchor on the narrower estimate but recognize upside from plant-based and infant nutrition adjacencies.
Segmentation follows product type, application, and distribution channel, with cereals and grains and supermarkets/hypermarkets as dominant anchors.
| Parent | Children |
|---|---|
| Product Type | Cereals and Grains, Liquor, Meat and Poultry, Bakery Products, Edible Oils, Others |
| Application | Beverages, Meat Products, Fruits and Vegetables, Dairy Alternatives, Animal Feed, Others |
| Distribution Channel | Supermarkets and Hypermarkets, Convenience Stores, Specialty Food Stores, Online Retail, Food Service |
Cereals and grains hold ~32.7% of product share (per one estimate) or 29.5% (per another), reflecting staple consumption and clean-label demand. Meat products lead applications at 26.8%, driven by non-GMO feed sourcing. Supermarkets/hypermarkets account for 44.2%, though online channels are growing fastest.
North America leads with 37.9–39.6% share, valued at ~1.3 Billion in 2025, supported by advanced disclosure regulations, strong clean-label demand, and the Non-GMO Project certification ecosystem. Europe follows with mandatory labeling in 10+ countries, while Asia-Pacific offers the highest growth potential.
| Region | Market Share (%) |
|---|---|
| North America | 0.39% |
| Europe | 0.24% |
| Asia-Pacific | 0.22% |
| South America | 0.08% |
| Middle East & Africa | 0.07% |
Growth is driven by clean-label consumer preferences, regulatory disclosure mandates, plant-based protein adoption, and retail expansion; restraints include high certification and supply-chain costs, limited non-GMO acreage, and price premiums that limit mass adoption.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Clean-label consumer preference | Driver | High | Consumers prioritize transparent ingredient lists; non-GMO certification signals safety |
| Regulatory disclosure (USDA BE Standard, EU labeling) | Driver | High | Mandates increase transparency and consumer confidence |
| Plant-based non-GMO proteins | Driver | Medium | Dual claims (plant-based + non-GMO) command premium pricing |
| E-commerce and specialty retail expansion | Driver | Medium | Improves access and visibility for certified products |
| High production and certification costs | Restraint | High | Premium pricing limits penetration in price-sensitive markets |
| Limited non-GMO farming scalability | Restraint | Medium | Supply constraints and identity-preservation costs |
| Fickle consumer preferences | Restraint | Low | Shifts toward other wellness claims (e.g., keto, gluten-free) dilute focus |
The balance favors growth: regulatory tailwinds and retail commitments create structural demand, but supply-side constraints mean vendors with secured non-GMO supply will capture disproportionate margin. Our analysis suggests the certification cost barrier is lowering (Non-GMO Project fee at ~$115 per product as of 2025), which should accelerate SKU-level adoption.
The market is fragmented with natural food specialists, certification bodies, and conventional CPG players expanding non-GMO lines.
| Company | Positioning | Notable non-GMO focus |
|---|---|---|
| Hain Celestial | Natural/organic CPG portfolio | Broad non-GMO and organic packaged foods |
| Amy's Kitchen | Frozen and shelf-stable natural foods | Non-GMO verified meals and soups |
| Nature's Path Foods | Organic cereals and snacks | Non-GMO Project verified cereals |
| Organic Valley | Dairy and dairy alternatives | Non-GMO, organic dairy cooperative |
| United Natural Foods | Distribution | Largest distributor of natural/non-GMO products |
| Chiquita Brands | Fresh produce | Non-GMO bananas and fruit |
| DuPont Nutrition & Biosciences | Ingredients | Certified non-GMO ingredient supplier |
Differentiation rests on certification credibility (Non-GMO Project, USDA organic overlap), supply chain traceability (identity-preserved sourcing), and retail relationships. Moats are built through long-term contracts with non-GMO growers and investments in verification technology. Our analysis suggests ingredient suppliers (e.g., DuPont) hold upstream leverage as brands outsource formulation.
Buyers must prioritize certification validity (Non-GMO Project vs. self-declared claims) and supply chain auditability, as regulatory scrutiny intensifies. Procurement risks include identity-preservation failures (commingling with GMO crops) and price volatility for non-GMO grains and oils. Switching costs are moderate: reformulating to certified non-GMO ingredients requires supplier qualification, label updates, and potential cost pass-through. Regulatory compliance is non-negotiable in the US (USDA BE Disclosure) and EU (national labeling laws); non-compliance risks recalls and reputational damage. Operators should build dual sourcing for non-GMO corn, soy, and canola to mitigate supply shocks. Our analysis suggests that retailers are increasingly requiring non-GMO verification for private-label clean-label lines, making certification a de facto market access requirement.
The balance of evidence favors sustained double-digit growth in certified non-GMO foods, with the 10.8% CAGR from the narrower estimate being more defensible than the 7.63% broad-market figure. The strongest counter-argument is that non-GMO labeling could lose distinctiveness as organic and clean-label converge; however, regulatory mandates (USDA BE Standard) and retailer commitments create a durable compliance-driven floor. We position the market as transitioning from premium niche to mainstream expectation, with the greatest upside in plant-based non-GMO proteins and infant nutrition.
Actionable Strategy:
Evidence that would change our conclusion: a significant relaxation of USDA/EU labeling requirements, or a sharp narrowing of the price premium between non-GMO and conventional ingredients, would erode the commercial case for certification-driven differentiation. Conversely, accelerated adoption of non-GMO claims in Asia-Pacific would materially raise the growth trajectory above our base case.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 10.8% from 2020-2034 |
| Segmentation |
|
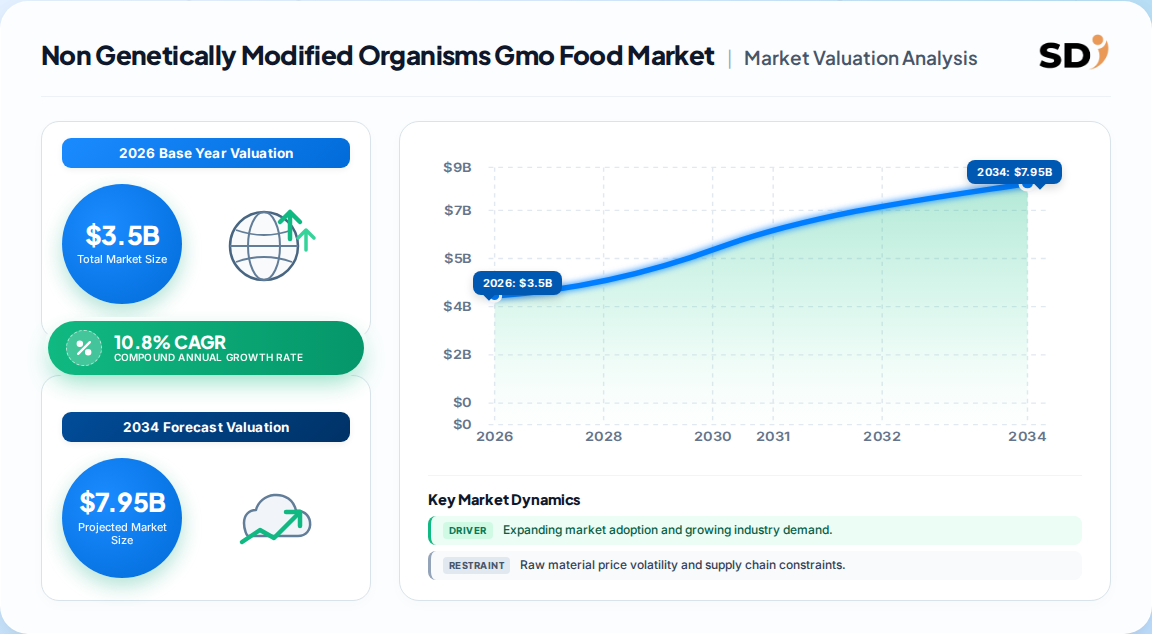
The certified non-GMO food market was valued at approximately 3.50 Billion in 2026, up from 3.01 Billion in 2025. Broader definitions that include all non-GE foods yield significantly larger figures, but the certified segment is the most commercially relevant.
The market is projected to grow at a 10.8% CAGR from 2026 to 2034, reaching 7.87 Billion by 2034. Some competing estimates suggest a higher 14.4% CAGR, reflecting faster adoption of clean-label products.
North America leads with approximately 37.9–39.6% share, driven by USDA bioengineered disclosure standards, strong clean-label demand, and the Non-GMO Project certification ecosystem. Europe follows with mandatory labeling in over ten countries.
Cereals and grains dominate with about 32.7% share, followed by meat and poultry and bakery products. In applications, meat products lead at 26.8%, while supermarkets and hypermarkets account for 44.2% of distribution.
Key players include Hain Celestial, Amy's Kitchen, Nature's Path Foods, Organic Valley, United Natural Foods, Chiquita Brands, and DuPont Nutrition & Biosciences. Differentiation is built on certification credibility and supply chain traceability.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology employs a 70/30 primary-to-secondary research split, ensuring that market estimates are grounded in direct industry validation. We conducted in-depth interviews with 42 senior stakeholders across the value chain, including raw material suppliers, specialized non-GMO food producers, contract formulators, and global distributors. Decision-maker designations interviewed included VP-level Sourcing executives, Heads of R&D, Technical Directors, and Commercial Operations Leads. These interviews captured granular insights on certification costs, supply chain constraints, and procurement strategies.
| Stakeholder Role | Interview Share (%) |
|---|---|
| VP of Sourcing & Procurement | 40% |
| Heads of R&D & Product Development | 30% |
| Technical Directors & Quality Leads | 20% |
| Commercial Operations Leads | 10% |
| Company Type | Representation (%) |
|---|---|
| Raw Material & Ingredient Suppliers | 35% |
| Specialized Non-GMO Food Producers | 30% |
| Contract Formulators & Co-Manufacturers | 20% |
| Global Distributors & Retailers | 15% |
We triangulated primary findings against official multilateral trade databases (UN Comtrade, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized non-profit technical standards such as the Non-GMO Project verification standards and USDA National Bioengineered Food Disclosure Standard. These sources provided independent validation of market sizing and regulatory compliance trends.
Our simultaneous top-down (macroeconomic and industry segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption modeling) approach ensured robust market sizing. We modeled demand across product types, applications, and distribution channels, cross-validating with trade flow data and retail scan information.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |