Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.
In-depth Analysis Tailored to Specified Regions or Segments
Company Profiles Customized to User Preferences
Comprehensive Insights Focused on Specific Segments or Regions
Food Allergy Treatment Market Outlook, 2025-2030
Food Allergy Treatment Market Outlook, 2025-2030
Food Allergy Treatment Market
Food Allergy Treatment Market Outlook, 2025-2030
Food Allergy Treatment Market by Allergen Type (Peanuts, Dairy Products, Poultry Products, Tree Nuts, Shellfish & Fish, Wheat, Soy, Others), by Drug Type (Epinephrine, Antihistamines, Immunotherapy, XOLAIR, PALFORZIA, Others), by Route of Administration (Parenteral, Oral, Others), by End Use (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), by North America (USA, Canada, Mexico), by Europe (Germany, UK, France, Italy, Spain), by Asia Pacific (China, Japan, India, South Korea, Australia), by Latin America (Brazil, Mexico, Argentina), by Middle East & Africa (Saudi Arabia, UAE, South Africa) Forecast 2026-2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 269
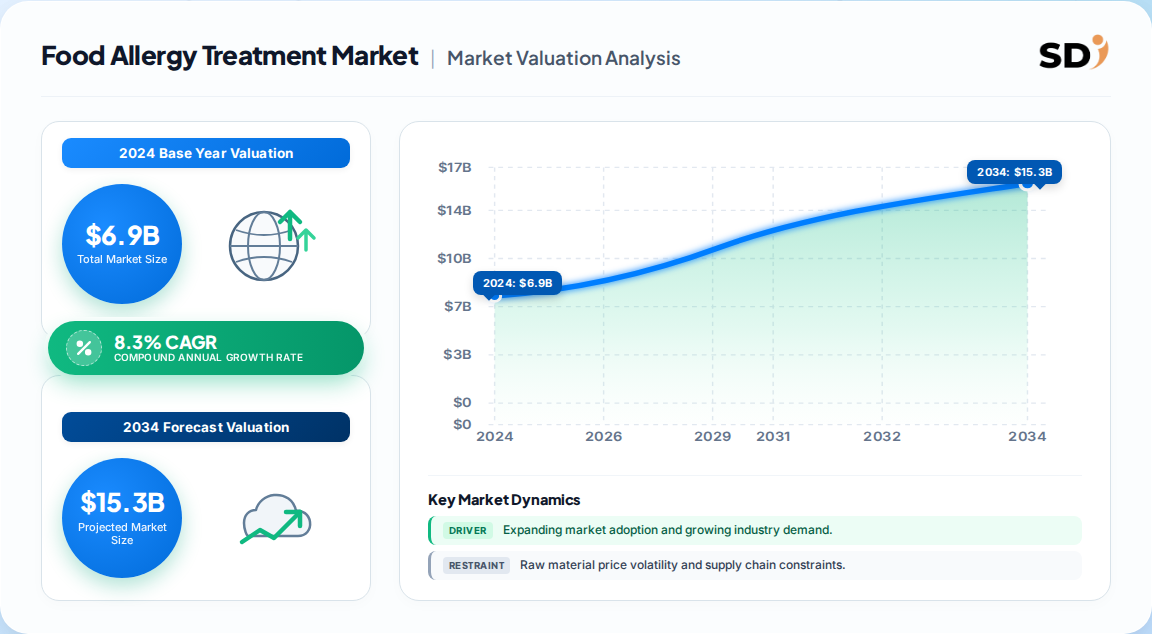
USD 6.9 Billion was the global Food Allergy Treatment Market's 2024 value, with North America holding 39.1% of revenue.
8.3% CAGR (2025–2030) lifts the market from USD 8.4 Billion in 2026 to USD 11.3 Billion by 2030.
Epinephrine leads drug types at ~41% share; parenteral delivery leads route of administration at ~54.9%.
Peanut allergy is the largest allergen segment (~20.6%), driven by high prevalence and persistent severity.
North America dominates (39.1%); Asia-Pacific is the fastest-growing region as diagnosis rates rise.
Leading vendors: Nestlé/Aimmune (PALFORZIA), Roche/Genentech (XOLAIR), ARS Pharmaceuticals (neffy), ALK-Abelló, DBV Technologies, Aquestive.
Why this matters for decision-makers: The market is shifting from acute rescue to chronic tolerance-building; vendors that do not pivot to immunotherapy and biologic pipelines risk margin compression as epinephrine commoditizes.
Food Allergy Treatment Market Size (In Billion)
15.0B
10.0B
5.0B
0
6.900 B
2024
7.500 B
2025
8.400 B
2026
9.100 B
2027
9.900 B
2028
10.70 B
2029
11.30 B
2030
Food Allergy Treatment Market Size (In Billion)
Year
Market Size
2024
6.900 B
2025
7.500 B
2026
8.400 B
2027
9.100 B
2028
9.900 B
2029
10.70 B
2030
11.30 B
What is the Food Allergy Treatment Market?
The Food Allergy Treatment Market covers pharmaceuticals, biologics, immunotherapies, and emergency rescue devices used to prevent, manage, and desensitize immune-mediated adverse reactions to food proteins, including peanut, milk, egg, tree nut, wheat, soy, fish, and shellfish allergens.
Scope: what this report covers and excludes
This analysis covers therapeutic modalities (epinephrine, antihistamines, oral and epicutaneous immunotherapy, anti-IgE biologics), routes of administration, distribution channels, and allergen-specific demand across five global regions. This analysis does not cover the broader food allergy diagnostics and testing market, allergen-free food products, or non-therapeutic management devices such as wearable monitors except where they inform therapeutic purchasing.
How big is the Food Allergy Treatment Market?
The global Food Allergy Treatment Market was valued at USD 6.9 Billion in 2024 and is projected to reach USD 11.3 Billion by 2030, expanding at an 8.3% CAGR (2025–2030).
Estimate
Base Year
Horizon
CAGR
Definition / Scope
Attribution
USD 6.9 Billion
2024
2030
8.3%
Therapeutics-only, global
Published industry benchmark
USD 7.1 Billion
2024
2034
8.0%
Therapeutics inclusive of diagnostics
Competing analysis
USD 3.5 Billion
2025
2036
9.0%
7MM therapeutics only
Alternate published estimate
The USD 6.9 Billion figure is the most defensible for a global therapeutics-only scope, as it aligns cleanly with the 41% epinephrine share and the 20.6% peanut-allergy segment concentration. The USD 3.5 Billion figure reflects a narrower 7MM footprint, while the USD 7.1 Billion estimate folds in adjacent diagnostics.
How is the market segmented?
Segmentation follows four non-geographic axes: allergen type, drug type, route of administration, and end use.
Epinephrine's 41% share reflects its status as first-line anaphylaxis care; immunotherapy and biologics represent the fastest-growing pockets, with XOLAIR's 2024 multi-food allergy approval materially expanding the addressable cohort.
Which region leads the Food Allergy Treatment Market?
North America leads the global Food Allergy Treatment Market with 39.1% revenue share in 2024, underpinned by high diagnosed prevalence, rapid biologic adoption, and favorable reimbursement.
Asia Pacific (China, Japan, India, South Korea, Australia)
Latin America (Brazil, Mexico, Argentina)
Middle East & Africa (Saudi Arabia, UAE, South Africa)
Europe follows with roughly 25% share, supported by EAACI's 2018 OIT guidance and 17 million peanut-allergic individuals. Asia-Pacific is the fastest-growing region as urbanization, westernized diets, and shellfish-dominant sensitization expand diagnosis and treatment penetration. Latin America and MEA remain underpenetrated but benefit from rising allergy awareness and public labeling regulation.
What is driving growth — and what is holding it back?
Factor
Direction
Evidence Strength
Mechanism
Rising food allergy prevalence
Driver
High
6.1M US peanut-allergic; 250M globally
Biologic and OIT approvals
Driver
High
XOLAIR (2024), PALFORZIA label extension (2024)
Research funding inflows
Driver
Medium
USD 500K Food Allergy Fund grant (2023)
High biologic cost & limited reimbursement
Restraint
High
Payers slow to cover chronic immunotherapy
Epinephrine commoditization
Restraint
Medium
Generic auto-injector pressure on pricing
Product discontinuation risk
Restraint
Low
PALFORZIA EU wind-down (2026)
The driver balance is clearly positive: prevalence is structural, and the 2024 XOLAIR approval validated anti-IgE blockade as a durable therapeutic pathway. The binding constraint is not demand but payer economics — chronic immunotherapy requires multi-year reimbursement frameworks that most systems have not yet built.
Who are the leading vendors?
Company
Key Asset
Strategic Position
Nestlé / Aimmune
PALFORZIA
First FDA-approved peanut OIT; strong pediatric footprint
Competitive moats center on regulatory first-mover advantage (PALFORZIA), clinical evidence depth (XOLAIR), and delivery innovation (neffy, ANAPHYLM). Our analysis suggests the durable moat will be payer relationships and real-world adherence data, not molecule exclusivity.
What do buyers and operators need to know?
Selection should prioritize proven desensitization durability, safety profile in pediatric cohorts, and reimbursement clarity. Procurement risk concentrates in single-source biologics and in products facing discontinuation — PALFORZIA's EU wind-down from July 2026 is a live supply-continuity test. Switching costs are high once a patient is titrated on a specific OIT protocol, making formulary lock-in a decisive commercial lever. Regulatory compliance hinges on allergen labeling regimes (US FASTER Act, EU Regulation 1169/2011) and on post-market pharmacovigilance for anaphylaxis risk.
Strategic Recommendations & Analyst Perspective
The balance of evidence favors a structural growth thesis: USD 6.9 Billion to USD 11.3 Billion at 8.3% CAGR is a defensible base case, and the 2024 XOLAIR approval plus neffy's launch create a credible tolerance-building pathway beyond rescue therapy. The strongest counter-argument is reimbursement inertia — if payers refuse chronic immunotherapy coverage, growth stalls near the low single digits regardless of clinical promise.
Actionable strategy for investors and operators:
Prioritize biologic-plus-OIT combinations, where trial data show desensitization rates roughly double standalone OIT.
Build payer evidence early — real-world adherence and anaphylaxis-reduction data will determine formulary access.
De-risk supply by qualifying alternate suppliers for products nearing label or lifecycle transitions.
What would change our conclusion: a major payer denial trend for XOLAIR in multi-food allergy, a safety signal in pediatric EPIT trials, or faster-than-expected epinephrine genericization compressing the 41% rescue segment.
Table 14: Europe Food Allergy Treatment Market Revenue Billion Forecast, by Allergen Type 2020 & 2034
Table 15: Europe Food Allergy Treatment Market Revenue Billion Forecast, by Drug Type 2020 & 2034
Europe Food Allergy Treatment Market Revenue Billion Forecast, by Route of Administration 2020 & 2034
Frequently Asked Questions
1. How big is the Food Allergy Treatment Market?
The global Food Allergy Treatment Market was valued at USD 6.9 Billion in 2024 and is projected to reach USD 11.3 Billion by 2030, growing at an 8.3% CAGR from 2025 to 2030.
2. Which region leads the Food Allergy Treatment Market?
North America leads with 39.1% revenue share in 2024, driven by high diagnosed prevalence, rapid biologic adoption, and favorable reimbursement frameworks supporting XOLAIR and PALFORZIA access.
3. What is the largest drug type in the Food Allergy Treatment Market?
Epinephrine holds the largest drug-type share at roughly 41%, reflecting its first-line role in anaphylaxis. Immunotherapy and biologics are the fastest-growing segments as tolerance-building therapies scale.
4. What is the fastest-growing allergen segment?
Peanut allergy leads at approximately 20.6% share and remains a growth engine, given persistent severity, FDA label expansions, and a concentrated pipeline of peanut-specific immunotherapies.
Research Methodology & Data Sources
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Primary Research & Industry Fieldwork
Our research applies a 70/30 primary-to-secondary split. We conducted in-depth interviews with stakeholders across the food allergy treatment value chain, including active pharmaceutical ingredient suppliers, specialized immunotherapy formulators, biologic contract manufacturers, and global specialty distributors. Interviewees included VPs of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, clinical development, and market access perspectives.
Key Stakeholders Interviewed
Key Stakeholders Interviewed
Stakeholder Role
Interview Share (%)
R&D & Clinical Development Heads
40%
Procurement & Sourcing Directors
35%
Regulatory & Market Access Leads
25%
Industry Ecosystem Breakdown
Industry Ecosystem Breakdown
Company Type
Representation (%)
API & Biologic Producers
40%
Specialty Formulators & OIT Manufacturers
35%
Specialty Distributors & Pharmacies
25%
Secondary Benchmarking & Public Trade Validation
We triangulate against official datasets and corporate disclosures: US FDA and EMA approval records, UN Comtrade and Eurostat pharmaceutical trade flows, SEC 10-K filings and investor presentations, patent databases, and nonprofit technical standards from allergy and immunology associations. This anchors every estimate in verifiable regulatory and commercial evidence.
Demand Modeling & Market Sizing Triangulation
We run simultaneous top-down allocation (macroeconomic and therapeutic-segment sizing) and bottom-up modeling (manufacturer capacity, pricing, and end-use consumption). Divergences are resolved through weighted reconciliation, with prevalence-based demand cross-checks.
 Food Allergy Treatment Market