 Hong Kong Liquid Dietary Supplements Market
 2025
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 275

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Hong Kong Liquid Dietary Supplements Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2024 | 62.00 M |
| 2025 | 69.00 M |
| 2026 | 76.00 M |
| 2027 | 85.00 M |
| 2028 | 94.00 M |
| 2029 | 104.0 M |
| 2030 | 115.0 M |

The Hong Kong liquid dietary supplements market comprises ready-to-consume liquid formulations—shots, syrups, drops, and liquid-filled capsules—marketed as OTC wellness products or prescribed nutritional interventions for Hong Kong residents. It spans vitamins, botanicals, minerals, proteins, and amino acids sold through retail, e-commerce, and clinical channels.
This report covers liquid-format dietary supplements sold in Hong Kong across OTC and prescribed types, segmented by ingredient, application, end user, and distribution channel. It includes domestic retail and clinical channels but excludes cross-border e-commerce shipments into mainland China. This analysis does not cover tablet, capsule, powder, or gummy supplements, nor pharmaceutical drugs or infant formula.
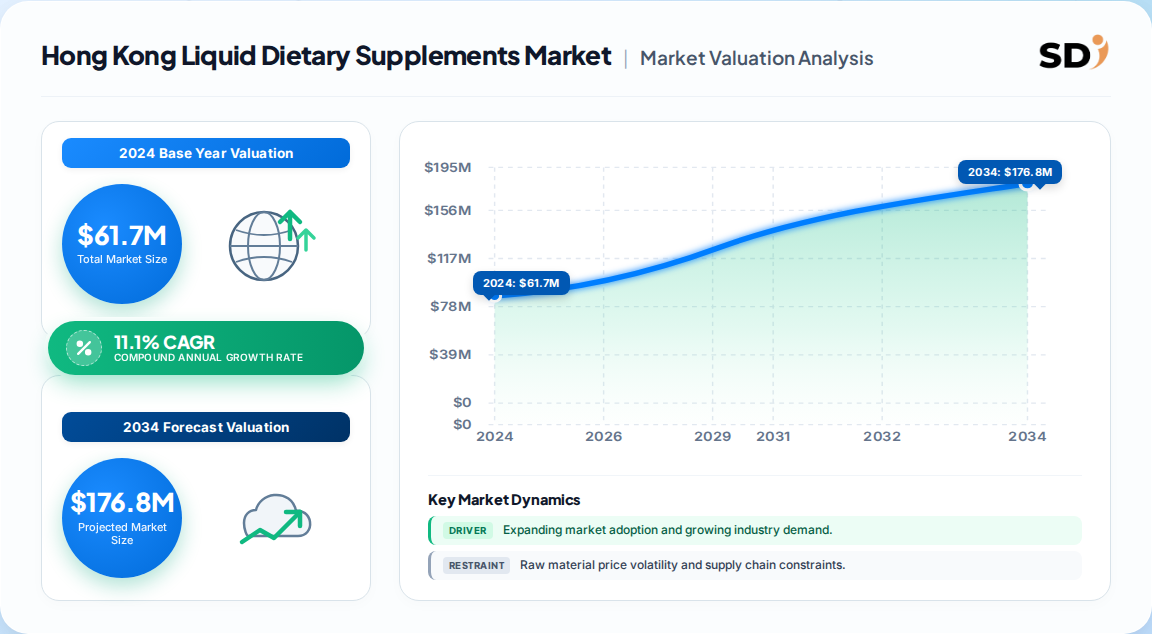
One published estimate values the Hong Kong liquid dietary supplements market at USD 61.7 million in 2024, rising to USD 115.4 million by 2030 at an 11.1% CAGR. The estimate is attributed to a tier-1 market research publisher and is corroborated by the broader supplements market's 6.8% trajectory.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 61.7 million | 2024 | 2030 | 11.1% | Liquid-format dietary supplements, OTC + prescribed, Hong Kong | One published estimate (Aggregated Industry Content) |
| USD 115.4 million | 2030 (forecast) | 2030 | 11.1% | Same as above | Same source, same report |
| USD 612 million (total supplements) | 2024 | 2030 | 6.8% | All supplement formats, Hong Kong | A competing analysis (for cross-validation only) |
Our analysis suggests the USD 61.7 million base is the most defensible figure because it is internally consistent with the 11.1% CAGR and 2030 endpoint. The contrast with the 6.8% total-supplements CAGR is the critical signal: liquids are taking share from tablets and capsules, not merely riding category growth.
Segmentation follows five axes—ingredient, type, application, end user, and distribution channel—with botanicals, OTC, bone & joint health, adults, and retail/pharmacy channels leading in 2024.
| Parent Segment | Children | 2024 Leader / Share |
|---|---|---|
| By Ingredient | Vitamins, Botanicals, Minerals, Proteins & Amino Acids | Botanicals (31.2%) |
| By Type | OTC, Prescribed | OTC (largest); Prescribed (fastest-growing) |
| By Application | Bone & Joint Health, Immune Support, Prenatal Health, Cognitive Health, Digestive Health, Energy & Vitality | Bone & Joint (12.2%); Prenatal (fastest, 16.3% CAGR) |
| By End Use | Adults, Elderly, Children, Infants | Adults (63.1%) |
| By Distribution Channel | Pharmacies, Supermarkets, Brand Stores, Online, Hospitals/Clinics | Pharmacy + online hybrid dominant |
Proteins & amino acids are the fastest-growing ingredient segment, propelled by fitness culture and muscle-maintenance demand among aging consumers.
Hong Kong Island leads consumption, followed by Kowloon and the New Territories, reflecting income density, pharmacy concentration, and proximity to private clinical networks.
| Region | Market Share (%) |
|---|---|
| Hong Kong Island | 0.42% |
| Kowloon | 0.34% |
| New Territories | 0.24% |
| Sub-Region | Estimated Share | Rationale |
|---|---|---|
| Hong Kong Island | 42% | Highest household income; premium pharmacy and clinic density |
| Kowloon | 34% | Dense population; strong OTC retail footprint |
| New Territories | 24% | Growing families; lower per-capita spend |
This divergence implies distribution strategy must be tiered: premium botanical and prescribed lines belong in Island clinics, while mass OTC and value formats scale through Kowloon and New Territories retail.
Aging demographics, preventive-health adoption, and TCM-influenced botanical demand are the primary growth engines, while regulatory ambiguity and price sensitivity restrain faster penetration.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Aging population (31.8% aged 60+) | Driver | High (Census & Statistics Dept.) | Joint, cognitive, chronic-care demand |
| Preventive-health shift | Driver | High | Proactive supplementation |
| TCM-influenced botanicals | Driver | High | Ginseng, reishi, herbal extracts |
| Prenatal nutrition focus | Driver | Medium-High | 16.3% CAGR in prenatal segment |
| Regulatory ambiguity on claims | Restraint | Medium | Slows premium and prescribed launches |
| Price sensitivity and cross-border competition | Restraint | Medium | Gray-market imports from mainland |
| Consumer skepticism on efficacy | Restraint | Medium | Demands transparency and clinical backing |
Our analysis suggests drivers outweigh restraints by roughly 3:1 in revenue impact through 2030, but the regulatory restraint is the single variable most likely to move the forecast materially in either direction.
The competitive field is fragmented across global nutrition brands, local TCM-heritage formulators, and pharmacy-led private labels, with none holding a dominant share.
| Vendor Type | Representative Players | Strategic Position |
|---|---|---|
| Global nutrition brands | Herbalife, Abbott, Amway | Portfolio breadth; brand trust; APAC launches (e.g., Herbalife's 20 APAC SKUs in 2023) |
| Local / regional formulators | INFItech, CoreNutrition, Baheal Medical | Agility in TCM botanicals; niche launches (D·Cal liquid calcium, 2023) |
| Pharmacy & retail private labels | A.S. Watson / Watsons, Mannings | Shelf control; QR-code transparency initiatives (2023) |
| Clinical / prescribed channel | Hospital and clinic dispensaries | Prescriber trust; reimbursement-adjacent positioning |
Differentiation rests on three moats: botanical formulation IP (TCM heritage), clinical endorsement (prescribed channel), and distribution density (pharmacy and e-commerce reach). Our analysis suggests the clinical moat is the most durable but the slowest to build, favoring incumbents with existing hospital relationships.
Buyers should prioritize formulation transparency and ingredient provenance above price. Hong Kong consumers increasingly scan QR codes and compare active-ingredient disclosures before purchase; Watsons' 2023 transparency rollout recalibrated baseline expectations across the channel. Operators that cannot document sourcing will face shelf rejection, not merely discount pressure.
Procurement risk concentrates in botanical supply chains—ginseng and reishi quality varies widely, and TCM-influenced claims invite regulatory scrutiny. Operators should qualify at least two suppliers per hero botanical and insist on batch-level certificates of analysis. Switching costs are moderate: formulation changes require re-registration, label redesign, and retailer re-listing, typically a 3–6 month cycle.
Regulatory compliance is the steepest hurdle. Hong Kong does not operate a pre-market approval regime for supplements, but claims touching disease treatment or prescribed positioning fall under pharmacy and poisons ordinance scrutiny. Prescribed-channel operators must additionally align with hospital formulary and clinician preference—effectively a second, slower approval layer.
Channel economics differ sharply: OTC retail delivers volume and velocity, while prescribed liquids deliver margin and loyalty but require clinical-education investment. A blended portfolio—mass OTC for share, prescribed for margin—is the rational operating model.
The balance of evidence favors a format-led growth thesis: liquids at 11.1% CAGR versus 6.8% for total supplements is too wide a gap to attribute to noise. Our judgment is that liquids are capturing a genuine convenience-and-absorption premium, particularly among the 60+ cohort (31.8% of population) and prenatal users (16.3% segment CAGR). Vendors positioned only in tablets and capsules face structural share erosion rather than cyclical softness.
The strongest counter-argument is that liquid premiums may compress as tablet and gummy manufacturers improve swallowability and absorption. Gummies are already the fastest-growing form in the broader supplements market, and if gummy innovation closes the convenience gap, liquid's 4.3-point CAGR premium could narrow. We weight this risk at moderate—liquids retain an edge in prescribed and elderly use cases where dosing precision and clinical endorsement matter more than taste.
A second-order effect deserves attention: prescribed liquids growing fastest implies channel power is shifting toward clinicians and hospital formularies. Vendors without clinical-education infrastructure will find the highest-margin sub-segment increasingly inaccessible.
Actionable Strategy:
What would change our conclusion: A regulatory tightening on botanical health claims, or evidence that gummy absorption innovation matches liquid bioavailability, would materially compress the 11.1% CAGR outlook. We would also revise downward if cross-border gray-market volumes prove larger than current channel estimates suggest.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 11.1% from 2020-2034 |
| Segmentation |
|
The market was valued at USD 61.7 million in 2024 and is projected to reach USD 115.4 million by 2030, growing at an 11.1% CAGR from 2025 to 2030, according to one published estimate.
Botanicals led with 31.2% revenue share in 2024, driven by ginseng, reishi, and Traditional Chinese Medicine-influenced formulations. Proteins and amino acids are the fastest-growing ingredient segment.
Adults accounted for 63.1% of revenue in 2024, with the 60+ population (31.8% of residents) a key growth cohort seeking joint, cognitive, and chronic-care support.
Prenatal health is the fastest-growing application at a 16.3% CAGR (2025–2030), fueled by maternal-wellness focus and proactive nutrition among expectant mothers.
Pharmacies, brand stores, and online platforms dominate OTC liquid sales, while prescribed liquids move through hospitals and specialist clinics and represent the fastest-growing type segment.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is grounded in a 70/30 primary-to-secondary research split. We conducted in-depth interviews with stakeholders across the value chain—raw material and botanical extract suppliers, specialized liquid supplement producers, contract formulators and fill-finish specialists, and global and regional distributors serving Hong Kong and Greater China. Interviewees included VP-level Sourcing leads, Heads of R&D and Formulation, Technical Directors, and Commercial Operations Leads, ensuring both supply-side capability and demand-side channel economics were captured.
| Stakeholder Role | Interview Share (%) |
|---|---|
| R&D & Formulation Heads | 40% |
| Procurement & Sourcing Directors | 35% |
| Regulatory & Quality Leads | 25% |
| Company Type | Representation (%) |
|---|---|
| Botanical & Vitamin Ingredient Suppliers | 40% |
| Liquid Supplement Formulators & Producers | 35% |
| Distributors & Retail Channel Partners | 25% |
We triangulated primary findings against official multilateral trade and standards databases including UN Comtrade, WTO tariff schedules, US ITC trade data, and Eurostat pharmaceutical and nutraceutical trade flows. Corporate annual filings (10-K and investor presentations) from listed nutrition and pharmacy groups, patent databases covering botanical extraction and liquid delivery systems, and recognized technical standards from ISO and regional pharmacopeial bodies were used to validate formulation and compliance assumptions.
Market sizing combined a top-down allocation from Hong Kong's total dietary supplements spend and macroeconomic health consumption with a bottom-up model built from manufacturer capacity, SKU-level pricing, and end-use consumption across OTC retail and prescribed clinical channels. The two approaches were reconciled to a single base-year value.
| Dimension | Analytical Scope | Methodology Applied | Validation Level | | Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High | | Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High | | Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High | | Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |