 Food Safety Testing Market
 Size, Trends & 2035 Forecast
Updated On : Nov 22, 2026|Base Year : 2025|Pages : 266

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Food Safety Testing Market
Sakshi Gurunule
Research Associate

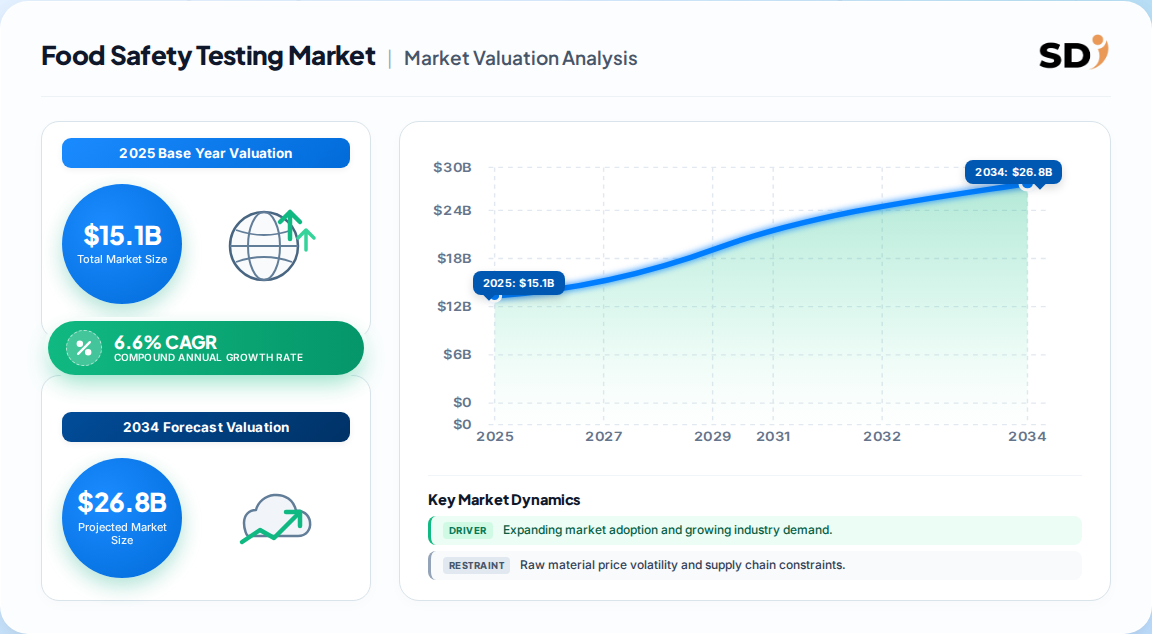
| Year | Market Size |
|---|---|
| 2025 | 15.10 B |
| 2026 | 16.10 B |
| 2027 | 17.20 B |
| 2028 | 18.30 B |
| 2029 | 19.50 B |
| 2030 | 20.80 B |
| 2031 | 22.20 B |

The food safety testing market encompasses analytical services, rapid diagnostic kits, reagents, molecular platforms, and instruments used to detect pathogens, allergens, chemical residues, and contaminants across the food supply chain. It serves primary production, processing, import control, retail, and food service, driven by regulatory compliance, traceability obligations, and brand protection.
This report covers global food safety testing demand across laboratory services, rapid in-house screening, molecular diagnostics, and analytical instrumentation from primary production through retail. It includes pathogen, allergen, chemical, GMO, and residue testing across meat, poultry, seafood, dairy, processed food, beverages, and cereals. This analysis does not cover agricultural pesticide registration, pharmaceutical residue regulation, or environmental water testing adjacent to food production.
Estimates for the global food safety testing market vary widely in scope and methodology, ranging from a 2025 valuation of 15.1 Billion to a 2033 forecast of 48.01 Billion. The following table compares published projections.
| Estimate | Base year | Horizon | CAGR | Definition / scope | Attribution |
|---|---|---|---|---|---|
| 15.1 Billion | 2025 | 2035 | 6.6% | Global outsourced lab services, kits, reagents, molecular platforms, instruments | One published estimate |
| 48.01 Billion | 2025 | 2033 | 7.8% | Global testing services and products, all test types | Competing analysis |
| 8.28 Billion | 2026 | 2031 | 4.68% | North America only, containment/technology/application | Regional specialist estimate |
Our analysis suggests the 15.1 Billion baseline is the most defensible global figure because it aligns with a test-volume anchor of approximately 163 million tests at a blended average selling price of USD 92.6. The 48.01 Billion projection implies a materially higher revenue per test or a broader scope that includes adjacent analytical services. The divergence between the 6.6% and 7.8% CAGRs likely reflects different assumptions about molecular-method adoption and emerging-market accreditation build-out. Buyers should treat the narrower scope as the more conservative planning base.
Segmentation follows testing type, application, and technology, with pathogen testing and microbiological methods anchoring revenue. The table below summarizes non-geographic segments.
| Parent segment | Children |
|---|---|
| By Testing Type | Pathogen, Pesticide & Residue, Mycotoxin, GMO, Allergen, Chemical & Nutritional, Others |
| By Application | Meat, Poultry & Seafood, Dairy, Processed Food, Beverages, Cereals & Grains, Pet Food & Animal Feed, Others |
| By Technology | Traditional, Rapid, PCR, Immunoassay, Chromatography & Spectrometry, Convenience-Based |
| By Containment | Pathogen, Pesticide & Residue, Mycotoxin, GMO, Allergen, Other |
Microbiological testing led the global market with 28.9% revenue share in 2025, while traditional methods still held 55.3% due to regulatory acceptance. However, PCR platforms captured 45.3% of North American technology revenue, signaling a gradual displacement of culture-based workflows. Our analysis suggests the coexistence of traditional and molecular methods creates a dual-pricing structure that sustains blended average selling prices.
Europe leads the global food safety testing market with approximately 34% revenue share in 2025, followed closely by North America at 28% and Asia Pacific at 28%. The geography tree below shows the regional structure.
| Region | Market Share (%) |
|---|---|
| North America | 0.28% |
| Europe | 0.3% |
| Asia-Pacific | 0.28% |
| South America | 0.07% |
| Middle East & Africa | 0.07% |
Europe's leadership stems from stringent EU regulations and comprehensive food safety policies, including the 2024/2895 Listeria controls effective July 2026. North America's 28% share is anchored by the US at 75.1% of regional revenue, with Mexico growing fastest at 6.21% CAGR. Asia Pacific's 28% share is the fastest-growing, driven by food processing expansion in India and China. Our analysis suggests Asia Pacific could overtake North America by the early 2030s if accreditation capacity expands as projected.
Growth is driven by structural foodborne disease burden, trade expansion, and tightening molecular confirmation requirements, while accreditation shortages and protocol disharmony restrain emerging-market conversion. The table below summarizes key factors.
| Factor | Direction | Evidence strength | Mechanism |
|---|---|---|---|
| Foodborne disease burden (866M cases annually) | Driver | High | Recurring pathogen and chemical testing across all food categories |
| Agrifood trade expansion | Driver | High | Cross-border screening, HACCP verification, authenticity testing |
| EU 2024/2895 Listeria controls | Driver | High | Validated shelf-life and challenge testing by accredited labs |
| Molecular method adoption | Driver | Medium | Higher revenue per test, instrument and consumable growth |
| Accreditation shortage in Africa (~30% labs accredited) | Restraint | High | Constrains third-party throughput in high-growth regions |
| Protocol disharmony (EAC loses >USD 700M annually) | Restraint | Medium | Duplicated compliance testing, trade friction |
The balance of evidence favors sustained above-GDP growth, but the restraint side is non-trivial. Our analysis suggests the accreditation gap is the single largest suppressor of emerging-market revenue, creating a multi-year lag between food production growth and testing revenue capture. Vendors that invest in accredited lab partnerships in Africa and Southeast Asia could unlock underserved demand ahead of competitors.
The competitive landscape is moderately concentrated, with the top five players holding 32.2% share in 2025 and Eurofins Scientific leading at over 15.2%. The table below compares key vendors.
| Company | Estimated share | Strategic positioning |
|---|---|---|
| Eurofins Scientific | >15.2% | Broadest accredited lab network, molecular menu depth |
| Mérieux NutriSciences | Top 5 | Strong in pathogen and allergen testing, global lab footprint |
| Neogen Corporation | Top 5 | Rapid diagnostic kits, food safety consumables |
| SGS SA | Top 5 | Inspection and certification integration, trade documentation |
| bioMérieux | Top 5 | Molecular diagnostics, instrument and reagent platforms |
Differentiation rests on accreditation breadth, assay menu depth, and turnaround time. Eurofins' scale advantage in accredited laboratories creates a moat in multi-market documentation, while Neogen and bioMérieux compete on kit and instrument economics. Our analysis suggests the top five will consolidate share as automation investments favor larger participants facing laboratory labor shortages.
Buyers selecting food safety testing partners should prioritize ISO/IEC 17025 accreditation, assay menu breadth, and turnaround time for perishable products. Procurement risks include protocol disharmony across trade corridors, which can duplicate compliance testing and add cost. Switching costs are moderate for laboratory services but high for instrument platforms due to reagent lock-in and staff training. Regulatory compliance is non-negotiable: EU 2024/2895, FDA's Food Traceability Rule (July 2028), and USDA-FSIS sampling plans set the verification bar. Operators should embed testing into production workflows rather than rely on finished-product sampling, and should seek laboratories capable of supporting multi-market documentation. The key procurement insight is that the lowest price per test often masks higher total cost from retesting, delayed release, and trade rejection.
The balance of evidence favors a sustained 6.6-7.8% CAGR through the early 2030s, with the 15.1 Billion baseline as the most defensible planning anchor. The strongest counter-argument is that the 48.01 Billion projection reflects a broader scope that includes adjacent analytical services and could materialize if molecular adoption accelerates faster than expected. However, the test-volume and average-selling-price evidence supports the more conservative view.
Our analysis suggests the most important strategic implication is the migration from culture-based to molecular confirmation, which raises revenue per test and favors vendors with broad assay menus and strong quality systems. The accreditation shortage in Africa and parts of Asia Pacific represents both a restraint and an opportunity: vendors that build accredited capacity early will capture underserved demand as trade corridors formalize.
Actionable Strategy:
Evidence that would change our conclusion: a faster-than-expected expansion of ISO/IEC 17025 accreditation in Africa and Asia Pacific, or a regulatory mandate for whole-genome sequencing in routine pathogen testing, would support the higher 7.8% CAGR scenario.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 6.6% from 2020-2034 |
| Segmentation |
|
The global food safety testing market was valued at 15.1 Billion in 2025, with approximately 163 million tests conducted worldwide. It is projected to reach 16.1 Billion in 2026 and 28.6 Billion by 2035 at a 6.6% CAGR.
Europe leads with approximately 34% revenue share in 2025, driven by stringent EU regulations. North America and Asia Pacific follow at roughly 28% each, with Asia Pacific growing fastest due to food processing expansion.
The primary drivers are the persistent global foodborne disease burden (866 million cases annually), agrifood trade expansion requiring cross-border screening, and tightening regulatory frameworks like EU 2024/2895 mandating validated molecular confirmation.
Eurofins Scientific leads with over 15.2% market share. The top five players — Eurofins, Mérieux NutriSciences, Neogen, SGS, and bioMérieux — collectively held 32.2% of the market in 2025.
PCR and molecular platforms are growing fastest, capturing 45.3% of North American technology revenue. GMO testing recorded the fastest containment-type CAGR at 5.25% through 2031, while chromatography and spectrometry grew at 6.12%.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our research methodology applies a 70/30 primary-to-secondary split, with in-depth interviews conducted across the food safety testing value chain. We engaged with accredited laboratory operators, rapid diagnostic kit manufacturers, molecular platform providers, third-party inspection and certification bodies, and food processor procurement teams. Decision-maker designations interviewed included VP of Sourcing, Heads of R&D, Technical Directors, Quality Assurance Directors, and Commercial Operations Leads. This fieldwork captured granular data on test volumes, pricing dynamics, accreditation capacity, and method migration patterns.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Technical & Quality Directors | 35% |
| Procurement & Sourcing Leads | 30% |
| Regulatory Affairs Managers | 20% |
| Commercial Operations Leads | 15% |
| Company Type | Representation (%) |
|---|---|
| Accredited Laboratory Operators | 40% |
| Rapid Diagnostic Kit Manufacturers | 25% |
| Molecular Platform Providers | 20% |
| Food Processor Procurement Teams | 15% |
We validated findings against official multilateral trade and standards databases, including UN Comtrade, WTO SPS notifications, US ITC trade data, and Eurostat food safety statistics. Corporate annual filings (10-K, SEC filings, investor presentations) from publicly listed testing companies informed capacity and revenue benchmarks. Patent databases and recognized industry associations, including ISO/IEC 17025 accreditation bodies and GFSI-recognized certification schemes, provided standards validation.
We applied simultaneous top-down macroeconomic and industry segment allocation alongside bottom-up manufacturer capacity, product pricing, and end-use consumption modeling. This triangulation reconciled test-volume anchors with average selling prices to produce a defensible revenue baseline and forecast trajectory.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |