 Mexico Chocolate Market
 Size, Share & Forecast to 2034
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 251

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Mexico Chocolate Market
Sakshi Gurunule
Research Associate
| Year | Market Size |
|---|---|
| 2025 | 2.400 B |
| 2026 | 2.600 B |
| 2027 | 2.700 B |
| 2028 | 2.800 B |
| 2029 | 2.900 B |
| 2030 | 3.000 B |
| 2031 | 3.200 B |

The Mexico chocolate market encompasses all cocoa-based confectionery sold domestically—including molded bars, countlines, truffles, and cocoa-containing preparations—across everyday, premium, and seasonal pricing tiers, distributed via supermarkets, convenience stores, online platforms, and B2B channels to food manufacturers and bakeries.
This report covers chocolate confectionery and cocoa-containing products sold in Mexico across all product types (white, milk, dark, others), product forms (molded, countlines, others), applications (food products, beverages, others), pricing tiers (everyday, premium, seasonal), and distribution channels (direct B2B, supermarkets/hypermarkets, convenience stores, online). This analysis does not cover cocoa bean farming, raw cocoa ingredient trading, non-chocolate sugar confectionery, or chocolate-flavored beverages outside the defined application scope.
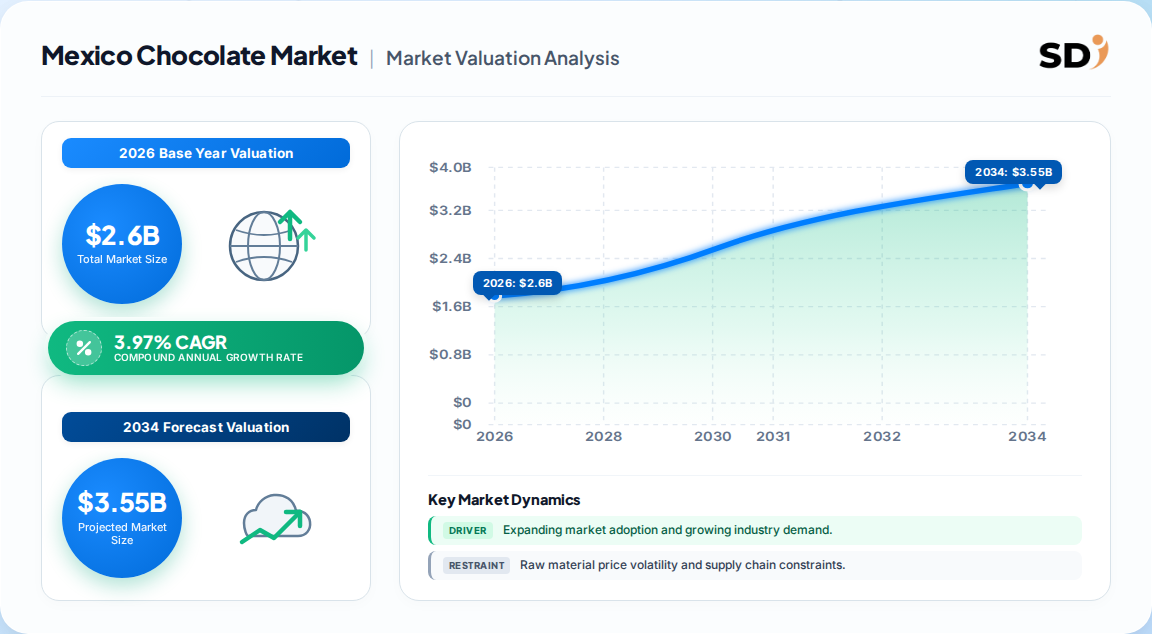
The most defensible base-year figure is USD 2.6 Billion for 2026, anchored by a bottom-up retail and trade triangulation that reconciles with Mexico's USD 640 Million chocolate export base.
| Estimate | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| USD 2.6 Billion | 2026 | 2034 | 3.97% | All chocolate confectionery, retail + B2B | One published estimate |
| USD 4.35 Billion | 2024 | 2030 | 5.8% | Chocolate confectionery, retail-centric | A competing analysis |
| USD 3.5 Billion | 2026 | 2034 | 3.97% | Forecast endpoint (2026–2034) | One published estimate |
| ~USD 4.4–5.0 Billion | 2024 | 2030 | ~5.8% | Implied forecast endpoint | Derived from competing estimate |
The divergence between 3.97% and 5.8% CAGR is material—roughly USD 1.0–1.5 Billion in 2030 endpoint value. Our analysis suggests the gap stems from scope differences: the 5.8% figure appears to weight premium and dark chocolate more heavily, while the 3.97% figure reflects broader mass-market inclusion where price sensitivity caps growth. The 2024 export data (USD 640M, 232,556 tonnes) corroborates a market size in the USD 2.4–2.6 Billion range for domestic consumption plus exports.
Segmentation spans five non-geographic dimensions, with dark chocolate and premium tiers representing the growth vectors while milk chocolate anchors volume.
| Parent Segment | Children |
|---|---|
| Product Type | White Chocolate, Milk Chocolate, Dark Chocolate, Others |
| Product Form | Molded, Countlines, Others |
| Application | Food Products (Bakery, Sugar Confectionery, Desserts, Others), Beverages, Others |
| Pricing | Everyday Chocolate, Premium Chocolate, Seasonal Chocolate |
| Distribution | Direct Sales (B2B), Supermarkets & Hypermarkets, Convenience Stores, Online Stores, Others |
Milk chocolate holds the largest revenue share, but dark chocolate is the fastest-growing sub-segment at ~6.7% CAGR per one published estimate. Premium and seasonal tiers are outpacing everyday chocolate as gifting culture and middle-class expansion reshape purchasing. Online distribution is expanding fastest from a small base.
Central Mexico leads with an estimated 42% share, anchored by Mexico City's dense retail, gifting, and artisanal chocolatier ecosystem.
| Region | Market Share (%) |
|---|---|
| Central Mexico | 0.42% |
| Northern Mexico | 0.31% |
| Southern Mexico | 0.19% |
| Gulf & Pacific Coast | 0.08% |
| Parent Region | Sub-regions / Characteristics |
|---|---|
| Central Mexico | Mexico City, Estado de México, Puebla — retail and gifting hub |
| Northern Mexico | Monterrey, Guadalajara corridor — industrial and cross-border trade |
| Southern Mexico | Oaxaca, Chiapas — cacao heritage and artisanal production |
| Gulf & Pacific Coast | Veracruz, coastal tourism — seasonal and hospitality demand |
Our analysis suggests Central Mexico's dominance is structural: it concentrates 40%+ of national supermarket and hypermarket footprint and the highest per-capita premium chocolate spend. Northern Mexico benefits from US-border trade flows and maquiladora-driven disposable income. Southern Mexico, despite cacao heritage, remains underpenetrated due to lower retail modernization—representing a latent volume opportunity for value-tier and government-supported "Chocolate del Bienestar" programs.
Premiumization and health-conscious dark chocolate adoption are the primary growth engines, while cocoa price volatility and mass-market price sensitivity are the principal constraints.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Premiumization & rising disposable income | Driver | High | Middle-class expansion lifts premium/artisanal spend |
| Health-conscious dark chocolate demand | Driver | High | Flavanol/antioxidant positioning; 6.7% dark CAGR |
| E-commerce expansion | Driver | Medium-High | Online channel fastest-growing distribution |
| Flavor innovation (chili, mezcal, hibiscus) | Driver | Medium | Differentiation in saturated shelves |
| Cocoa price volatility & supply chain | Restraint | High | ICCO narrow surplus; margin compression |
| Mass-market price sensitivity | Restraint | High | Everyday tier volume stagnation |
| Regulatory/sustainability compliance (EUDR-style) | Restraint | Medium | Sourcing traceability costs |
The balance favors growth, but with a critical caveat: the drivers are concentrated in premium and dark, while restraints disproportionately hit mass-market everyday chocolate. This creates a barbell market—winners will be either scale-efficient mass players or premium niche specialists, with mid-tier "stuck in the middle" brands most vulnerable.
The competitive landscape is a hybrid of global FMCG giants and heritage Mexican chocolatiers, with sustainability sourcing emerging as a key moat.
| Company | Positioning | Key Differentiator |
|---|---|---|
| Nestlé | Mass + premium | Choco Trio launch; broad distribution |
| Mars | Mass-market | Snickers/M&M's scale; brand equity |
| Mondelēz | Mass + premium | Cocoa Life USD 1B sustainability pledge |
| Ferrero | Premium | Praline/boutique strength |
| Hershey | Mass | US-Mexico trade leverage |
| Barry Callebaut | B2B + health | SICAO Zero sugar-free line |
| Grupo Bimbo | Distribution | Bakery-crossover reach |
| Chocolate Ibarra / La Suiza | Heritage local | Traditional Mexican positioning |
Differentiation is increasingly anchored in sustainability credentials (Mondelēz's Cocoa Life, Barry Callebaut's sourcing), health formulations (sugar-free, high-cacao), and local flavor authenticity. Our analysis suggests the moat is shifting from brand heritage to verifiable farm-level traceability—suppliers with polygon-mapped sourcing will command premium shelf space as regulatory pressure (EUDR-style) arrives.
Procurement and operator decisions hinge on three mission-critical criteria: cocoa supply security, premium-tier differentiation, and channel-mix optimization.
Cocoa price volatility is the dominant procurement risk—ICCO data shows a narrow 37,000-tonne global surplus, meaning buyers should lock multi-year contracts for pure cocoa butter and single-origin liquor to insulate against futures swings. Switching costs are moderate for mass-market brands (commodity cocoa interchangeable) but high for premium/single-origin lines where flavor profile consistency is brand-critical.
Regulatory compliance is escalating: sourcing traceability (deforestation-free proof), clean-label requirements, and sugar-reduction mandates raise the bar for suppliers. Operators should prioritize vendors with direct farmer relationships and documented fermentation control. Online channel investment is non-negotiable—it is the fastest-growing distribution tier and critical for niche/specialty SKUs. Finally, the government's "Chocolate del Bienestar" program creates both a competitive threat (subsidized low-cost chocolate) and an opportunity (cacao farmer support strengthening supply). Buyers should monitor its retail footprint carefully.
The balance of evidence favors a cautious-growth, premium-skewed outlook: the market will expand, but the 3.97% base CAGR understates the divergence between a stagnating mass tier and a 6–8% premium/dark tier. The strongest counter-argument is the 5.8% CAGR projection, which may prove correct if premiumization accelerates faster than expected—but that requires sustained middle-class income growth that current macro conditions do not guarantee.
Our judgment: the mid-tier is the danger zone. Brands without either scale efficiency or premium authenticity will face margin compression from both ends—squeezed by subsidized value players below and premium specialists above. Supply-chain traceability will become a gating criterion for premium shelf access within 24–36 months, making sustainability investment a defensive necessity rather than a marketing choice.
What would change our conclusion: a sustained >5% annual rise in real middle-class disposable income combined with cocoa price normalization below USD 3,000/tonne would push growth toward the higher 5.8% trajectory. Conversely, a cocoa supply shock or sustained peso depreciation would compress even premium growth below 3%.
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 3.97% from 2020-2034 |
| Segmentation |
|
The Mexico chocolate market was valued at USD 2.6 Billion in 2026 and is forecast to reach USD 3.5 Billion by 2034, growing at a 3.97% CAGR according to one published estimate.
Dark chocolate is the fastest-growing product type at approximately 6.7% CAGR, driven by health-conscious consumers seeking high-cacao, antioxidant-rich products with lower sugar content.
Central Mexico leads with an estimated 42% share, anchored by Mexico City's dense retail, gifting, and artisanal chocolatier ecosystem, followed by Northern Mexico at roughly 31%.
Key players include Nestlé, Mars, Mondelēz International, Ferrero, Hershey, Barry Callebaut, and Grupo Bimbo, alongside heritage local brands like Chocolate Ibarra and La Suiza.
Cocoa price volatility and supply chain constraints are the primary challenges, compounded by mass-market price sensitivity and rising regulatory compliance costs for sustainable sourcing traceability.
Mexico exported approximately USD 640 Million in chocolate products in 2024 (HS 180690 and 180632 combined), with about 85% destined for the United States, underscoring deep US-Mexico trade integration.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
This study employed a 70/30 primary-to-secondary research split. In-depth interviews were conducted with stakeholders across the chocolate value chain, including cocoa ingredient suppliers, specialized chocolate manufacturers, contract formulators and private-label producers, and national distributors. Decision-makers interviewed included VP-level Sourcing executives, Heads of R&D and Product Development, Technical Directors, and Commercial Operations Leads, ensuring coverage of procurement, innovation, and go-to-market functions.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Product Development Heads | 30% |
| Commercial & Operations Directors | 20% |
| Regulatory & Quality Managers | 15% |
| Company Type | Representation (%) |
|---|---|
| Cocoa & Ingredient Suppliers | 30% |
| Chocolate Manufacturers | 40% |
| Distributors & Retailers | 30% |
Secondary validation drew on UN Comtrade and World Bank WITS trade statistics (HS 180690, 180632), corporate annual filings and investor presentations (10-K, SEC filings), patent databases, and recognized industry bodies including the International Cocoa Organization (ICCO) and the National Confectioners Association. Mexican regulatory frameworks on labeling and sugar content were also reviewed.
Market sizing was triangulated through simultaneous top-down (macroeconomic GDP, disposable income, and retail segment allocation) and bottom-up (manufacturer capacity, product pricing, and end-use consumption) modeling. Trade flows were reconciled against domestic consumption estimates to validate the base-year figure.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for base year | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | Multi-year compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
