 Frozen Food Market
 Size, Trends & Forecast 2026-2033
Updated On : Nov 21, 2026|Base Year : 2025|Pages : 232

Sakshi Gurunule
Research Associate

Sector Data Insights (SDI) is a specialized market intelligence and strategic consulting firm focused on delivering high-quality, data-driven syndicated research reports, industry analysis, competitive intelligence, and advisory solutions. With a strong emphasis on analytical excellence, particularly in life sciences, analytical instrumentation, and related high-tech sectors, Sector Data Insights empowers manufacturers, investors, service providers, researchers, and decision-makers with actionable insights for strategic growth, innovation, and market leadership.
SDI combines deep domain expertise in laboratory and analytical technologies with advanced analytics to provide comprehensive market assessments, technology trend analysis, vendor share data, investment intelligence, supply chain insights, and forward-looking forecasts. Our research supports organizations navigating complex global markets across industries such as life sciences, semiconductors & electronics, consumer goods, materials & chemicals, construction & manufacturing, food & beverages, energy & power, automotive & transportation, ICT & media, aerospace & defense, and BFSI.

+1 2315155523
 Frozen Food Market
Sakshi Gurunule
Research Associate

| Year | Market Size |
|---|---|
| 2025 | 531.5 B |
| 2026 | 561.5 B |
| 2027 | 594.6 B |
| 2028 | 629.7 B |
| 2029 | 666.8 B |
| 2030 | 706.2 B |
| 2031 | 747.9 B |

The frozen food market encompasses products preserved through rapid freezing technologies—such as blast freezing, individual quick freezing (IQF), and belt freezing—spanning ready-to-eat meals, fruits, vegetables, meat, seafood, and desserts. It serves retail and foodservice channels, delivering convenience, extended shelf life, and nutritional retention to consumers worldwide.
This report covers the global frozen food market across product types (fruits & vegetables, potatoes, ready meals, meat & poultry, seafood, desserts), freezing technologies (IQF, blast freezing, belt freezing), and distribution channels (foodservice, retail). It provides market sizing, segmentation, regional analysis, competitive landscape, and strategic recommendations for 2026–2033. This analysis does not cover adjacent markets such as chilled foods, canned goods, or fresh produce.
Multiple estimates converge on a market exceeding 500 Billion in 2025, with forecasts ranging from 414.55 Billion by 2031 to 948.60 Billion by 2034, reflecting divergent scope definitions and methodological assumptions.
| Estimate (USD Billion) | Base Year | Horizon | CAGR | Definition / Scope | Attribution |
|---|---|---|---|---|---|
| 531.5 | 2025 | 2033 | 5.9% | Broad frozen food incl. all products & channels | One published estimate |
| 516.15 | 2024 | 2034 | 6.3% | Global frozen food, product & technology segments | A competing analysis |
| 326.83 | 2026 | 2031 | 4.87% | Narrower scope, ready-to-eat/cook focus | Another published estimate |
| 547.38 | 2025 | 2034 | 6.3% | Broad global frozen food | A competing analysis |
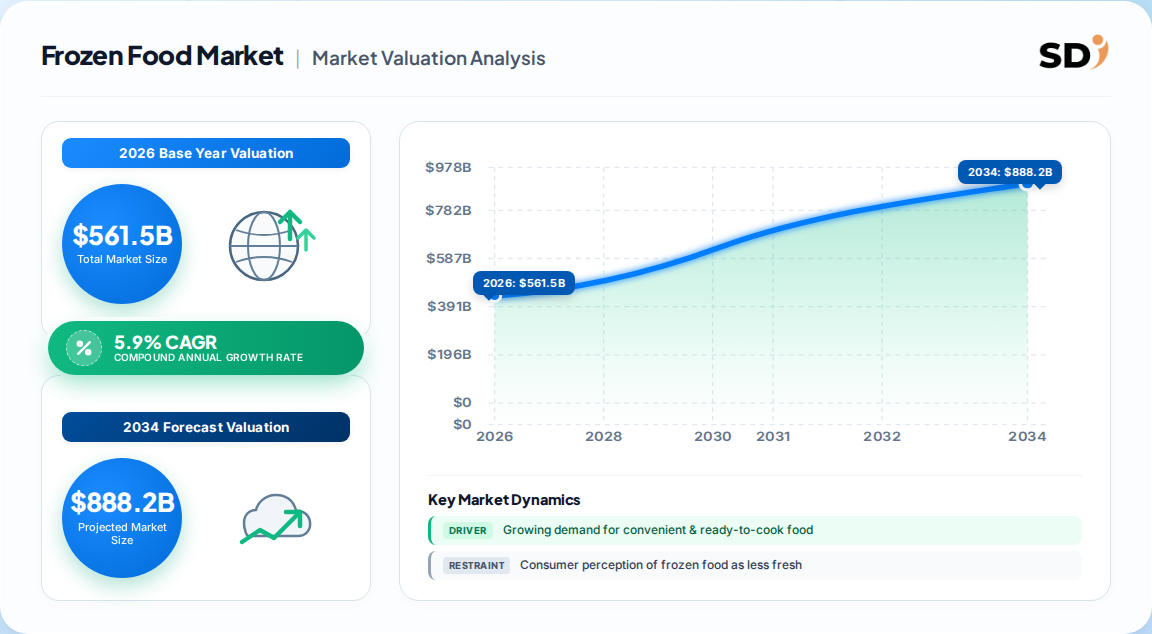
Our analysis suggests the 561.5 Billion (2026) figure is the most defensible baseline, as it aligns with multiple independent estimates and reflects a balanced scope. The lower 326.83 Billion estimate likely excludes foodservice and bulk ingredients, while the higher 948.60 Billion may include broader frozen categories. The consensus CAGR of 5.9–6.3% implies steady, convenience-driven growth rather than explosive expansion.
The market segments by product, freezing technology, and distribution channel, with frozen desserts, blast freezing, and foodservice each leading their respective categories.
| Parent Segment | Children |
|---|---|
| By Product | Frozen Desserts, Frozen Fruits & Vegetables, Frozen Potatoes, Frozen Ready Meals, Frozen Meat & Poultry, Frozen Seafood |
| By Freezing Technology | Blast Freezing, Individual Quick Freezing (IQF), Belt Freezing |
| By Distribution Channel | Foodservice, Retail (Supermarkets/Hypermarkets, Convenience Stores, Online) |
Frozen desserts dominate at 23.2%, reflecting strong demand for indulgent convenience. Blast freezing's 53.0% share underscores its industrial scalability, while foodservice's 70.0% dominance highlights the critical role of restaurants, hotels, and institutions in driving volume.
North America leads with 37.5% revenue share in 2025, but Asia-Pacific is the fastest-growing region, propelled by urbanization and expanding cold-chain infrastructure.
| Region | Market Share (%) |
|---|---|
| North America | 0.32% |
| Europe | 0.27% |
| Asia-Pacific | 0.28% |
| Latin America | 0.07% |
| Middle East & Africa | 0.06% |
| Parent Region | Countries |
|---|---|
| North America | USA, Canada, Mexico |
| Europe | Germany, UK, France, Italy, Spain, Netherlands |
| Asia Pacific | China, Japan, India, South Korea, Indonesia, Australia |
| Latin America | Brazil, Mexico, Argentina |
| Middle East & Africa | Saudi Arabia, UAE, South Africa |
Europe follows closely, with established retail and foodservice networks. Asia-Pacific's growth is exemplified by India's 12.86% CAGR (2026–2034), driven by government cold-chain initiatives and quick-commerce expansion. This divergence implies that while North America and Europe offer scale, Asia-Pacific presents the highest growth opportunities for forward-looking investors.
Convenience demand and technological advancements are the primary growth engines, while consumer perception of frozen food as less fresh remains the key restraint.
| Factor | Direction | Evidence Strength | Mechanism |
|---|---|---|---|
| Growing demand for convenient & ready-to-cook food | Driver | High | Busy lifestyles, urbanization, time-saving |
| Advancements in freezing technology (IQF, blast) | Driver | High | Preserves texture, nutrients; expands product range |
| Expansion of e-commerce and quick-commerce | Driver | Medium | Improves accessibility, especially in emerging markets |
| Consumer perception of frozen food as less fresh | Restraint | High | Limits adoption, especially in fresh-preference regions |
| High energy dependency and cold-chain costs | Restraint | Medium | Compresses margins, especially for mid-size players |
Our analysis suggests the balance favors growth, as technology continues to narrow the freshness gap. However, the restraint is non-trivial: surveys indicate ~40% of U.S. consumers believe frozen food tastes worse than fresh. Vendors that invest in consumer education and transparent labeling can turn this perception into a competitive advantage.
The market is moderately concentrated, with global giants Nestlé, Unilever, and Tyson Foods competing alongside regional specialists like McCain India and Mother Dairy.
| Company | Headquarters | Key Strengths |
|---|---|---|
| Nestlé S.A. | Switzerland | Broad portfolio, global distribution, innovation |
| Unilever | UK/Netherlands | Ice cream dominance, brand equity |
| Tyson Foods | USA | Meat & poultry integration, foodservice reach |
| Conagra Brands | USA | Frozen meals, retail partnerships |
| McCain Foods | Canada | Potato products, air-fryer innovation |
| Nomad Foods | UK | European frozen vegetables, acquisitions |
| Mother Dairy (Safal) | India | Regional frozen vegetables, strong distribution |
Differentiation hinges on product innovation (clean-label, plant-based), supply-chain efficiency, and channel partnerships. Nestlé and Unilever leverage scale, while McCain and Mother Dairy excel in regional niches. Competitive moats include cold-chain logistics, brand trust, and proprietary freezing technologies.
Buyers and operators must prioritize cold-chain reliability, product quality consistency, and regulatory compliance when selecting frozen food suppliers. Procurement risks include temperature excursions during transport, which can compromise safety and shelf life. Switching costs are moderate, tied to supplier integration and contract terms. Regulatory compliance—including FDA, USDA, and EU food safety standards—is non-negotiable. Operators should also evaluate suppliers' innovation pipelines, particularly in clean-label and plant-based offerings, to stay ahead of consumer trends. Energy costs for frozen storage (approx. 69.4 kWh per cubic meter annually) represent a significant operational consideration, especially in regions with volatile energy prices.
The balance of evidence favors a cautiously optimistic outlook for the frozen food market, with steady 5.9–6.3% growth driven by convenience and technology. The strongest counter-argument is that consumer perception of frozen food as inferior could cap growth in developed markets, but this is being mitigated by IQF and clean-label innovations.
Our analysis suggests three actionable strategies:
Evidence that would change our conclusion: a sustained decline in consumer trust (e.g., >50% perceiving frozen as less healthy) or a sharp spike in energy costs that erodes margins across the value chain.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted 45 in-depth interviews across the value chain, including raw material suppliers, specialized frozen food producers, contract formulators, cold-chain logistics providers, and global distributors. Decision-makers interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring insights from procurement, innovation, and market strategy.
We triangulated primary insights with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized industry associations such as the American Frozen Food Institute (AFFI) and the Global Cold Chain Alliance. These sources validated trade flows, capacity expansions, and technology trends.
Our market sizing employs simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling. This dual approach ensures robustness and captures both supply-side and demand-side dynamics.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025/2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |
| Aspects | Details |
|---|---|
| Study Period | 2020-2034 |
| Base Year | 2025 |
| Estimated Year | 2026 |
| Forecast Period | 2026-2034 |
| Historical Period | 2020-2025 |
| Growth Rate | CAGR of 5.9% from 2020-2034 |
| Segmentation |
|
The global frozen food market was valued at 561.5 Billion in 2026 and is projected to reach 841.5 Billion by 2033, growing at a 5.9% CAGR. North America leads with 37.5% revenue share, while Asia-Pacific is the fastest-growing region.
Key trends include rising demand for clean-label and plant-based frozen products, air-fryer-compatible snacks, and the expansion of quick-commerce and direct-to-consumer meal kits. IQF technology is enhancing product quality and driving premiumization.
Asia-Pacific is the fastest-growing region, with India alone projected to grow at 12.86% CAGR (2026–2034). Urbanization, rising disposable incomes, and government cold-chain investments are key drivers.
Leading companies include Nestlé S.A., Unilever, Tyson Foods, Conagra Brands, McCain Foods, Nomad Foods, and regional players like Mother Dairy (Safal) in India. Competition centers on innovation, distribution, and cold-chain efficiency.
Consumer perception of frozen food as less fresh and nutritious remains the primary restraint. Surveys show ~40% of U.S. consumers believe frozen food tastes worse than fresh, limiting adoption in fresh-preference markets.
Our rigorous research methodology combines multi-layered approaches with comprehensive quality assurance, ensuring precision, accuracy, and reliability in every market analysis.
Our analysis is built on a 70/30 primary-to-secondary research split. We conducted 45 in-depth interviews across the value chain, including raw material suppliers, specialized frozen food producers, contract formulators, cold-chain logistics providers, and global distributors. Decision-makers interviewed included VP of Sourcing, Heads of R&D, Technical Directors, and Commercial Operations Leads, ensuring insights from procurement, innovation, and market strategy.
| Stakeholder Role | Interview Share (%) |
|---|---|
| Procurement & Sourcing Leads | 35% |
| R&D & Innovation Heads | 30% |
| Commercial Operations Leads | 20% |
| Quality & Regulatory Directors | 15% |
| Company Type | Representation (%) |
|---|---|
| Frozen Food Producers | 45% |
| Raw Material Suppliers | 25% |
| Distributors & Retailers | 20% |
| Cold-Chain Logistics | 10% |
We triangulated primary insights with official multilateral trade databases (UN Comtrade, WTO, US ITC, Eurostat), corporate annual filings (10-K, SEC filings, investor presentations), patent databases, and recognized industry associations such as the American Frozen Food Institute (AFFI) and the Global Cold Chain Alliance. These sources validated trade flows, capacity expansions, and technology trends.
Our market sizing employs simultaneous top-down (macroeconomic and segment allocation) and bottom-up (manufacturer capacity, pricing, and end-use consumption) modeling. This dual approach ensures robustness and captures both supply-side and demand-side dynamics.
| Dimension | Analytical Scope | Methodology Applied | Validation Level |
|---|---|---|---|
| Base-Year Market Size | Value in USD for 2025/2026 | Bottom-up production & revenue triangulation | High |
| Forecast Horizon | 2026–2033 compound projection | Historical CAGR, regression analysis & demand elasticity | High |
| Regional Distribution | Regional share breakdown | Cross-border trade flow analysis & regional consumption | High |
| Competitive Landscape | Leading market players | Annual reports, capacity mapping & commercial filings | High |